


Circular 78/2021/TT-BTC on electronic invoices has been replaced by Circular 32/2025/TT-BTC effective from June 1, 2025. Therefore, businesses should not use Circular 78 as the sole basis for creating or processing invoices currently in circulation. From July 1, 2026, Circular 91/2026/TT-BTC will come into effect within the framework of new regulations on electronic invoices and electronic documents.
Circular 78 still needs to be consulted when reviewing records from the previous period. Accountants need to separate two tasks: determining the regulations in effect at the time the invoice was created and determining the regulations applicable to the processing operation being performed.
Is Circular 78 on electronic invoices still in effect?
No longer applicable under current regulations: Clause 1, Article 12 of Circular 32/2025/TT-BTC stipulates that Circular 78 will be replaced from June 1, 2025. This date is different from July 1, 2022, the date Circular 78 came into effect.
| Mold | Text and meaning | What should I do when searching? |
|---|---|---|
| 17/09/2021 | The Ministry of Finance issued Circular 78/2021/TT-BTC, guiding the 2019 Tax Administration Law and Decree 123/2020/ND-CP on invoices and supporting documents. | Verify the correct number, year, and issuing authority; avoid confusing it with another Circular 78. |
| 07/01/2022 | Circular 78 is now in effect. | Place the text content within the context of the current phase of electronic invoicing implementation. |
| 01/06/2025 | Circular 32/2025/TT-BTC is effective and replaces Circular 78. | Do not continue providing guidance on new professional practices solely through Circular 78. |
| 01/07/2026 | Circular 91/2026/TT-BTC, now in effect, stipulates several provisions regarding electronic invoices and electronic documents within the framework of Law 108/2025/QH15 on Tax Administration and Decree 254/2026/NĐ-CP. | Consult the current regulations according to the type of document, transaction, and time period. |
It can be compared directly. Article 12 of Circular 32/2025/TT-BTC in the Official Gazette and validity information of Circular 91/2026/TT-BTC. The replacement of a document does not automatically invalidate all invoices issued during the period in which that document is in effect.
Download the full text of Circular 78 and select the correct document for comparison.
Use the full official text to check the terms, appendices, and context of the old document. A summary cannot replace the full terms and conditions when a conclusion is needed for a specific transaction.
Open the full text of Circular 78/2021/TT-BTC — PDF
This PDF document, issued in 2021, is for reference only and is not a consolidated guide to all current invoicing procedures.
| Situation | Comparison direction | Points to avoid |
|---|---|---|
| Check invoices issued during the period when Circular 78 was in effect. | Keep records of the invoice date, type, original data, and transaction details; consult applicable regulations when the transaction occurs. | Applying all the requirements of a later-issued document to an older file without checking the transitional provisions. |
| Create a new invoice. | Refer to current regulations and specific rules governing sales and service provision activities. | Reuse the deadlines, notification templates, or procedures from the old Circular 78 guidelines. |
| Discovering errors in old invoices at the present time. | Separate the original invoice date from the discovery date and the processing date; check the relevant processing and transitional regulations. | Concluding that an invoice must be canceled, adjusted, or replaced simply because the original invoice was issued previously. |
| Change software or service provider. | Verify the ability to transfer original data, status history, access rights, and registration records. | Consider switching software as a reason to delete records or reissue invoices in bulk. |
For example, an accountant discovers an invoice issued in 2024 with incorrect information in 2026. The record needs to clearly state both dates. It's not possible to simply consult Circular 78 and immediately perform a cancellation or replacement operation while ignoring the applicable handling regulations at the time of the action.
What specific guidelines were provided in Circular 78?
Key content areas include invoicing authorization, invoice forms and symbols, certain invoicing and processing procedures, invoices from cash registers, and service provider criteria. The following explains the role of Circular 78 during the implementation phase; when implementing new procedures, it is necessary to refer to the current regulations.
Authorization for issuing electronic invoices
Circular 78 provides specific guidance on sellers authorizing third parties to issue invoices. Authorization is not simply about handing over software accounts to others: it requires checking the conditions of the parties, the scope of authorization, the written agreement, and the notification procedures as stipulated in the applicable period.
When reviewing old authorization records, gather the contract or agreement, information on the authorizing party and the authorized party, the type and symbol of the invoice, the purpose, the term, and the payment responsibility. Compare these details with the actual invoice and the registered data, rather than just checking for signatures on the contract.
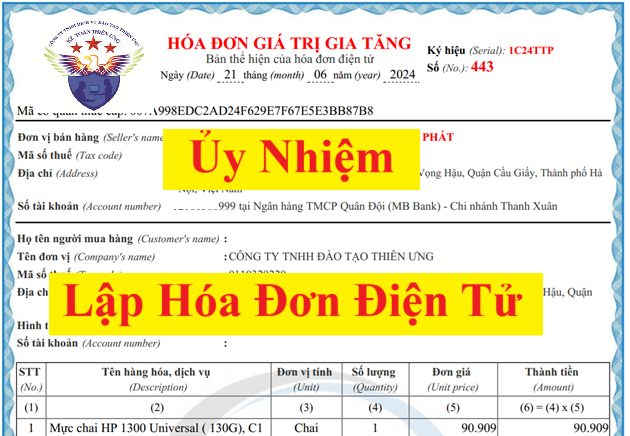
The invoice number and the invoice symbol are two different pieces of information.
The invoice number indicates the type of invoice; the symbol helps identify other attributes of the invoice according to the relevant regulations. Do not combine both into a single code and then arbitrarily interpret each letter to represent a profession.
For example, when reading a document containing the string "1C25TAA," it's necessary to separately identify the denominator and the symbol from the document data. Compare the symbol structure in the applicable document to correctly interpret the invoice's attributes, instead of inferring from the seller's business name.
To check the details of each section, refer to Article 4 and the appendix in the full text of Circular 78 above if you are reviewing files related to the period in which this document is being applied. For new procedures, compare the structure in the current document.
Time of creation, digital signing, and data transfer
These are related but not synonymous steps. When reviewing records, separately record the time the transaction occurred, the date of creation, the time of signing, and the status of data transfer to the tax authority. A guideline on data transmission deadlines does not automatically allow for postponing the invoice creation date.
Activities with specific regulations, such as banking services, should be checked according to the type of service and corresponding terms. Do not use authorization regulations to answer the question of when invoices are issued, nor infer the issuance date from internal payment schedules.
Handling erroneous invoices
Circular 78 contains provisions on handling errors within the legal context while the document is still in effect. It does not transfer any old guidelines regarding Form 04/SS-HĐĐT, service cancellation, adjustment, or replacement into a general procedure applicable today.
When an error is detected, clearly identify which field is incorrect, whether it affects the amount or tax, which system the invoice belongs to, and whether there is any prior processing documentation. (Procedure) Categorize errors and choose how to handle electronic invoices. This helps in verifying the situation before proceeding. Keep the original invoice and related documents to track the relationship.
Invoice generated from cash register
This is a specific group of invoices with unique data creation and transfer characteristics; it's not just another name for all electronic invoices. When reviewing old records, it's crucial to correctly identify the registered subject, invoice type, and actual data; when implementing new systems, it's necessary to check the current requirements for the unit's business operations.
The requirement for digital signatures for one type of invoice cannot be used to exempt all other types of invoices from this requirement. Nor does it mean that the system's ability to send data using a specific method allows for optional post-transaction invoicing.
Criteria of the service provider organization
It's important to distinguish between the solution provider and the organization that receives, transmits, and stores invoice data for the tax authorities. These two roles do not have the same obligations or criteria. Therefore, a single number of personnel should not be used to conclude that a provider meets all requirements.
When selecting or reviewing service contracts, request clarification on the provider's role, responsibilities for data transmission, storage, and delivery; how errors are recorded, interruption support is handled, and contract termination is carried out. These are operational checks, not certifications of the provider's compliance with the law.
How does Circular 78 differ from Decree 123 and Circular 32/2011?
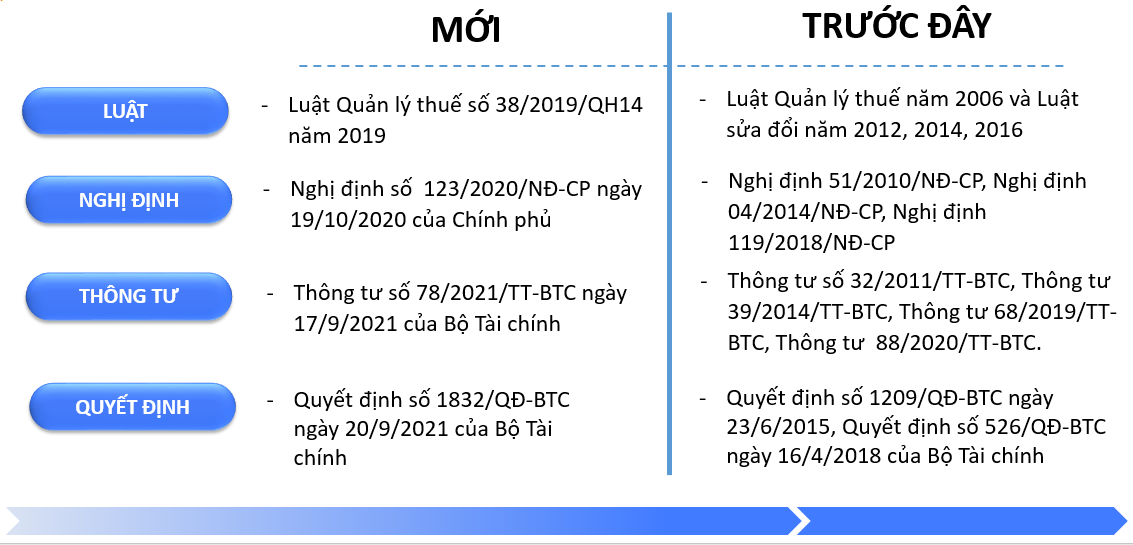
Circular 78 is a guiding document, not a replacement for Decree 123/2020/ND-CP. Circular 32/2011/TT-BTC actually belongs to the earlier phase of guidance on electronic invoices; it is necessary to read the year number correctly to avoid confusion with Circular 32/2025/TT-BTC.
| Document | The role of searching | It should not be interpreted as |
|---|---|---|
| Decree 123/2020/ND-CP | The regulatory framework regarding invoices and supporting documents is guided by Circular 78 for the corresponding period. | “"The previous regulations have been superseded by Circular 78.". |
| Circular 32/2011/TT-BTC | The old guidelines for creating, issuing, and using electronic invoices. | Circular 32 was issued in 2025. |
| Circular 78/2021/TT-BTC | Guidelines on certain aspects of invoices and supporting documents; effective from July 1, 2022, and superseded from June 1, 2025. | This is the sole basis for all invoices being created or processed. |
| Circular 32/2025/TT-BTC | This document replaces Circular 78 from June 1, 2025. | This document has the same content or scope as Circular 32/2011. |
Comparisons regarding transition deadlines, issuance notices, invoice numbers, or transitional processing are only meaningful when applied to the correct period. Do not use a comparison table between the two old regulations to decide on a current transaction.
In what order should accountants review invoice records and procedures?
Starting with the documentation and transaction timing, then identifying the basis, classifying the work, and checking the results. Don't start by choosing an action on the software and then looking for rules to legitimize that action.
- Gather the documents. Retain the original invoice file, including the copy, date, contract or order, delivery/acceptance documents, and processing records. Separate the file under review from newly issued invoices.
- Identify the timeline and type of transaction. Record separately the date the original invoice was created, the date the error was discovered, and the expected date for correction. Determine whether this is a new invoice, a data check, or an error correction.
- Choose the appropriate basis. Check the relevant legal documents, industry/sector regulations, and transitional provisions. If the situation is unclear, consult the tax officer or competent authority for confirmation before proceeding.
- Compare the configuration and data. Verify the registration details, template/symbol, creator/approver permissions, and data transmission status; request clarification from the provider regarding any discrepancies.
- Perform the action and leave a trace. Only perform actions after the plan has been determined; save original documents, processed documents, system feedback, and the approver's information for future reference.
For example, a department wants to reuse a configuration named “TT78” in the software. The configuration name does not provide sufficient justification for its application. The person in charge needs to check the functional version, invoice type, transaction time, and current implementation guidelines before releasing it.
Frequently Asked Questions about Circular 78/2021/TT-BTC
When did Circular 78 come into effect and when will it be replaced?
Circular 78 came into effect on July 1, 2022. Clause 1, Article 12 of Circular 32/2025/TT-BTC stipulates that Circular 78 will be replaced from June 1, 2025. When handling current matters, it is necessary to check the currently effective regulations and relevant transitional provisions.
Do all invoices issued under the old regulations need to be reissued?
Do not automatically reissue documents simply because the text has been replaced. The date of creation, the accuracy of the records, and the transitional regulations must be checked. If errors are found, choose the appropriate course of action for the situation instead of reissuing documents en masse.
Can the guidelines for canceling invoices in Circular 78 be applied now?
Do not apply mechanically. Separate the original invoice date from the processing date, identify the type of error and relevant applicable regulations before deciding to cancel, adjust, or replace.
Does Circular 78 replace Decree 123?
No. Circular 78 provides guidance on certain provisions within the framework of the 2019 Tax Administration Law and Decree 123/2020/ND-CP. The guiding circular should not be considered a substitute for the decree.
Does purchasing invoicing software guarantee full compliance?
No. Businesses still need to correctly define the business process, timing, data, and audit responsibilities. When choosing a solution, clarify the scope of functionality, configuration, and update support; do not consider a marketing commitment as the legal conclusion to every transaction.





