


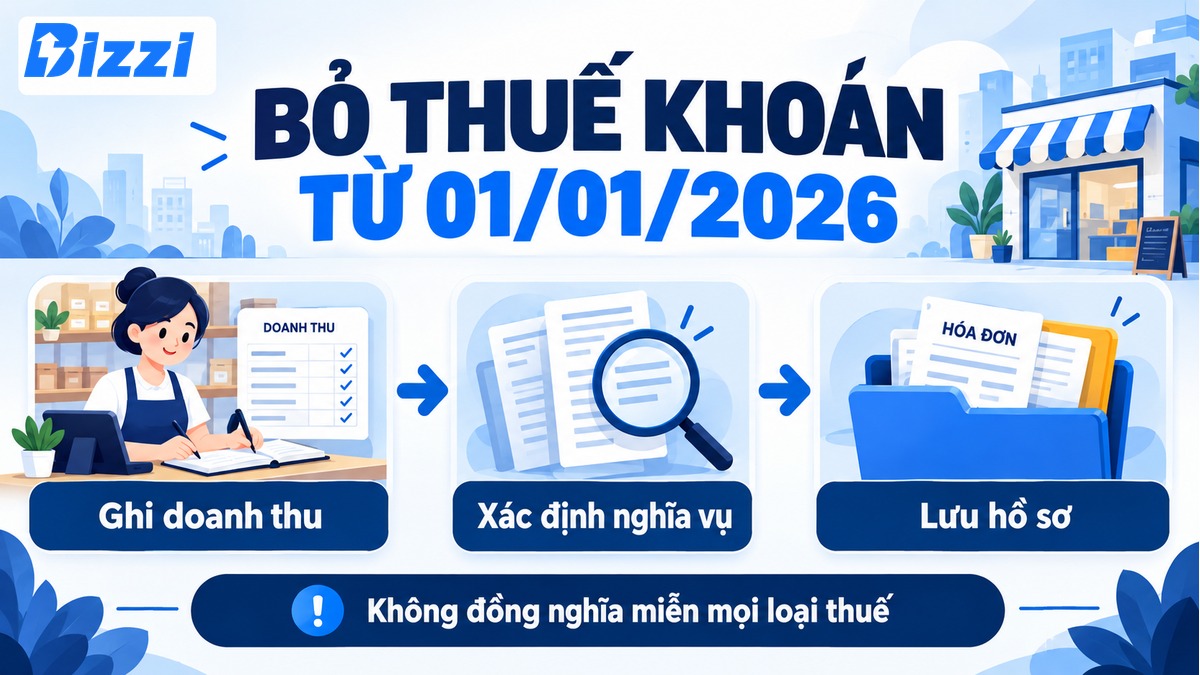
Household businesses and individual business owners will no longer be subject to the lump-sum tax method from January 1, 2026. Abolishing the lump-sum tax system is a change in how tax obligations are determined and managed, not an exemption from all taxes for household businesses. What needs to be done is to record actual revenue, correctly identify your situation, prepare invoices, and complete the necessary paperwork according to applicable regulations.
For households operating in 2026, start with sales figures and submitted records. Do not continue using the old quota or choose a declaration form simply because you used it in 2025.
When was the lump-sum tax abolished, and does it also apply to household businesses?
The effective date is January 1, 2026, according to Clause 6, Article 10 Resolution 198/2025/QH15. Households and individual businesses now fulfill their tax obligations according to tax management laws, instead of relying on a fixed tax amount as before.
Three things need to be separated: eliminating the lump-sum tax method, determining whether there is tax payable, and fulfilling the documentation obligations. A household not required to pay VAT or personal income tax based on revenue thresholds may still have to report revenue and retain data to prove their case.
| Problem | The understanding needed | What businesses should be inspected? |
|---|---|---|
| Contract method | Not applicable from January 1, 2026. | Do not use last year's contract figures instead of this year's data. |
| Tax payable | It depends on the type of tax, revenue, activity, and method of application. | Determine VAT and personal income tax separately; see other obligations if any. |
| Bill | There are specific regulations regarding the target audience and forms of use. | Compare revenue and business characteristics, don't just look at the "small business" label. |
| Records and documents | Fact-based data serves as the basis for determining obligations and accountability. | Track revenue, documents, notifications, and receipt results. |
Previously, the fixed-rate system helped some households estimate their tax payments but did not accurately reflect all sales fluctuations. The new management method requires clearer data; in return, household heads can compare the tax amount with actual sales instead of just tracking a fixed rate.
What is the difference between revenue of 1 billion VND or less and revenue of over 1 billion VND?
In the 2026 regulations, Decree 141/2026/ND-CP The threshold for VAT and personal income tax for household and individual businesses has been raised from VND 500 million to VND 1 billion per year. The decree stipulates that it will take effect from January 1, 2026. This is the threshold for the obligations specified in the amended document, not the threshold for exemption from all taxes.
If annual revenue is 1 billion VND or less.
For activities falling under this threshold, households are exempt from VAT and personal income tax on business income as per relevant regulations. Households still need to determine, monitor, and report actual revenue; the lack of tax payable cannot be considered a reason to abandon sales records.
Keep a record of revenue by channel and relevant reconciliation statements. If you have already declared and paid taxes according to the thresholds before Decree 141 was adjusted, check the handling of the paid amount according to transitional provisions; do not arbitrarily deduct it from another tax amount.
If annual revenue exceeds 1 billion VND
It is necessary to determine VAT and personal income tax obligations based on the activity and method applied. A single rate should not be used for all businesses selling goods and services or those engaged in mixed activities. Nor should it be assumed that all households calculate tax based on "revenue minus expenses": the method for determining the tax base may vary between cases.
Before preparing the documentation, finalize three key pieces of data: revenue for which period, which activity it pertains to, and which method is being used. If selling multiple product categories or providing both sales and services, the data needs to be separated so that the person preparing the documentation can choose the correct calculation method.
Revenue is different from the remaining cash in the account. Cash transferred after deducting fees, collected payments, transfers between accounts, and sales revenue can be different data. Compare the nature of each cash flow and avoid using bank balances alone as revenue.
What should household businesses do after the abolition of the flat-rate tax?
Follow these five steps to go from sales data to records and submission results. Each step should have verifiable output, rather than buying software first and then figuring out how to import the data.
Step 1. Compile revenue and business locations.
Create a list of stores, online channels, e-commerce platforms, and revenue-generating activities. Clearly state the data source for each channel: sales records, order reports, invoices, platform reconciliation statements, and bank statements.
- Set the same time period when adding up the data.
- Distinguish between orders, customer payments, refunds, and platform transfer fees.
- Mark the amount that has already been deducted, declared, or paid on behalf of the organization or platform for verification; do not add it again as a new sales transaction.
- Save the explanation for the discrepancy, instead of correcting the total to match the statement.
Hypothetical example: A household has cash sales of 350 million VND at the store, bank transfer sales of 450 million VND at the store, and online sales of 120 million VND. If the three groups do not overlap and represent the total revenue to be aggregated for the year, the total is 920 million VND. The online sales report, after fees, is used for reconciliation purposes and is not added to the 920 million VND figure.
Step 2. Determine obligations based on actual data.
Use aggregated revenue to check thresholds, operations, and tax calculation methods. If cumulative figures are increasing rapidly, review them during the year instead of waiting until the end of the year to discover that a different situation has arisen.
With the example of 920 million VND, it is first necessary to check whether the data covers the entire year, all channels, and the correct revenue scope. The threshold result does not replace checking the invoice obligations or other taxes for the specific activity.
Households with activities on the floor should be viewed separately. How to determine tax filing and payment responsibilities when doing business online.. The fact that the platform deducts an amount does not mean that all of the household's obligations have been fulfilled.
Step 3. Prepare the appropriate invoices and tracking records.
Compare the usage scenarios for invoices before choosing a tool. Then determine who records revenue, who creates the invoice, who verifies the data, and where the documents are stored. One person may handle multiple tasks, but it's crucial to know exactly which steps have been completed.
With the revenue-based calculation method, sales data is the focus; having expense documents does not automatically make expenses deductible from taxable revenue. Cases where the calculation method considers expenses require specific documentation and conditions. Choose accounting books according to the current accounting system suitable for the household; do not assume all households use the same set of books as businesses.
Step 4. Prepare, submit documents, and verify payment.
- Verify the registration information, filing period, and applicable case with the directly managing tax authority.
- Choose the current form for that period and obligation; avoid reusing an old form just because the name is similar.
- Compare the figures with the revenue statement, invoices, and any deductions or payments made on behalf of others, if applicable.
- Submit your documents through the channels supported by the tax authorities, save the receipt notification, and view the processing results.
- If any tax liability arises, make the payment as required, retain the documentation, and check the status.
Submitting the application does not guarantee successful payment; the transferred money does not prove that the application was submitted on time or met the eligibility criteria. Both sets of evidence should be kept for comparison in case of discrepancies.
Step 5. Review periodically and when changes occur.
Regularly compare revenue, invoices, cash received, and tax declaration results. When opening new locations, changing business activities, temporarily suspending or terminating business, check the corresponding procedures before unilaterally abandoning the filing period.
Schedule tasks with designated personnel and inspection dates. If hiring a service, clearly agree on the client's role, the service provider's role, and how results will be delivered; data responsibility should not be based solely on a "done" message.
Does abolishing the lump-sum tax require all households to purchase cash registers?
It is not possible to infer the need to purchase a specific piece of equipment simply by abandoning the lump-sum payment method. It is necessary to determine which type of invoice the household uses, the data transmission method, and the actual operating conditions.
According to Tax Department's guidelines on invoices for household businesses. According to Decree 254/2026/ND-CP, households with annual revenue exceeding 1 billion VND or those selling assets requiring registration of ownership or usage rights are required to use electronic invoices. The type of invoice, whether a coded invoice or an electronic invoice generated from a cash register connected to the tax authority, must be verified against the specific application conditions of the activity; households cannot choose arbitrarily. Households outside these categories can still register if they wish, subject to the prescribed conditions.
Tax thresholds and invoice conditions need to be checked separately. If the revenue is exactly 1 billion VND, it is necessary to compare it with the group of 1 billion VND or less instead of the group of over 1 billion VND; in the case of selling assets requiring registration of rights, the corresponding invoice conditions must still be checked.
If you need to go into detail about the process of creating and sending invoices, see Instructions for issuing electronic invoices for household businesses.. If you are unsure which type of invoice to use, confirm with the tax authorities or a supporting unit before implementation.
Before signing a billing service contract, clearly ask about the type of invoices you need, whether your existing equipment supports them, the total cost, how to export data, and who will provide support in case of errors. Don't choose based solely on promises of "guaranteed tax compliance.".
What documents do I need to keep so I don't have to redo them when filing the declaration?
The records should help auditors trace a revenue or expense from its source to the final tax return. They can be organized by period and by sales channel, as long as they are easily accessible and the original data is not lost.
| File group | What is it used for testing? | Common mistakes |
|---|---|---|
| Sales reports, orders, and invoices. | Revenue generated, adjusted transactions, and channel data. | Adding both the floor sales and the floor money converts into two sales transactions. |
| Statements, receipts, and reconciliations | Which cash flow is associated with which transaction; the remaining difference. | Take all the money deposited into the account as revenue without categorizing it. |
| Invoices and payment vouchers | The nature of the expenditure and the conditions of the method being applied. | It is assumed that any expenditure is deductible when calculating all types of taxes. |
| The application has been submitted and the processing notification has been received. | The documents are accepted or require additional information, depending on the timeframe and type of obligation. | Only keep the screenshot you sent; do not view the received result. |
| Payment, deduction, or substitute payment receipt | Which payments have been made, the amounts, and the details need to be verified. | Duplicate payments are made due to a failure to track payments made by other organizations. |
A discrepancy tracking table should be maintained: transaction, data source, amount, cause, handler, and result. When figures change, record the adjustment to explain why the final figure differs from the original.
How should the household head, accountant, and purchasing company coordinate?
The major difficulty in transitioning away from lump-sum tax often lies in the input data and the handover process, not just in the tax return submission itself. Clearly defined responsibilities will reduce the need to wait until the deadline to search for documents.
With homeowners and salespeople
Establish a standardized method for recording transactions at the start of each shift, handling order cancellations or refunds, and determining who checks revenue at the end of the day. If you're new to using digital tools, test the process on a few transactions and check the data retrieval capabilities before expanding.
Implementation costs should be balanced against scale: equipment, services, training time, and support. Clear data helps track sales and prepare documentation better, but it doesn't automatically guarantee loan security or eliminate tax risks.
With an accountant or service provider.
Submit data requests in batches, clearly explaining why the data is needed and confirming any missing information. Prioritize processing cases involving threshold changes, mixed operations, multiple locations, or floor revenue with deductible expenses. Do not apply a single set of documents to all households.
For businesses purchasing goods from household businesses.
Agree in advance on buyer information, invoices, and transaction documents to be received. Businesses must still independently verify their eligibility for recognition, payment, and tax obligations; invoices issued by individual households do not automatically meet all conditions for deductible expenses.
Frequently Asked Questions about Abolishing the Fixed Tax for Household Businesses
Does abolishing the lump-sum tax mean that households with incomes under 1 billion VND no longer need to file any paperwork?
No. It's necessary to distinguish between VAT and personal income tax thresholds and the obligation to report revenue, invoices, and other obligations, if any. Households still need to monitor actual figures to determine their specific situation.
Can the old flat-rate tax be used to continue paying in 2026?
Do not use the old fixed rate to determine your tax liability as stipulated in the regulations effective from January 1, 2026. If the system still displays the old amount due or there is a discrepancy, check the period and details with the tax authority before making payment.
Is it true that any expense receipt can be deducted when calculating household taxes?
No. The type of tax and the method being applied must be identified. Expenses are not automatically deductible from revenue when using a percentage-based calculation method; separate documentation is required for conditional expense deductions.
How do you track sales both in-store and online?
Monitor each channel and compile a summary to avoid duplicate transactions. Record revenue, fees, actual received funds, and any platform taxes deducted or paid on behalf of others, if applicable, to ensure compliance with obligations.
Is it necessary to immediately convert to a business entity after the elimination of the lump-sum tax system?
The termination of the contract-based system should not be considered an automatic notification of a change in registration type. If conversion to a business entity is being considered, a separate assessment of scale, governance, accounting system, and applicable procedures is required.
Can the old information stating the threshold of 200 or 500 million VND be used for the entire year of 2026?
A figure should not be applied separately from the type of obligation and the timeframe. Decree 141/2026 amended the relevant threshold in Decree 68 to VND 1 billion. It is necessary to read the current regulations to ensure the correct period and type of tax before preparing the application.
If households need a tool for generating outgoing invoices, they can explore Bizzi's electronic invoicing solution and clearly discuss the type of invoice, transaction scale, equipment, and implementation requirements. The decision should be based on the identified needs.





