Decree 70/2025/ND-CP amended regulations on invoices and documents effective from June 1, 2025. From July 1, 2026, this document ceased to be in effect according to Article 43 of Decree 254/2026/ND-CP. When reviewing the new provisions of Decree 70, accountants need to distinguish between regulations from the previous period and those currently applicable to their accounting practices.
The 2025 changes directly relate to the timing of invoice creation and signing, invoices from cash registers, buyer information, error handling, and registration. Below are 13 content groups to help compare old records, identify changes, and determine what needs to be re-checked on the system.
Is Decree 70/2025/ND-CP still in effect?
No. Decree 70 expires on July 1, 2026. Article 43 of Decree 254/2026/ND-CP This regulation sets an effective date, simultaneously terminating the validity of Decree 123/2020/ND-CP, Article 1 of Decree 41/2022/ND-CP, and Decree 70/2025/ND-CP.
| Timeline | The meaning of searching | What needs to be distinguished |
|---|---|---|
| 20/03/2025 | Date of issuance of Decree 70/2025/ND-CP. | The date of issuance is different from the effective date. |
| 01/06/2025–30/06/2026 | During the period when Decree 70 was in effect, Decree 123 was amended. | The new provisions for 2025 must be read in conjunction with the underlying regulations and conditions of each specific case. |
| From July 1, 2026 | Decree 254/2026/ND-CP is in effect; Decree 70 and Decree 123 are no longer in effect. | Current practices require referencing the new regulations, not just the 2025 guidance documents. |
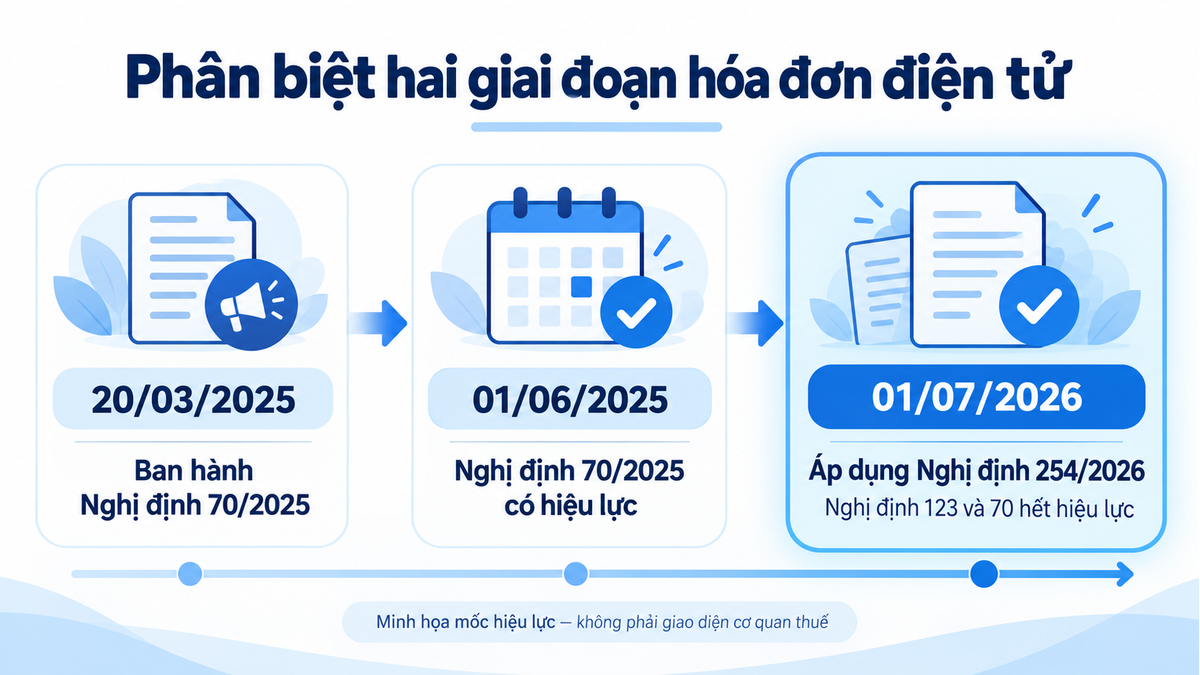
The expiration of the document does not mean that all previously issued electronic invoices automatically become invalid or must be canceled. Transaction records, the time of occurrence, and the processing method used must be separated. With the changes effective from July 2026, businesses can make comparisons. New points of Decree 254/2026/ND-CP before updating the process.
13 groups of changes to Decree 70 have been implemented since 2025.
According to Introduction from the Tax Department regarding invoices and supporting documents., The changes to Decree 70 are summarized below according to 13 operational groups. When reviewing records during the period when the document is in effect, accountants need to read both the amended regulations, the clarified regulations, and the conditions of application.
1. Clarifying the timing of invoicing for exports and certain services.
A notable change is the timing of invoicing for exported goods, including those processed for export: the seller determines this timing, but it must be no later than the next business day after the goods are cleared through customs. Therefore, tracking records must include both the customs clearance date and the invoicing date, instead of relying solely on the date payment is received.
For services, the principle of completing the service delivery is clarified for both service provision to foreign organizations and individuals. In cases where payment is collected before or during the service delivery process, specific regulations must be followed according to the conditions of each case, in addition to the principle of issuing invoices upon service completion.
The decree also adjusts and supplements the timing for certain specific activities. Accountants need to properly categorize these activities before establishing an invoicing schedule.
- High-volume, frequently occurring services requiring reconciliation: Only cases falling within the specified scope will apply the reconciliation completion deadline, with a limit of no later than the 7th of the following month or 7 days from the end of the agreed period. Businesses need to determine if their service falls within the group subject to the reconciliation period before using this deadline.
- Insurance: linked to the point in time of revenue recognition according to insurance business law.
- Lottery: This is linked to the period before the next draw after unsold tickets have been recalled as per regulations.
- Casino, electronic games with prizes: It has a billing mechanism based on daily revenue and submits data using the corresponding template; the benchmarks of conventional retail are not applied.
- Credit services, foreign exchange, taxi services, and medical examinations and treatment covered by health insurance: The benchmark should be determined separately based on the nature of the service, interest collection period, transaction, or settlement, instead of using the date the money is deposited into the account as a general benchmark.
For example, when reconciling records in 2025: if an export is cleared on one business day, the accountant must check the next business day limit, even if the customer hasn't paid. For service contracts with reconciliation, it's necessary to confirm whether the service falls within the applicable category and record the reconciliation period agreement. When processing current transactions, re-verify this. Invoice timing varies depending on the type of transaction..
2. Separate the invoice creation date from the digital signature and data transfer.
Decree 70 clarifies the situation where the time of digital signing differs from the time of invoice creation. In this case, the digital signing and submission to the tax authority for code issuance or data transfer must be done no later than the next working day from the time of invoice creation, except in cases where data is submitted as part of a summary table subject to separate regulations.
The timestamp of signing or data transmission does not alter the obligation to create the invoice at the correct time. For example, the system allowing signing to be completed on the next business day does not mean that the invoice can be postponed from the date it should have been created when the transaction occurred. When comparing, the three timestamps—creation, signing, and data transmission—should be examined separately.
The 2025 regulations also differentiate between the tax filing period for sellers based on the date of issuance and for buyers when they receive a complete and valid invoice. The date the email is sent to the customer should not be used as the sole evidence of the date of issuance or data transmission to the tax authorities.
3. Expand the range of users of cash register invoices.
Decree 70 expands the scope of electronic invoices generated from cash registers connected to and transferring data with the tax authorities. The scope includes households and individual businesses that meet the conditions referenced in the Law on Tax Administration, including cases with annual revenue of 1 billion VND or more, and businesses engaged in direct sales to consumers as stipulated.
The business sectors mentioned include retail (with specific exceptions); food and beverage, restaurants, and hotels; passenger transport; entertainment and recreation; and certain personal services. The revenue threshold of 1 billion VND needs to be considered in conjunction with the subjects, industries, and conditions of regulations regarding invoices from cash registers; other tax obligations have their own specific basis.
Regarding implementation, the key areas to check are the target audience, the actual industry, and the data connectivity capabilities of the solution being used. Buyer information on invoices from cash registers has specific conditions, including cases where the buyer requests it; the rules of regular invoices should not be applied directly to these.
4. Allow foreign suppliers to voluntarily register to use electronic invoices.
The decree adds foreign suppliers without a permanent establishment in Vietnam who engage in e-commerce, digital platform-based businesses, and other services to the list of those who can voluntarily register to use electronic invoices. Registration under this regulation is voluntary for foreign suppliers falling within the aforementioned scope.
Expanding the scope of eligible entities does not mean that every invoice from a foreign supplier automatically becomes a Vietnamese value-added tax invoice. When comparing records, it is necessary to identify the registering entity, the type of invoice, and the actual transaction. This is also a different issue for Vietnamese businesses exporting goods abroad.
5. Supplement the list of e-commerce invoices and clarify invoice types according to business activity.
Electronic commercial invoices are added to export activities when exporters meet the conditions for electronically transferring data to the tax authorities according to prescribed standards. If these conditions are not met, electronic value-added tax invoices or electronic sales invoices should be used as prescribed. The conditions for using this type of invoice are linked to export activities and the ability to transfer data according to prescribed standards; selling goods through a trading platform is not sufficient to determine the type of invoice.
For export processing enterprises with business activities other than export processing, the Decree clarifies the type of invoice according to the value-added tax calculation method: the direct method uses sales invoices; the deduction method uses value-added tax invoices. Accountants must separate the business activity and the tax calculation method, and not choose the invoice type based solely on the name of the export processing enterprise.
6. Adjust buyer information and content for specific industries.
Decree 70 updates the content of buyer information, including the use of personal identification numbers or budget-related unit codes in corresponding cases. When the buyer is an individual or a budget-related unit, the identification data needs to be appropriate for the entity, not just checking the business tax code field.
Some industries have specific requirements: food and beverage services need to show the food and drinks served; transportation activities require information about the vehicle and route in cases where stipulated. Conversely, some invoices, such as those for the sale of gasoline to individuals not engaged in business or casino operations, have exceptions regarding certain buyer information. In these exceptional cases, accountants still need to verify the mandatory information on the invoice.
Businesses can use the original data to verify invoice templates issued in the past, but should not copy the entire 2025 configuration to 2026. The invoice content must be reviewed according to the applicable text and transaction type.
7. Change the way incorrectly issued invoices are handled.
Decree 70 abolishes the old mechanism for canceling invoices with codes that have been issued but not yet sent to the buyer in order to issue new invoices. The handling method is categorized according to the nature of the error: incorrect name or address but correct tax identification number, as opposed to incorrect tax identification number, amount, tax rate, or tax amount.
The documentation between the parties also needs to be differentiated. For buyers who are businesses, economic organizations, other organizations, households, or individual business owners, if applicable, a written agreement clearly stating the errors must be provided before correction or replacement. For buyers who are individuals, notification is required according to the relevant regulations.
The decree also allows for the processing of multiple incorrect invoices under certain conditions, such as from the same buyer and within the same month, instead of assuming that all incorrect invoices can be grouped arbitrarily. The "not declared" or "not sent to customer" status does not automatically determine how to process them. If you are currently correcting an invoice, select the correct branch within the relevant section. Procedures for notifying, correcting, and replacing erroneous invoices..
8. Clarify discounts, returns, and transactions arising after invoicing.
Quantity or sales-based trade discounts may be adjusted on the invoice of the last purchase or the next period, provided the discount amount does not exceed the value of the goods or services stated on that invoice. If an adjustment invoice is issued with an accompanying list, the seller must retain and provide the list upon request.
This is a different situation from an invoice that was incorrectly issued at the time. Similarly, returns or changes to transactions later require review of records, agreements, and the entity issuing the invoice according to regulations. Accountants should clearly state the reason for the adjustment: correcting incorrect data, determining discounts based on sales volume, or resulting from a return of goods.
For example, a year-end discount due to a customer reaching an agreed-upon purchase level should not be recorded as "incorrect unit price" if the original invoice accurately reflects the transaction at the time it was created. Categorizing the cause helps to correctly link the invoice, statement, and commercial agreement.
9. Add registration checks and invoicing authorization mechanisms.
The registration procedure includes verification and authentication of identification information as required, including data on the representative, phone number, email address, and residential information where applicable. Some applications with potential risks must be verified; submitting a registration does not guarantee immediate acceptance.
The decree allows sellers, including households and individual businesses, to authorize third parties to issue electronic invoices under certain conditions. When authorizing, businesses need to check the documentation, scope of responsibilities, and registration information of the parties involved. The granting of software accounts must be accompanied by the required authorization documents and procedures.
The process of accessing information from subsidiary units also has a regulatory request mechanism. The scope of parent company data that can be accessed depends on the relationship with the subsidiary unit and the access rights granted.
10. Adding cases for discontinuing the use of electronic invoices.
The decree regulates the circumstances under which the use of invoices should be discontinued and the responsibilities of tax authorities in coordinating with relevant parties, relating to the taxpayer's operational status, the use of invoices, or other prescribed grounds. The grounds and timing for discontinuing the use of invoices must be determined on a case-by-case basis and notified by the tax authorities.
When a notification or error occurs that prevents further issuance, the accountant needs to record the notification, determine the basis, scope, and time of application, and then coordinate with the tax officer to resolve the issue. It is not advisable to transfer the invoice to a different account, unit, or document type simply to continue issuing the invoice without clarifying the legal status.
11. Differentiate between canceling invoices, destroying data, and data that needs to be retained.
Decree 70 removes the provision explaining the "cancellation of electronic invoices and documents" from the old regulations, and amends the content related to destruction after the retention period expires. Correcting an erroneous invoice and destroying data after the retention period expires are two different tasks.
After adjusting invoices, businesses still need to retain XML data and processing history to track records. When reviewing an old record, it is necessary to maintain the relationship between the original invoice, the adjusted or replacement invoice, and the explanatory document. For paper documents subject to the transitional regulations of 2026, separate classification is required as mentioned in the section on effectiveness.
12. Adding prohibited behaviors and repealing some old regulations.
The decree clarifies and addresses actions such as forging invoices or documents, or failing to electronically transmit data to the tax authorities as required. Therefore, issuance control must monitor both the invoice content and the data transmission results, not just the PDF version sent to the customer.
Regarding the repeal, Decree 70 removes some provisions of Decree 123, including Clause 10 of Article 3, Point g of Clause 4 of Article 9, Clause 2 of Article 33, Article 37, and some provisions in Articles 50–53. The repeal of the old Article 37 does not mean that electronic documents are no longer managed; the amended, supplemented, and replaced content should be read in the entire document.
Businesses should clearly state the effective date in each internal guideline and replace outdated versions. When configuring software functions, the procedures should be compared with the corresponding regulations.
13. Update tax deduction certificates and electronic receipts.
Decree 70 amends regulations on tax deduction certificates, electronic receipts, and content related to the time of creation, digital signing, formatting, or data transfer. This includes content related to the deduction activities of organizations managing e-commerce platforms and digital platforms within the prescribed scope.
Sales invoices, tax deduction certificates, and fee receipts serve different purposes, so they must be selected according to their intended use. When implementing this, it is necessary to correctly identify the type of document, the issuing entity, and the data to be submitted. For existing paper receipts, it is necessary to check current transitional regulations, not just refer to the guidelines issued in 2025.
Download the text of Decree 70 to compare with old records.
The signed copy of Decree 70 helps to accurately identify the amended content and refer to the relevant clauses when examining transactions from the previous period. When archiving documents for staff to refer to, the applicable period should be clearly indicated, and current guidelines for the ongoing operation should be attached.
Download the PDF version of Decree 70/2025/ND-CP.. When searching for a provision, it's necessary to examine the entire amended version of Decree 123, rather than reading only the amended sentence and applying it to all subjects.
Review the invoicing process after the document changes.
Businesses can review internal configurations, forms, and guidelines in the five steps below. This is a suggestion for internal control; the legal terms and conditions remain determined on a transaction-by-transaction basis.
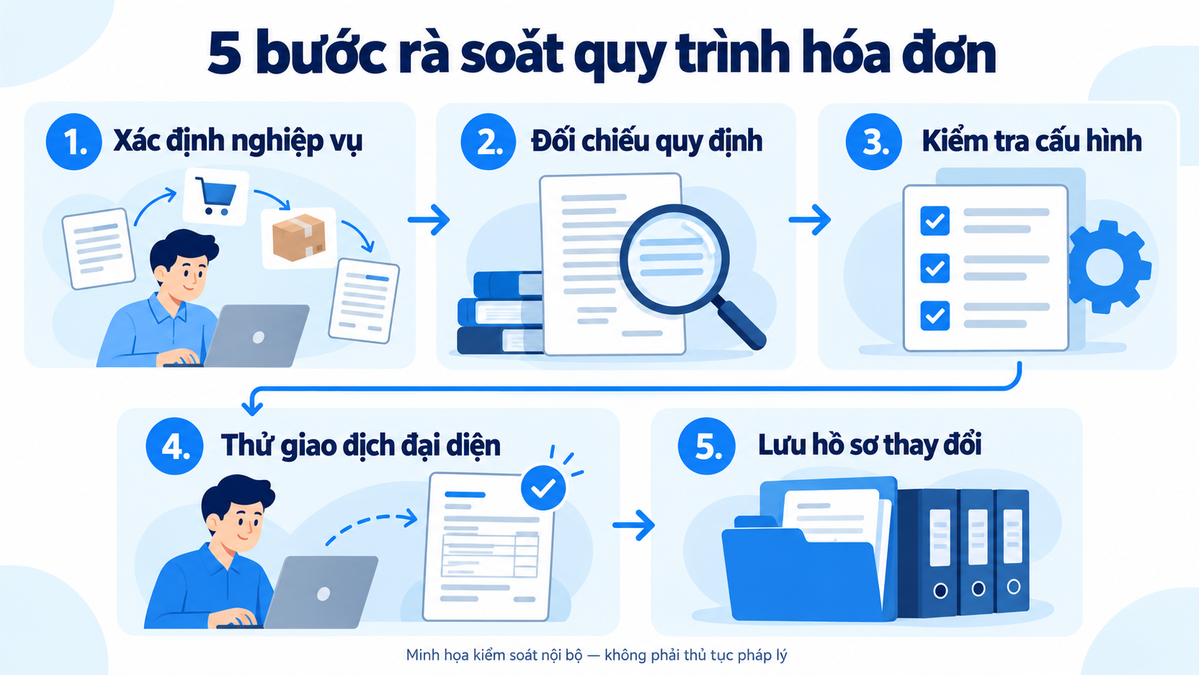
- Finalize the type of transaction and the timeline. Record the delivery date, acceptance date, payment collection date, customs clearance date, or transaction reconciliation date. The required result is documentation proving the transaction milestone, not just the date the accounting data was entered.
- Identify the applicable text and terms. Distinguish between comparing an old invoice and the ongoing processing procedure. The processing method should be based on the date of the original invoice, current regulations, and relevant transitional regulations.
- Check the billing configuration. Verify the subject, invoice type, buyer information, industry, digital signature, and data transmission method. Clearly state whether the invoice was issued from a cash register or through authorization.
- Try a representative transaction before using it widely. Verify the instance, XML data, timestamps, and send/receipt results within the permitted scope. Functional testing must be within the permitted scope and ensure that no invoices are issued for fictitious transactions.
- Maintain a history and keep internal guidelines up-to-date. Record changes, checkers, and replaced documents. In case of errors, link the original invoice to the processing document; for specific transactions, identify the person responsible for verification before issuance.
For example, a guide that still requires “canceling an invoice with an unsent code and then reissuing it” needs to be reviewed before use. The fact that the original transaction dates back to 2025 is not sufficient to conclude that any modifications in 2026 must follow the 2025 function or guidance.
Frequently Asked Questions when looking up Decree 70
When did Decree 70 come into effect?
The document was issued on March 20, 2025, and came into effect on June 1, 2025. From July 1, 2026, Decree 70 will cease to be in effect according to Article 43 of Decree 254/2026/ND-CP. When searching for records, the transaction date should be compared with the period when the document was in effect.
Will Decree 70 still be used to issue service invoices in 2026?
It is necessary to determine the timing and procedures. For current operations from July 1, 2026, the new regulatory framework must be consulted; Decree 70, which is currently in effect, cannot be used solely as a basis. The service provisions in Decree 70 are still useful for reviewing records from the previous period.
Do electronic invoices issued before July 1, 2026 need to be canceled in bulk?
There is no basis to conclude that simply because Decree 70 has expired. A distinction must be made between invoices already issued and unused pre-printed paper invoices and paper receipts subject to transitional regulations. An invoice with errors needs to be checked and handled according to the specific circumstances.
What is the new regulation on electronic invoices effective from July 2026?
Decree 254/2026/ND-CP takes effect from July 1, 2026. When carrying out procedures, it is necessary to compare both the guiding regulations and the corresponding transitional provisions. The changes in 2025 support the comparison of old records; procedures from July 2026 onwards must be checked according to the new regulatory framework.
Compare the invoicing process with the system currently in use.
B-Invoice is Bizzi's electronic invoicing solution. When discussing invoice creation, issuance, and management with Bizzi, businesses should provide the transaction type and data connection requirements to determine the system's configuration, deployment scope, and compliance with current regulations.