


Cost reduction in a business means cutting expenses that don't add value, while maintaining product quality, service capabilities, and fulfilling obligations. The first step is to identify documented waste, calculate the savings after implementation costs, and then assign responsibility for implementation.
A software contract with few users might need to be scaled back. A training program that is helping reduce bugs needs a different evaluation. Both involve budget cuts, but the impact on profitability and operations can be contradictory.
Where should we start cutting costs?
Let's start with the large, recurring, variable expenses that are showing signs of being wasteful. For example: unused software licenses, slow-moving inventory, orders needing rework, or the same data being entered in multiple departments. The largest expense isn't necessarily the easiest to reduce; small expenses that occur thousands of times are also worth considering.
The data for a given period should adequately reflect normal operations, taking seasonality into account. For each expenditure group, record the amount, the department using the funds, the workload, the related contract, and the cause of the expenditure. Simply looking at the higher amount this month compared to the previous month can lead businesses to mistakenly believe that increased sales are due to inefficiency.
| Measure | Results need to be differentiated | How to check |
|---|---|---|
| Cancel licenses for unused software. | Reduce actual expenditures from the effective period. | Compare invoices and termination conditions. |
| Defer payment to the supplier as agreed. | Reducing immediate cash pressure doesn't necessarily mean reducing costs. | Check fees, lost discounts, and payment due dates. |
| Automate a data entry task. | Freeing up working hours only results in savings when expenses are actually reduced. | Measure working hours and determine whether to reduce overtime or avoid hiring additional staff. |
| Reduce budget but keep placing the same orders. | Plans may change; actual costs may not decrease. | Track purchase commitments, received goods, and incurred costs. |
For materials, packaging, or shipping, compare costs per unit of operation. Guidance on Variable costs and how to calculate them based on output. This helps to separate the increase due to volume from the increase due to standard rates or unit prices.
These are some cost-cutting measures that businesses can implement.
The following measures should be selected based on the causes of the cost increase. Businesses can combine several measures, but each action must have data before implementation and standards for evaluation after the change.
1. Purchasing, suppliers, and inventory
Review frequently purchased items, compare needs across departments, and consolidate orders with similar technical requirements where appropriate. Negotiate prices, delivery terms, warranties, payment terms, and minimum order quantities. High discounts may not be beneficial if they require over-purchasing, additional warehouse space, or losses.
When choosing a new supplier, so total cost to get goods ready for useConsider factors such as purchase price, shipping, inspection, defect rate, lead time, and complaint handling costs. Test a small batch before shipping the entire output; for critical inputs, maintain alternative supply options.
For inventory, categorize by sales rate, expiration date, and importance to production. Adjust reorder points, handle slow-moving inventory, and check for discrepancies between physical and data inventory. Reducing inventory too quickly can lead to shortages or increased urgent shipping costs, so monitor both order fulfillment rates and lead times.
2. Process, technology, and processing time
Choose a process with multiple waiting or rework steps, then clearly specify who provides the data, who checks it, and who makes the decisions. Eliminate re-entering the same information, reports with no user, and duplicate review cycles. Retain essential control steps; these can be combined or modified instead of eliminating them entirely.
Before purchasing additional software, inventory your existing tools: the number of accounts granted and in use, any overlapping functions, renewal dates, and data connection costs. A single system is not necessarily cheaper than many specialized tools. Consider data migration, training, operation, and the ability to export data when you stop using it.
Automation is suitable for repetitive tasks with clear inputs and rules. Test it on a small scale, keep people handling exceptions, and measure the rework rate. For time management, reduce meetings that don't require decisions, standardize input forms, and clearly define response deadlines; don't just ask employees to work faster.
3. Personnel, capabilities, and work organization
Compare workload with capacity and schedules to identify areas of understaffing, overcapacity, or mismatched assignments. Cross-training, standardized instructions, and task reassignment can be considered before scaling up the workforce. Retaining key skills also helps limit re-recruitment, training, and service disruption costs.
Outsourcing, remote work, or flexible scheduling are only beneficial when they align with the nature of the work, security requirements, and coordination capabilities. Consider the total cost, which includes service fees, contract management, quality control, and delivery; don't just compare outsourcing costs to the salary of a position.
Changes to wages, contracts, working hours, or employee benefits must be reviewed by the human resources department and qualified personnel as per applicable obligations. Converting a full-time to a part-time position is not a unilateral solution that can be applied in all cases.
For support departments, evaluation should be based on tasks and service level: processing time, errors, backlog of requests, and impact on other departments. The difficulty in directly quantifying revenue doesn't mean the department doesn't create value.
4. Office space, equipment, and costs
Verify the actual usable area, meeting room usage history, machinery, and equipment. Infrequently used assets may be reassigned, shared, or liquidated after assessing needs and authority. Subleasing of premises must comply with the contract and applicable conditions, not solely based on available space.
Renegotiate the size or lease term if the contract allows. If considering shared office space or relocating, factor in additional costs for moving, disruption, travel, storage, and security. A lower rent alone is not enough to conclude that overall costs will decrease.
For electricity, water, and office supplies, meter by area or activity, schedule shutdowns of unused equipment, and address leaks and losses. Standardize the inventory of supplies, allocate them according to needs, and digitize documentation accordingly; record keeping and security requirements must still be met.
5. Production, quality and safety
Measure material losses, defective products, machine downtime, and rework cycles. Prioritize recurring causes such as unstable machine settings, inaccurate production standards, or substandard input materials. Utilize scrap and by-products only when relevant technical, environmental, and safety conditions are met.
Maintenance, training, and quality checks can help prevent larger costs from arising later. ASQ distinguishes between the costs of prevention and assessment and the costs of error.; Therefore, it is necessary to compare the total impact, rather than treating every inspection as a negligible cost.
For example, reducing input inspection costs may save a small amount, but it could lead to the entire production batch being reworked. When trying to change materials or processes, maintain limits on error rates, complaints, and incidents. If costs are reduced but quality or safety exceeds limits, stop, find the cause, and make adjustments.
6. Marketing, customers, and product portfolio
Evaluate marketing channels by trackable business results: customer fit, orders, contribution margins, and service costs. Separate the channel under testing from one with sufficient data. A channel generating few direct orders can still support the exploration phase; consider the buying cycle before ceasing budget allocation.
Content creation, social media, and an in-house team all require time, skills, and tools. Choose whether to do it yourself or outsource based on output quality and total cost; don't assume online channels are free or that in-house staff are always cheaper.
Group customers and products based on their contribution after service costs, return rates, accounts receivable, and relationship retention potential. Do not apply the 80/20 ratio as a guaranteed outcome. Before discontinuing a low-revenue product, consider whether it helps with reselling, retaining customers, or utilizing excess capacity; adjustments to pricing, order quantities, or service methods may be necessary instead of immediately stopping sales.
7. Finance, insurance, and payment methods
Compare bank fees, loan amounts, service maintenance fees, and insurance policies to identify overlaps or inconsistencies. Compare coverage, deductibles, and remaining risks when changes occur, not just choosing the lowest premium. Mandatory obligations and essential protections should not be excluded from the decision.
Plan your cash inflows and outflows to reduce short-term borrowing resulting from a lack of coordination. When negotiating payment terms, consider discounts, fees, and the supplier's ability to provide the service. Extending payment terms only supports cash flow if the total amount payable remains unchanged; it's not automatically a savings.
Electronic payments, installment payments, or switching service accounts can reduce processing time, but you need to check transaction fees, limits, approvers, and information security. Don't switch to a new method just because it's advertised as cheaper.
8. Internal work, coordination, and spending discipline.
Replace in-person meetings with online meetings when objectives can be achieved remotely; keep trips for surveys, inspections, or in-person work. Plan early, consolidate schedules effectively, and compare total costs for changes/cancellations, travel, accommodation, and personnel time.
Internally, clearly disclose budgets, approval levels, and required documentation to avoid pre-purchases followed by subsequent legalization. Assign responsibility for expenditures to the users, not just the accountants. Mechanisms to encourage savings should be accompanied by quality standards, avoiding rewarding cost reductions while shifting workloads to other departments.
Review overlapping internal procedures, unclear delegation of authority, and requests outside of established processes. Businesses can only modify processes within their own jurisdiction; they cannot unilaterally abolish procedures or obligations mandated by government agencies. For instances of non-transparent spending, record evidence and handle it through authorized channels instead of incorporating it into operational practices.
Calculate net savings before approval.
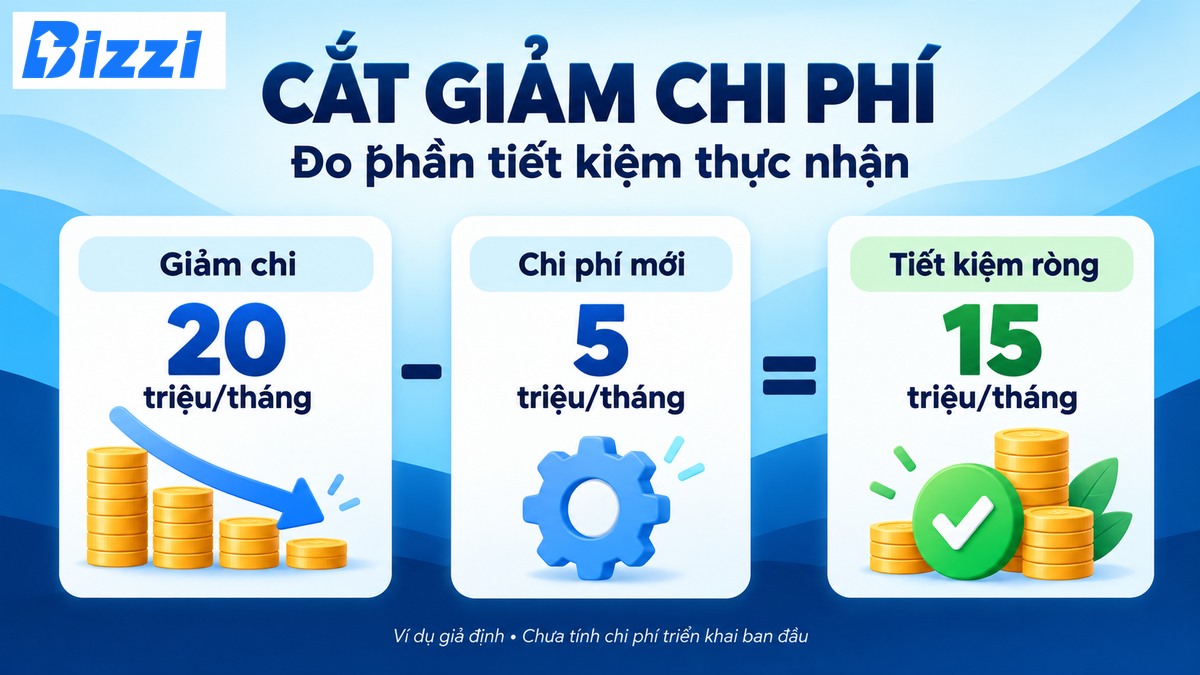
The net savings equal the actual cost reduction minus the new costs incurred to maintain the measure. One-time implementation costs need to be tracked separately to determine how long it takes for the savings to offset the initial investment. Agree on a similar timeframe, scope of operations, and tax treatment before making comparisons.
Hypothetical example: The business expects to reduce costs by 20 million VND per month, but will have to pay an additional 5 million VND per month for operating expenses and 30 million VND for initial implementation. The net savings when operating stably are: 20 - 5 = 15 million VND/month. If the benefits are immediate and remain constant, the payback period for the initial costs is 30 ÷ 15 = 2 months.
In the first month, including implementation costs, the improved cash flow is 15 - 30 = -15 million VND. If there is a trial period, termination fees for the old contract, or incremental benefits, the payback period will be different. This example uses hypothetical figures based on the same costs; it does not represent guaranteed savings or customer results.
With automation, record the number of freed hours and the amount saved separately. If staff still work full hours and there are no cost reductions, the benefit could be handling more work, reducing backlogs, or improving quality. This is still a value worth considering, but it shouldn't be recorded as actual savings.
Avoid calculating the same benefit twice, such as both calculating overtime reductions and allocating those hours as other personnel cost reductions. Accountants and operations managers should agree on the calculation method before submitting it for approval.
The process of implementing data to actual results.
A sufficiently clear process is needed to distinguish beneficial initiatives from budget cuts on paper. Each measure should have a responsible person, source data, and a timeframe for verification.
- Finalize the issue and initial figures. Identify the expenditure, volume of activity, causes, and potential impact. Review contracts, renewal schedules, and related obligations.
- Choose an option and calculate the total impact. Compare net savings, deployment costs, transition time, and risks to the customer, quality, and personnel. Specify which assumptions lack data.
- Delegate responsibility and grant approval. The user of the expenditure is responsible for implementation; the finance department checks the calculation method; and the authorized person approves the scope and budget for the conversion.
- Test within the appropriate range. Select a group of products, components, or suppliers that can be tracked. Prepare a plan for handling disruptions and criteria for stopping testing.
- Compare the actual results. Compare invoices, incurred costs, and service quality with the initial adjusted figures based on operations. Separate the actual savings from the projected savings.
- Conditional maintenance and expansion. Update quotas, approval schedules, responsible personnel, and reports periodically. Only expand when results and risks have been validated.
In the analysis of Maintaining cost-cutting results featured in ACCA's AB Magazine, The author emphasizes a clear roadmap, measurable results, and integrating change into daily operations. For businesses, this means transforming good practices into accountable practices, rather than ending when the initial target is met.
| Measure | Person in charge | Benefit Index | Limits must be maintained. |
|---|---|---|---|
| Reduce redundant software licenses. | IT and user departments | The actual fee is reduced after renewal. | Users can still access the data, and it is stored correctly. |
| Change the source of supplies. | Purchase and quality | Total expenditure per unit meets requirements. | Error rate, on-time delivery, and alternative sources. |
| Reduce repetitive data entry | Operations and Accounting | Processing time, number of repairs, and actual overtime costs are reduced. | Exception checking and data tracing |
| Adjust work schedule | Head of Department | Total expenditure for work objectives completed | Work quality and schedule changes |
To maintain results after implementation, regular reporting by item and department is necessary. A sample report can be used as a reference. cost management report when designing the tracking section.
Evaluate results without reducing competitiveness.
Reduced costs are only one aspect of the outcome. It's necessary to consider whether profits, cash flow, and service levels have improved across the board. When the market changes or output decreases, lower overall costs may stem from less business rather than improved operations.
- Expense: Does the savings appear on documents, contracts, or actual expenditures? Has it been transferred to another account or a later period?
- Quality: Are errors, returns, rework, complaints, and disruptions on the rise?
- Revenue and customers: Have the response rate, delivery time, and customer retention changed?
- Personnel: Does workload, overtime, and dependence on one person increase?
- Sustainability: Who will review the contract renewal, quotas, and actual usage after the project ends?
Good results can generate additional resources for investment or increase resilience to fluctuations, but they don't automatically guarantee increased profits. If a business reduces costs in one area but then increases warranty services, loses orders, or has to re-employ in another area, the overall impact needs to be reassessed.
When expenses are incurred before they are controlled.
If the problem lies in employees booking services before seeking approval, submitting disjointed documents, and accountants only discovering budget overruns during final settlement, businesses need to establish policies and appoint approvers before spending. Software can support the organization of the process; however, the responsibility for selecting which expenses to reduce remains with management and finance.

Link the proposed expenditure to the budget and approval. If your business requires centralized expense management and reporting, discuss with Bizzi the scope that best suits your specific processes.
Frequently Asked Questions When Cutting Business Costs
Should all departments be required to reduce their budgets by the same percentage?
A general ratio might be required in planning, but it's not enough to decide which items to cut. The tasks, volume, contracts, and risks of each department must be considered. Prioritize measures that yield clear net savings while maintaining service standards.
If revenue is declining, should marketing be stopped immediately?
It's necessary to examine which channels generate suitable customers and the contribution after service costs. Check the buying cycle, data reliability, and signed commitments. Ineffective parts can be reduced or the experiment adjusted instead of stopping entirely.
Is downsizing the quickest way to save money?
There is no general conclusion. The costs of change, remaining work, lost capacity, and potential disruption need to be considered. A review of assignments, processes, and actual needs is necessary beforehand; any changes involving employees must meet applicable obligations.
How long will it take to see results?
Depending on the method and the time the contract takes effect, the cancellation of excess services may be reflected from the next billing period; changes to processes or equipment require implementation time. It is advisable to establish verification milestones for each task and only record benefits that have been proven.
Do small businesses need to purchase software before they can reduce costs?
Not necessarily. You can start with expense data, contract lists, and a dedicated tracking sheet. When numerous requests, documents, and approvers work in a fragmented manner, evaluate the software by specific issues and overall cost of use.





