


View and download the PDF list of 1,520 businesses listed as invoice buyers in the copy of Official Letter 1328/ĐCSKT of 2024 in Tan Phu District, Ho Chi Minh City. The link and instructions for finding businesses by tax identification number are below.
View and download the PDF list of 1,520 businesses.
Open a list of 1,520 businesses on Google Drive.
The file is named DS-1520-cong-ty-dieu-tra-hoa-don_-Tan-Phu.pdf. After opening, select Download Use the Google Drive viewer if you want to save it to your computer. If the link doesn't open or access permissions have changed, check with the file sharer before using it.
This is a link to a copy shared on Google Drive; please verify the source and scope of the document before using it.
Do you have an Excel file containing a list of 1,520 businesses?
The link above is a PDF, not an Excel file. No Excel version has been matched to the PDF and is available here. If you receive an Excel file from another source, you should check the file name, row number, tax code, and corresponding PDF page number before using it to filter or merge data.
How to look up tax identification numbers in the list of 1,520 businesses.
Use the tax identification number as the primary identifier, then double-check the name and transaction information. Searching by name alone can easily lead to confusion with businesses that have similar names, abbreviations, or information that has changed.
- Open the PDF and find the tax identification number. Use the search function of your PDF viewer or press Ctrl+F and enter the full tax identification number you are looking for. If the scan lacks a text layer and yields no results, switch to viewing the image page or use OCR to assist in locating the position.
- Read the line above the original image again. Compare the tax identification number with the company name, not just relying on a single word in the name. With the OCR results, check each character to detect errors such as 0/O, 1/I, or reversed digits.
- Check full row and column headers. Read out the company name, address, invoice number, amount, and unit of measurement if applicable. Keep the number so you can return to the correct position in the original document.
- Compare with the supplier list and actual documents. Record which businesses have transactions with the entity under review, in which period, and which invoices are involved. Matching tax identification numbers is the starting point for comparison, not the final tax assessment result.
- Make a list of tasks that need verification. Separate the rows that match, have insufficient data, or contain discrepancies. Assign this to the responsible person, record the findings, and update the verification results.
In Excel, tax identification numbers should be saved as text to avoid losing the leading zero or being converted to scientific numerical format. When splitting a branch, keep the code string and separator as on the records, and cross-check the official information before merging the data.
For example, a scanned file might show a tax identification number ending in "108," while the internal catalog shows "180." The accountant needs to open the correct image page and double-check the code before flagging the supplier. It's not advisable to modify the code simply to match a similar name.
If you need to retrieve your tax identification number or verify registration information before cross-referencing the list, see How to look up individual and business tax identification numbers.. Looking up registration information is different from finding a code in the 2024 appendix.
Official document 1328/ĐCSKT and the scope of the list.
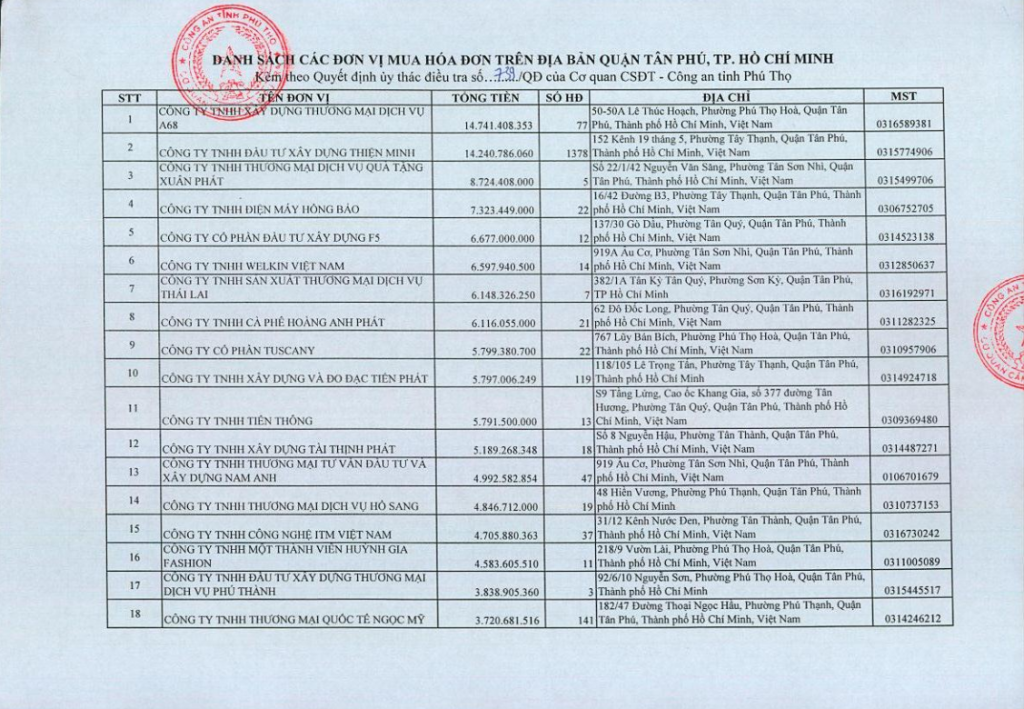
The circulated copy bears the number 1328/ĐCSKT, dated April 3, 2024, issued by the Criminal Investigation Department of Tan Phu District Police, and sent to the Tan Phu District Tax Office. The summary states the transfer of information regarding suspected tax and invoice violations. The content requests inspection, verification, and document collection to determine whether or not violations exist.
The Ho Chi Minh City Law Newspaper on April 15, 2024, also reported that the Tan Phu District Police transferred a list of 1,520 units and businesses to the tax authorities for inspection and verification. The article is archived on [website/platform name]. Youth. This is information regarding the 2024 review.
The scope and timeframe need to be maintained when reviewing the document. An old file reposted in 2026 does not become the new 2026 list. Similarly, a list of entities included for comparison does not equate to a list of businesses that have been found to be in violation.
If you need to compare the group often referred to as the “1,500 businesses,” check separately. Source and period of each aggregate file To avoid confusion with this list of 1,520.
| Information | Comparison method | What cannot yet be inferred |
|---|---|---|
| Document number and date | Check the official document page, the sending agency, the receiving agency, and any accompanying documents. | The file upload date is not the publication date. |
| The role of businesses | Read the table title, tax identification number, and the description of the buyer and seller. | The buyer appearing in the table is not automatically identified as the entity that established the company to sell the invoices. |
| Review phase | Compare the transaction time with the scope of the document. | The 2024 information does not confirm the current status of the entire business. |
| Information characteristics | Distinguish between information transfer, verification requests, and processing conclusions. | The signs to be checked do not replace the results of case-by-case verification. |
For PDF or Excel files sent via email, chat groups, or archive links, businesses should request the provider to confirm the source and version before using them as a basis for processing. If they cannot yet be compared with documents provided by competent authorities, the file should only be used to identify records requiring further verification.
What should I check when I find a tax identification number in the list?
Current tax registration information and transaction records answer two different questions. Lookups help identify taxpayers and their published status at the time of inspection; contracts, deliveries, invoices, and payments help reconcile specific transactions.
Instructions for looking up tax identification numbers on the Government Electronic Information Portal. This leads to the taxpayer information lookup system. Accountants should save the results along with the lookup date, cross-check the tax identification number and company name, and then check relevant notifications through official channels when clarification is needed.
| File group | Checkpoint | Results to be recorded |
|---|---|---|
| Contracts, quotations, purchase orders | The subject, goods or services, price, and terms of the transaction. | Based on the need to purchase. |
| Delivery, warehousing, and acceptance testing. | Quantity, timing, delivery person, and outcome. | Based on the actual goods or services received. |
| Electronic invoices and data | Seller, buyer, numbers and symbols, date, contents, money, and accompanying data. | Which invoices match the records and which do not?. |
| Payments and accounts receivable | Beneficiary, amount, date, details, and debt reconciliation. | Which transactions are the cash flows related to?. |
| Notification, explanation | The issuing authority, document number, scope, requirements, and deadline are stated in the document. | Tasks to be done, responsible person, and feedback criteria. |
This is a suggested record-keeping table, not a list of eligible deductions or deductible expenses for all cases. When processing tax obligations, businesses need to refer to the regulations applicable to the period, type of transaction, and specific notification.
Prioritize preserving records and clarifying transactions before drawing conclusions or making adjustments. The head of the accounting department needs to know the verified data, the parts that are still under review, and who is handling them.
- Keep invoices, electronic data, contracts, delivery and payment documents; also retain copies of documents used for review.
- Create a reconciliation table for each tax identification number and invoice, clearly stating the source of the warning and the actual discrepancies found.
- Contact the supplier to clarify information and gather any missing documents; record the details of the communication.
- Refer files requiring tax or legal assessment to a qualified professional, including the correct period and circumstances.
- Upon receiving a document from an authorized agency, carefully read the requirements, scope, and deadlines in order to organize a response.
A forwarding list does not replace the basis for automatically canceling invoices, deleting data, or adjusting the entire declared tax amount. If there is already a notification or conclusion regarding the transaction, the handling process must adhere to that content and the corresponding regulations.
Businesses should also limit who has access to review files and separate unverified information from approved conclusions. Clear documentation helps purchasing, accounting, and management communicate the same file status.
The invoice value is not the amount of tax involved. Comments on a 2024 case file cannot be used as a rule of exemption from liability for all cases below a certain monetary threshold. When a tax or legal assessment is required, the correct case file, subject, conduct, period, and applicable regulations must be examined.
Frequently Asked Questions when searching for a list of 1,520 businesses
Is this the latest list of shell companies in 2026?
Documents numbered and dated in 2024 should not be used as a new list for 2026. The issuing authority, version, and updated notification or processing results for the case being compared must be checked.
Is the mere appearance of a name on the list sufficient to conclude a violation?
That information needs to be read in the same way as the document and the record of each transaction. The review list, indicator information, and processing conclusions are different types of information.
Can Excel and PDF files be different?
There may be discrepancies due to re-entry, OCR, filtering, or editing. The original document should be retained, and the tax identification number, serial number, and column headers should be compared with the corresponding page before using the data.
If my name isn't on the list, can I skip the invoice verification step?
No. A file with its own scope and timing does not cover every vendor or every transaction. Businesses still need to verify documents according to their existing procedures.





