Employee training costs are the expenses a business incurs to help employees learn and apply the knowledge and skills necessary for their work. When budgeting, it is necessary to account for both external payments and internal resource time, and to clearly separate administrative costs, payments, and tax-deductible expenses.
A cheaper program isn't necessarily more effective. HR and accounting need to agree on what problem the program will solve, who will participate, the total resources required, and what evidence will be provided to demonstrate that the results have been achieved.
What are the costs involved in employee training?
Training budgets typically include tuition fees, instructors, learning materials, tools, travel, and internal resources allocated for learning. The scope of calculation should be clearly stated from the outset so that departments can compare on the same basis.
| Item group | For example | How to track |
|---|---|---|
| External purchases | Course fees, instructor fees, materials, venue, and learning platform accounts. | Compare quotations, service scope, invoices, and payment schedules; separate fixed costs from per-person charges. |
| Support for learners | Travel, accommodation, living expenses, or financial support as per the approved program. | It is linked to the learner, the time frame, and the applicable policies; it is not automatically included as tuition fees. |
| Internal resources | Employee training time; instructor preparation, teaching, and evaluation time. | It is possible to convert data for management analysis, but clearly state the unit price, number of hours, and avoid double billing. |
| Maintain and retrain | Updating documentation, workplace instructions, supplementary exams, retraining. | Please list separately the portion included in the service package and any additional costs that may arise after the course. |
Opportunity cost is the value of the option to be forgone when allocating resources to training. This is a decision-making perspective, not a sum of money that must be automatically added to the accounting books. If the time spent learning has already been converted into salary, do not continue to add the entire projected lost revenue without explaining which parts have not actually been reflected.
In the context of vocational training under Article 62 of the 2019 Labor Code, training costs have their own legal scope and require valid documentation. Internal L&D budgets may include management-related expenses, but this does not mean that every internal estimate becomes an amount that can be claimed from employees.
How to calculate the budget and training costs per employee.
Add up items within the same range, check for overlapping items, and select the correct denominator before calculating the average cost. It is necessary to distinguish between those who register, those who actually learn, and those who complete the course, especially when comparing the two forms of training.
Two management metrics can be used: Costs within the selected scope = external purchases + learner support + allocated internal resources; Average cost = cost per selected range / number of people in the measured group. Items already included in the package price or allocated to other items will only be charged once.
For example, estimating the cost of a course for 20 people.
Suppose a company organizes an internal program, registers 20 people, and 18 complete it. The numbers below are for illustrative purposes only, not representing market prices or tax rates.
| Illustrative item | How to calculate | Value |
|---|---|---|
| Hire external instructors. | Hypothetical package price | 12 million VND |
| Document | Total for the course | 2 million dong |
| Travel and support as planned. | General assumption | 4 million VND |
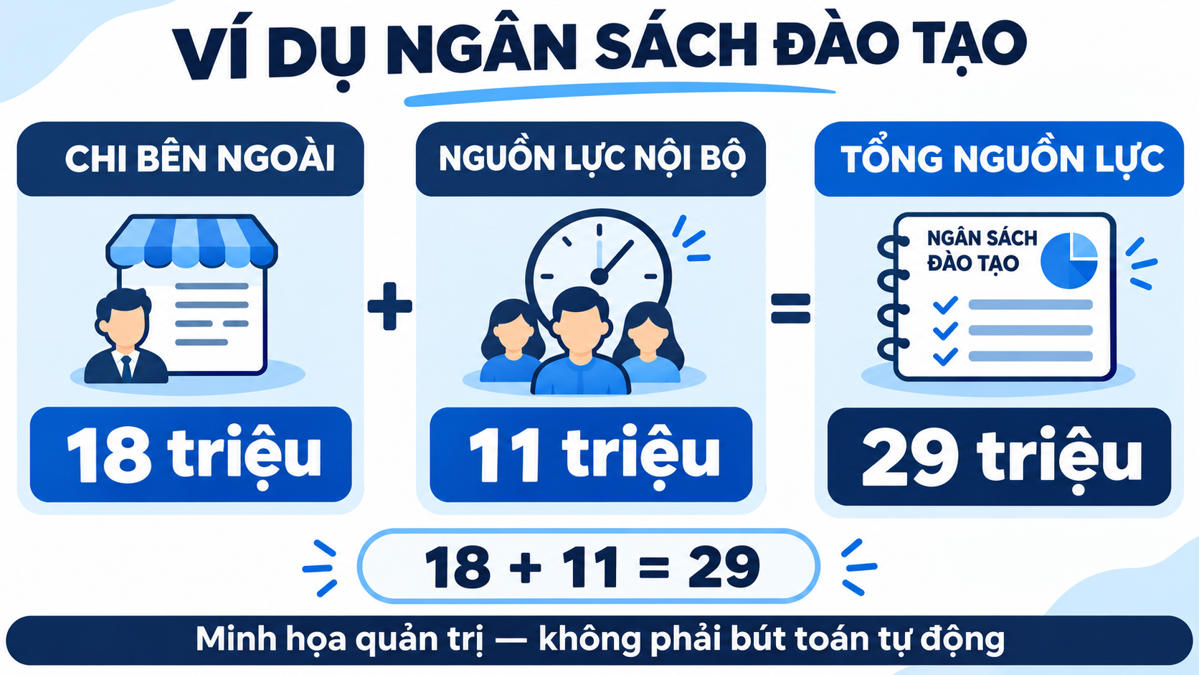
| Total external expenses | 12 + 2 + 4 | 18 million VND |
| Time converted by learners | 40 hours of public time combined × 200,000 VND/hour | 8 million VND |
| Internal preparation and support | 10 hours × 300,000 VND/hour | 3 million dong |
| Total resources by scope of management | 18 + 8 + 3 | 29 million VND |
According to the registration number, the cost is 29 / 20 = 1.45 million VND/person. Based on the number of completed items, the cost is 29 / 18 ≈ 1.61 million VND/person. If the initial budget of 30 million VND also includes internal resources on the same basis, the difference is less than 1 million VND, approximately 3.33%. Don't compare the 18 million VND in external expenses with the 30 million VND total budget and then conclude that 12 million VND was saved.
Factors that cause total costs to change
Class size affects each component differently: instructor fees may be fixed per session, while learning accounts and materials are charged per person. Duration, initial skill gap, practice requirements, location, and number of retakes can all alter the budget. Therefore, it's necessary to ask the provider what is included, how additional costs are approved, and whether absenteeism is permitted.
When reviewing multiple programs, they can be organized into training categories. business cost management process, Instead of just totaling tuition fees at the end of the month.
Six steps to cost control from proposal to post-training evaluation.
Each program needs a work objective, a person responsible for the budget, and a timeline for tracking results. HR is responsible for content and learners; the user department confirms the needs; finance and accounting check the feasibility of spending and documentation.
- Identify skill gaps. Record the work being struggled with, the learning needs of the team, and the expected outcome, such as reducing order entry errors. The output should be a specific need, rather than a suggestion to purchase a course because it's on sale.
- Compare options with the same output. In-house training, outsourced training, and blended learning should be considered side-by-side in terms of content, instruction time, practical support, and total resources. The outcome should be a rational choice.
- Prepare and approve the budget. Finalize outsourced purchases, labor hours, support, number of people, timeframe, and contingency. Determine the authority to approve changes. The output is a budget with defined scope and basis for calculation.
- Prepare the agreement and documents. Review service contracts, trainee lists, payment terms, and expected supporting documents; prepare vocational training contracts when required by law. The output is a complete set of documents before any expenditures are incurred.
- Record the facts and address the discrepancies. Track participants, sessions, committed funds, additional payments, and settlements; explain price increases, additions of students, or schedule changes. The output is a budget-to-actual reconciliation statement on the same basis.
- Review the application and make a further decision. After a suitable period of time on the job, management assesses where skills have been utilized, what is lacking, and whether further training is needed. The outcome is a decision to continue, adjust, or discontinue the program.
Businesses should determine in advance the required documents, reviewers, and payment methods. Internal spending rules. The regulations help standardize operations; however, the tax deduction for expenses must still be subject to separate verification according to applicable regulations.
How are training costs checked in terms of documentation and taxes?
Tax eligibility depends on the nature of the expenditure, supporting documents, payment method, and the period of application. Do not use the label "employee training" to simultaneously draw conclusions about corporate income tax, value-added tax, and personal income tax.
Corporate Income Tax: Checking the basis for expenditure and payment conditions.
Clause c, point 2, Article 9 of Decree 320/2025/ND-CP stipulates that expenditures for vocational education and training for employees include fees for instructors, materials, equipment, practical training materials, learner support, new recruitment training, retraining, and professional development. These activities must be detailed in one of the following documents: employment contract, collective labor agreement, or the enterprise's financial regulations.
It is also necessary to meet the conditions regarding invoices, documents, and payment as stipulated in Article 9, Point c, Clause 1, which specifies the conditions for non-cash payment documents for the purchase of goods, services, and other payments made in installments. 5 million VND Above that, with specific regulations for related cases. The default threshold of 20 million VND from the old guidelines for current expenditures will no longer be applied. The original text can be compared. Article 9 of Decree 320/2025/ND-CP when checking the records.
- The plan, decision, or approval specifies the objectives, learners, and budget.
- Labor records, agreements, or financial regulations should reflect training content as applicable.
- Service contracts, programs, participant lists, acceptance documents, or completion confirmations are consistent with the actual transaction.
- Invoices, supporting documents, and payment flows match the supplier, payer, and amount the business is liable for.
The above list is a way to organize documents for verification, not a guarantee that all expenses will be deductible if all four groups of documents are present. In cases where the employee pays in advance and the company reimburses, it's necessary to check the regulations and documentation from both sides, instead of just keeping a photo of the money transfer transaction.
VAT: input VAT is only considered for deduction if it is present.
Teaching and vocational training activities, as regulated by the law on education and vocational training, are exempt from Value Added Tax (VAT) according to Clause 13, Article 5 of the 2024 VAT Law; this point was reiterated by the tax authorities in the official guidance issued in 2026. When a valid invoice for a non-VAT-exempt service does not include VAT, the business does not have any input tax on that invoice to deduct.
Each service needs to be examined individually: a combined contract for training, implementation consulting, software leasing, or event organization should not be considered the same simply because the package name includes the word "training". If input VAT is involved, further examination of its deduction conditions is necessary; recognizing expenses and deducting VAT are two different matters.
Personal Income Tax: Separating tuition fees, financial aid, and salary.
Tuition fees paid by businesses to training institutions, direct support payments to employees, and salaries during training periods need to be categorized separately. Do not simply label all of these as tax-exempt for personal income tax just because the business has approved the program.
Personal Income Tax Law 109/2025/QH15 Effective from July 1, 2026; regulations related to salaries and wages for resident individuals apply from the 2026 tax year. When processing payments to students, accountants need to compare the nature of the expenditure and apply the correct guidance for the period, instead of using only the old regulations in Circular 111/2013/TT-BTC as the conclusion for all support payments in 2026.
How does recording training costs differ from paying tuition fees?
The date of money transfer does not automatically determine the entire timing of expense recognition. Accountants need to examine the progress of the service, the department using it, the accounting system applied by the company, and the nature of the upfront payment.
For example, paying upfront for a course that hasn't started is different from paying after the program is completed. A program serving multiple departments also needs a rational allocation method, rather than allocating all funds to the department that requested the service simply because that department submitted the payment request.
| Data | What purpose does it serve? | Points to avoid |
|---|---|---|
| Estimated cost and equivalent working hours | Compare the options and examine the resources available. | Record the salary again once it has already been included in personnel costs. |
| Invoices, service confirmations, accounts payable | Identify the actual transaction and the recognition period. | Only use the money transfer receipt to conclude that the service has been completed. |
| Down payment | Monitor your eligibility to receive services in the relevant periods if you meet the conditions. | Large sums of money are automatically allocated over three years. |
| Tax identification records | Check deductible amounts, input taxes, and related obligations. | Verify the amount recorded in accounting with the amount accepted for tax purposes. |
There is no basis for applying a three-year allocation period to all courses simply because of the high cost. The applicable accounting policies and procedures must be considered for each case. When selecting specific accounts, recording periods, and journal entries, refer to the guidelines. Accounting for employee training costs, Then compare it with the accounting system and records of the unit.
When should you consider reimbursing training costs?
It is necessary to consider the training circumstances, the signed agreement, the actual expenses with supporting documents, and the method of terminating the employment relationship. Do not automatically conclude that full compensation is due simply because an employee resigns, nor assume that all training commitments are terminated by law.
Article 62 of the 2019 Labor Code requires both parties to sign a vocational training contract when an employee receives advanced training, skill development, or retraining, either domestically or internationally, using funds provided by the employer, including funds sponsored by partners. The contract shall be made in two copies, with each party retaining one copy.
The main content includes the training occupation; location, time, and salary during the training period; commitment period for employment after training; costs and reimbursement responsibilities; and the responsibilities of each party. Clause 3 of Article 62 lists the costs with valid documentation, including salaries and insurance for trainees during their studies, as well as travel and living expenses while being sent for training abroad.
Clause 3 of Article 40 stipulates that employees who unilaterally terminate their employment contract illegally must reimburse training costs according to Article 62. For other cases or disputes regarding the agreement, a review of the records and specific applicable grounds is necessary. These conditions can be checked at [link/website]. Articles 40 and 62 of the 2019 Labor Code.
- Determine the basis: Is this vocational training under Article 62 or other guidance activities; what agreement was signed?
- Compare the amounts: Prepare a table of expenses incurred by the business and corresponding supporting documents; separate the estimated opportunity cost, the amount funded by other parties, and the amount paid by the employee.
- Check the conditions under which liability arises: Commitment period, performance period, reason for termination, and refund terms.
- Exchange and save results: Clarify the agreed-upon terms, identify any disputed points, and refer the matter to the legal representative for review when necessary.
Businesses should not take a compensation formula applied to a group of officials, civil servants, or employees and apply it automatically to all employees. An example of allocation by the number of months is only meaningful if that calculation is consistent with a valid agreement and applicable law; it does not automatically create the right to claim reimbursement.
Optimize costs while maintaining training results.
The priority should be to reduce non-essential services, not just the course purchase price. If learners lack time for practice or management doesn't support application, businesses may end up paying extra for retraining, even if the initial tuition was low.
- Internal training: It depends on the specific process and practical experience; however, preparation time, instructor quality, and up-to-date learning materials still need to be considered.
- Blended learning: Put foundational knowledge into self-study materials, dedicate in-person sessions to practice and feedback. Assess the student's self-learning ability and the time available for support.
- Experiment with a group: Measure job performance and then decide whether to expand, instead of buying a large package right away just because the price per person is low.
- Learning resources and peer guidance: Reusing stable content is acceptable, but someone should be responsible for the version to avoid re-teaching a changed process.
- Tools and AI support: It can help with finding documents, practicing, or creating questions; it requires someone to review the professional content, data access rights, and operating costs. The number of times a tool is used should not replace the assessment of competence.
Measure effectiveness by application, not just the number of participants.
Choose one or more metrics linked to the goal: completion rate, satisfactory practice, level of management-approved application, operational errors, or pre- and post-processing time. When comparing, keep the scope of work the same and consider other changes that might affect the results.
ROI should only be calculated when there is a basis for converting benefits into monetary terms and identifying the portion related to the program: ROI = (determined monetary benefit − cost of the same scope) / cost of the same scope × 100%. If the benefits cannot be measured, report the costs and applicable metrics separately, instead of assigning a profit margin to the learning activity.
Questions when planning and controlling training budgets
Is there a reasonable overall training cost per employee?
You can't choose a one-size-fits-all program based solely on the number of people. Determine the skills gap, output, methodology, and cost range; use quotes and labor hour assumptions to establish the program's cost structure.
Does in-house training cost anything if no tuition is paid?
No. The time spent by instructors, students, and in preparing materials and tools still utilizes resources. This can be measured in hours or converted for administrative purposes, while also avoiding double recording of salaries already accounted for by the accounting department.
Is buying an online learning platform definitely cheaper than outsourcing?
It's necessary to compare output, actual user count, time spent building learning materials, operation, and support. A low account fee doesn't necessarily mean lower overall resources if there are fewer users or retraining is required.
When multiple departments propose training expenditures, standardization is needed in terms of budget allocation, approval authority, and actual expenditure records. With Bizzi Expense, businesses can organize spending requests, approve and track budgets according to a streamlined process. This scope supports expenditure management; training content, competency assessments, and tax decisions remain under the purview of the relevant department.