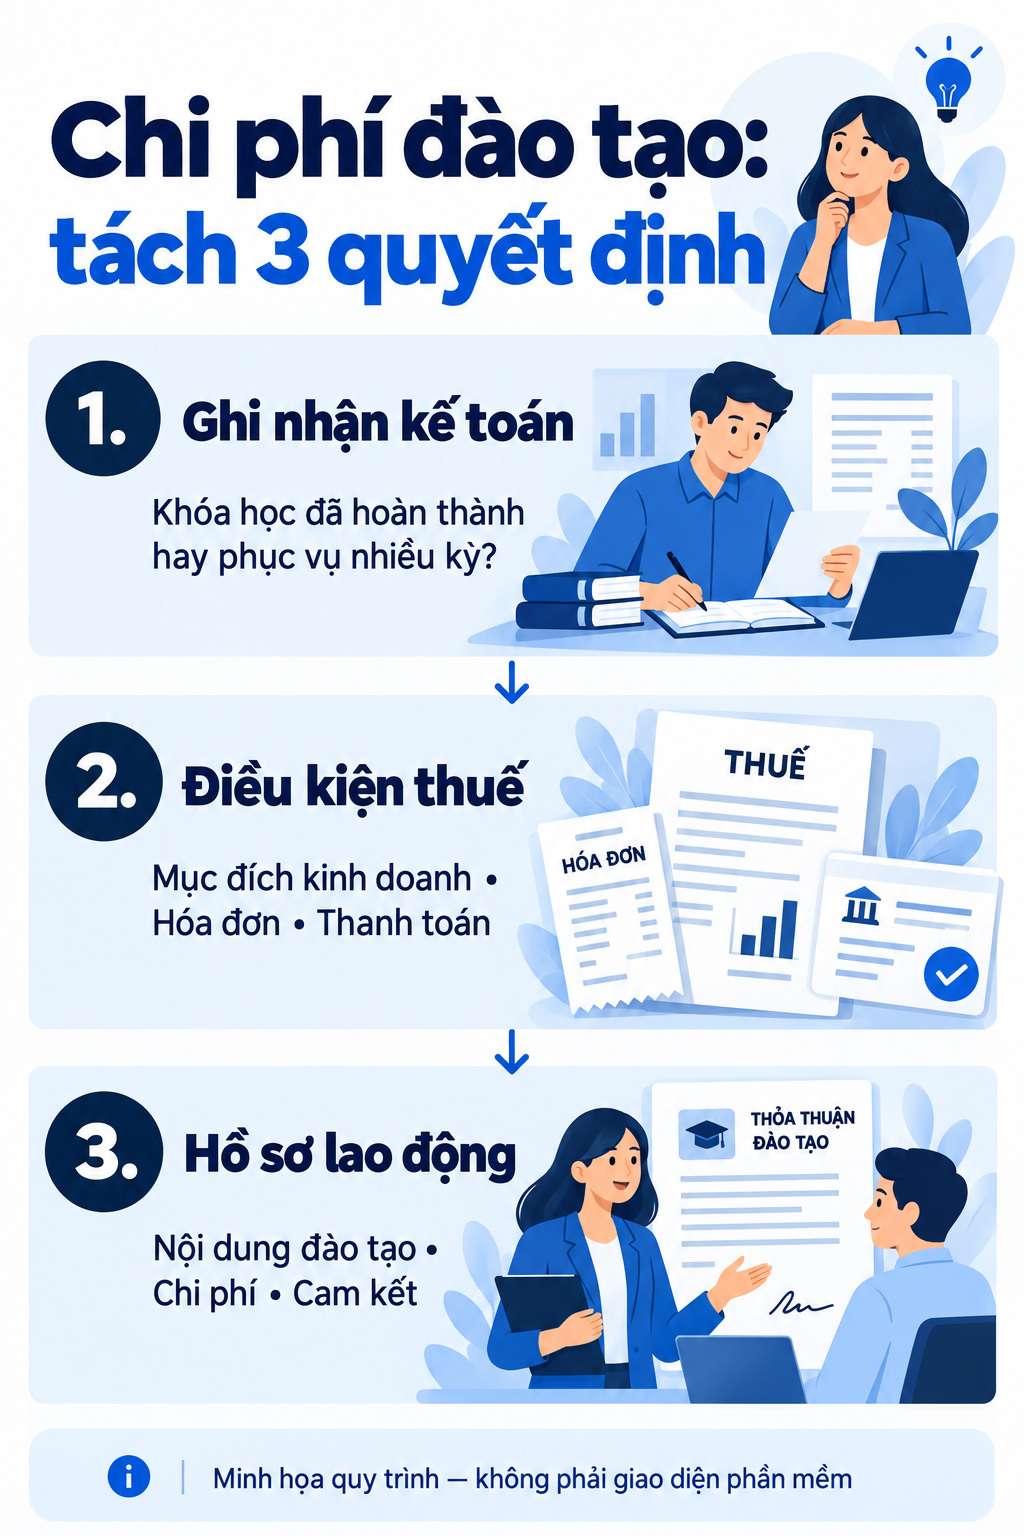
Where employee training costs are accounted for depends on the accounting system, the purpose of the expenditure, and the duration of the service provided. For management training completed during the period, businesses applying Circular 99 typically record it in account 642. A course should not be transferred to account 242 simply because of high tuition fees or knowledge that can be used for many years. After determining the accounting entry, the accountant must still separately check the tax records and reach an agreement with the employee.
Choose an account based on the nature of the expense, not the tuition fee.
Before recording an expense, three questions need to be answered: has the business received the training service, which department did the expense serve, and is there a basis for allocating it over multiple periods? A payment made is not necessarily an expense for the period; conversely, a completed service may need to be recorded even if the business has not yet paid.
| Situation | Way of looking at it | Points to check |
|---|---|---|
| The management training course has been completed. | Business management expenses, usually account 642 | Completion date, department used, invoice, and amount payable. |
| Training for sales or production | Review the expense accounts of the function/department under the currently applied accounting system. | Practical purposes and allocation criteria; not just looking at the student's job title. |
| Pay before the course starts. | Track upfront payments to suppliers as per contract; record when services are provided. | Distinguish between cash advances and incurred deferred expenses. |
| The actual expenditure relates to multiple periods. | Consider account 242 — Delayed expenses — if they meet the criteria for reasonableness and nature. | Scope of services, benefit period, allocated amount, and remaining amount. |
| Pre-operation training for newly established businesses, according to Circular 99. | Record production and business expenses during the period; instruct account 213 to debit account 642 and credit the relevant account. | Do not mechanically apply the method of grouping 242 and then allocating it over three years from the old guide. |
| Expenses that are not deductible when calculating corporate income tax. | Determine the accounting entry based on its nature, then adjust it during tax settlement. | Do not debit account 421 simply because the expense is disallowed for tax purposes. |
When is there a basis for using account 242?
Circular 99 stipulates that Account 242 reflects actual expenses incurred related to the production and business results of multiple periods. The allocation method and criteria must be appropriate to the nature of each expense item, and must be tracked in detail by period, allocated amount, and unallocated amount. Therefore, the documentation needs to explain which periods the expense serves and why that allocation method was chosen.
For example, a contract for providing continuing education over two fiscal years needs to be read according to the service content and implementation schedule. A class completed in a month but employees continuing to use the skills for two years does not automatically create the same allocation basis. Nor should account 242 be selected simply to lower monthly expenses.
For pre-operational cases, refer to account 213. Circular 99/2025/TT-BTC It has been clearly stated that training costs should be recorded as expenses for the period. The recording date in the books and the date of deduction for tax purposes may need to be compared separately; accounting conclusions should not be used to assert that the entire amount is deductible immediately in the same period.
What expenses need to be included in the training expense report?
Training costs may include tuition fees, instructor fees, materials, venue, equipment and practical materials, student support, wages, and insurance during the training period. If sending workers for training abroad, documentation may also include travel and living expenses. Each expense must be supported by appropriate documentation, an approving authority, and a link to the training program.
- Hire instructors or training providers: Keep records of course content, contracts, schedules, invoices/receipts, and proof of services rendered. When hiring foreign experts, review related tax obligations based on the contract type; do not use the complete documentation from a domestic provider.
- Materials and classrooms: Collect funds for course materials, printing, and hall rentals for each course. Expenses shared among multiple classes require clear internal allocation criteria.
- Machinery and equipment: Purchasing equipment for both training and production purposes does not mean recording the entire purchase price as tuition fees. Accountants evaluate the recognition of assets, tools and equipment, depreciation, or allocation separately according to their nature.
- Salary and insurance during the study period: Compare payroll records, attendance records, and student lists; do not record any additional expenses already included in the payroll.
- Travel, accommodation, and financial assistance: Link the decision to send someone for training to the trip, specifying the time and location; separate the work-related expenses from the personal expenses if the trip serves multiple purposes.
When budgeting, the time employees are away from home can be factored in to compare training options. This is an opportunity cost that supports management decisions and does not automatically become an accrual expense simply because it is included in the budget.
Example accounting entry: Course completed and employee receives advance payment.
The following examples are hypothetical scenarios for management, applying Circular 99. The amounts in the ledger must be taken from actual documents; VAT is only separated into account 133 when there is input tax that meets the conditions for deduction.
The 15 million VND course has been completed, and the company has transferred the payment.
The company sent a team of accountants for professional training. The service was completed within the month, with a payment of 15 million VND; assuming the training documents do not include any separately deductible VAT. The company has complete training records and will make payment from its corporate account.
| Major | In debt | Have | Amount |
|---|---|---|---|
| Record the service as completed but not yet paid for. | 642 | 331 | 15,000,000 VND |
| Pay the supplier by bank transfer. | 331 | 112 | 15,000,000 VND |
If recording and payment are done simultaneously, the entry can be Debit 642/Credit 112 according to the unit's accounting procedure. Do not record both methods for the same transaction. The tuition fee of 15 million VND is also no longer automatically payable in cash according to the old 20 million VND threshold.
Employees receive an advance of 10 million VND, with actual tuition fees of 8 million VND.
Assume the company transfers an advance payment to the employee to cover the approved course; the course is completed, the application is accepted, and no separate VAT is deductible. The accountant keeps full records of the disbursement and the amount the employee returns.
| Step | Illustrative journal entry | Amount |
|---|---|---|
| Advance payment | Debit 141/Credit 112 | 10,000,000 VND |
| Settlement of legitimate tuition fees already paid | Debit 642 / Credit 141 | 8,000,000 VND |
| The staff refunded the excess money via bank transfer. | Debit 112/Credit 141 | 2,000,000 VND |
After settlement, this advance payment has a remaining balance: 10 million VND, which includes 8 million VND spent and 2 million VND refunded. If the employee pays upfront and the company reimburses them later, track the employee's payables according to the unit's procedures; do not credit account 141 if there has never been an advance payment. The documentation must prove the correct disbursement, the correct supplier, the correct program, and the correct flow of funds.
VAT is not deductible or the expense is disallowed for tax purposes.
Do not add a debit to account 133 at an assumed rate when tuition invoices do not include VAT. For invoices with VAT, separately check the deduction conditions, the purpose of the service, and the payment documents; the non-deductible tax portion is handled according to the nature of the expense or related asset.
If an actual expense has been correctly recorded in the accounting but lacks the conditions for being deductible for corporate income tax, the accountant should monitor it for adjustment during tax settlement. Account 421 reflects undistributed after-tax profits; the lack of invoices or incorrect payment conditions are not automatically considered reasons for debiting account 421 and crediting it. In cases of accounting errors from previous periods or transactions with owners, these must be analyzed separately and not included in situations resulting in tax disallowance.
What tax documents are needed for the year 2026 before finalizing the tax return?
Businesses need to verify the authenticity of the expenditure, invoices/documents, and payment terms. According to Decree 320/2025/ND-CP, the requirement for non-cash payment documentation for purchases of goods and services and other payments of 5 million VND or more per transaction applies from December 15, 2025. The 20 million VND threshold will not be used to consider new payments in 2026.
Vocational training application dossier according to Circular 20/2026
Clause 3, Article 3 of Circular 20/2026/TT-BTC stipulates the documentation for vocational education and training expenses for employees. In addition to the corresponding invoices and payment documents, the following groups must be checked:
- Based on the expenditure records in the internal file: The employment contract, collective bargaining agreement, or financial regulations include provisions regarding expenses for vocational education and training.
- Approve participants: The decision of the competent authority approving the list of employees to be sent for training.
- Register for the course: A copy of the employee's training registration record.
- Participation results: Diploma or certificate; if none, a confirmation letter from the training organization or a list of employees who have participated.
The decision to send someone for training does not replace all other documents. For internal training courses, it is necessary to retain the organizational basis, attendance list, content, and actual expenditure documents consistent with the training format. Using a course code to link documents will help accountants check for missing records before closing the books.
Paying staff: check both the payment and the refund.
Circular 20 mentions cases where labor records or financial regulations allow employees to pay for training using cashless payment services, and then the company reimburses them using cashless payment services. Therefore, a company's refund statement alone is not sufficient to prove the employee's payment to the training provider.
In the example of a tuition fee of 8 million VND, you should keep records of internal approval/authorization, valid invoices or documents, employee payment statements to the training provider, settlement request, and proof of company reimbursement if necessary. Do not split the expense into smaller amounts to circumvent payment conditions. See more on how to check. non-cash payment voucher when comparing records.
Are tuition fees paid by the company included in an employee's income?
According to point i, clause 4, Article 8 of Decree 253/2026/ND-CP, the amount paid by the employer on behalf of the employee for training to improve their skills and qualifications relevant to their professional work or according to the employer's plan is not included in taxable personal income. The Decree takes effect from July 1, 2026; previous records need to be compared with the corresponding regulations.
Therefore, conclusions cannot be drawn solely from the course name. English for customer service may differ from a purely academic program based on personal preference. The purpose, job position, and company plan need to be clarified. If the above conditions are not met, the payroll department must assess how to handle the tax based on the nature of the benefit; not arbitrarily classify everything as exempt.
Training contracts and reimbursement agreements should be separate from service purchase documents.
The contract with the training center specifies the services the company purchases. The training contract between the company and the employee defines the responsibilities of both parties. These two documents serve different purposes; a supplier contract should not be used as a substitute for an agreement with the employee.
Article 62 of the 2019 Labor Code stipulates that both parties sign a vocational training contract when an employee receives advanced training, skill enhancement, or retraining domestically or abroad at the employer's expense, including funding from partners. The contract is drawn up in two copies, with each party retaining one; there is no provision stating "only when tuition fees are substantial" in this regulation.
- Training occupation; location, duration, and salary during the training period.
- Commitment period for employment after training.
- Training costs and reimbursement responsibilities.
- The responsibilities of the company and the responsibilities of the employee.
The costs for claiming reimbursement must be supported by valid documentation and agreement. Employees who leave the company are not automatically obligated to pay every amount the company allocates to its budget. In case of disputes, the contract, reason for termination, obligations of each party, and relevant labor regulations should be examined before determining the amount to be recovered or processing the severance pay.
Training new hires, apprenticeships/training for on-the-job training, and retraining existing employees can have different employment profiles. The HR department should determine the correct format from the outset, rather than waiting until the accounting department receives an invoice to add a general commitment form.
Handling cases that are prone to errors in recording.
| Case | How to check | Mistakes to avoid |
|---|---|---|
| Pre-operation training | Compare accounting methods, fiscal year, and specific tax deduction periods. | By default, 242/three-year allocation is given to all businesses in 2026. |
| Training for new or existing employees. | Proof of service work, academic program, approvals, and participation results. | Consider new recruits as eligible, or consider all expenses as belonging to account 642. |
| Training abroad | Separate tuition fees, airfare, and accommodation; check foreign documents, foreign currency, and related tax obligations. | Debit account 133 simply because the foreign document contains an item labeled "tax".“ |
| Individual learning without a work/plan basis. | Determine the nature of the benefit and documentation; consider separate corporate income tax/personal income tax. | Type the tax and record it directly in account 421. |
| Course cancellation or staff non-participation | Compare refund terms, cancellation fees, and outstanding balances; update approval records. | The cost remains the same as when the course was completed. |
If the missing documents can be supplemented, it must be clearly stated which documents are pending and who is responsible. Amounts that do not actually serve the operation or do not meet tax requirements must be assessed on their nature; they cannot be legitimized by a later decision containing inaccurate information about the transaction.
Develop a training budget and control expenditures from the proposal stage.
A useful budget should show what the expenses are for, who is being trained, and how the expected results will be measured. Simply compiling tuition fees after they arise makes it difficult for businesses to control duplicate classes, unplanned expenses, and incomplete documentation.
- Identifying needs: Address job and competency gaps, such as reducing operational errors or meeting new process requirements; prioritize needs requiring evidence.
- Set the results to be verifiable: Choose the number of participants, the required competencies, the deadline, and the evaluators. Don't just write "improve quality.".
- Compare the options: Internal training, hiring experts, external classes, or online/blended learning; comparison of content, practice, support, and job relevance.
- Schedule: Consider the learning time and how to maintain your work, and avoid booking classes simply because the provider is offering a discount.
- Prepare a comprehensive budget: Tuition fees, materials, travel/accommodation, support, and anticipated expenses. Separate opportunity costs from the amount to be paid.
- Document approval and preparation: Determine the budget, approver, payer, and documents to be delivered after the course.
- Compare actual expenses and results: Review discrepancies in budget estimates, missing documents, participation rates, and applicability to the work before the next phase.
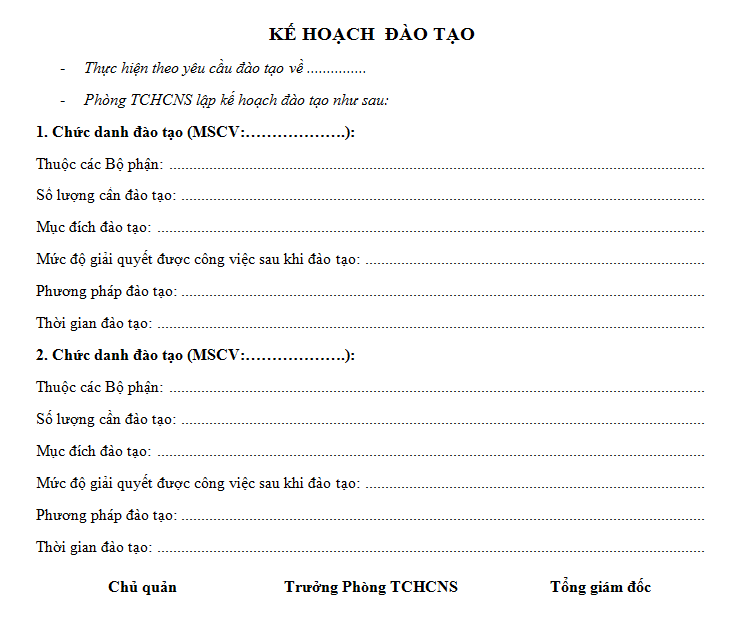
Cost savings can be achieved by using in-house experts for relevant content, combining online learning with hands-on practice, and negotiating group class sessions. However, it's important to compare total costs with learning outcomes, rather than simply choosing the lowest tuition. Cheap training that requires retraining or is inapplicable can increase overall costs. When choosing a learning format and building a budget, consider additional options. Types of employee training costs and how to optimize them..
When it is necessary to link training budgets to general control activities, refer to business cost control process. This article focuses on training expenses; other types of expenses require separate documentation and classification.
When should Bizzi be used for training expenditure processes?
If employees submit multiple requests for training, advances, and settlements through different channels, the primary need is to centralize the expenditure purpose, approval, and documentation. Bizzi Expense The process for proposing expenses, recording expenditures, attaching supporting documents, and submitting reports for approval is introduced. Businesses can discuss how to apply this to departmental training budgets and existing processes.
Accountants still need to evaluate accounts, documents, tax conditions, and labor records. An approved request on the software does not automatically prove deductible expenses; appropriate functionality needs to be confirmed according to the company's implementation plan.
Focus on training expense proposals and supporting documents.
We spoke with Bizzi about the process of creating, approving, and reporting expenses that best suits how businesses organize their budgets and settlements.
Frequently asked questions
Is it mandatory to allocate large tuition fees through account 242?
No. It must have a nature related to multiple periods and an allocation criterion consistent with accounting regulations. Large values or a desire to reduce profit volatility do not automatically create the conditions for using account 242.
What are the risks if the company pays 15 million VND in tuition fees in cash in 2026?
This amount exceeds the 5 million VND threshold for non-cash payment documentation requirements under Decree 320. Having an invoice and a decision to send the individual to study is not sufficient to waive the payment requirement; the specific situation needs to be assessed before final settlement.
Will not receiving a certificate after the course void my application requirements?
Circular 20 allows for a confirmation letter from the training organization or a list of participating workers even without a diploma or certificate. Appropriate evidence must be kept; do not create your own certificate or consider a registration email as proof of participation.
Is learning English always subject to personal income tax?
It's impossible to draw conclusions based solely on the course title. It's necessary to examine whether the payment made by the company is appropriate for the employee's professional work, duties, or aligns with the employer's plans and applicable regulations at the time the payment was made.
If an employee resigns before the agreed-upon timeframe, are they required to repay the full tuition fee?
It is necessary to review the training contract, documented expenses, reimbursement responsibilities, and circumstances surrounding the termination of the employment relationship. Do not assume that all termination cases result in the same obligations or that the entire salary will be automatically deducted.
Before closing the books: Compare the curriculum, accounts, and recording periods; check tax records and the flow of funds; and verify settled advances. Keep separate any missing funds for proper processing, instead of using a single entry for all training expenses.