


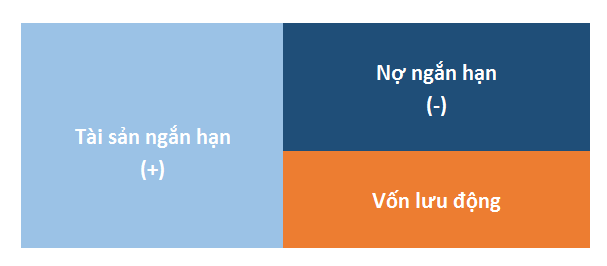
Working capital is a resource associated with short-term business operations, such as cash, accounts receivable, and inventory. When assessing financial performance, the indicator that is usually calculated is: Net working capital = current assets - current liabilities. A positive number indicates that current assets are greater than current liabilities at a given time; it does not mean the business has that much money available to pay them.
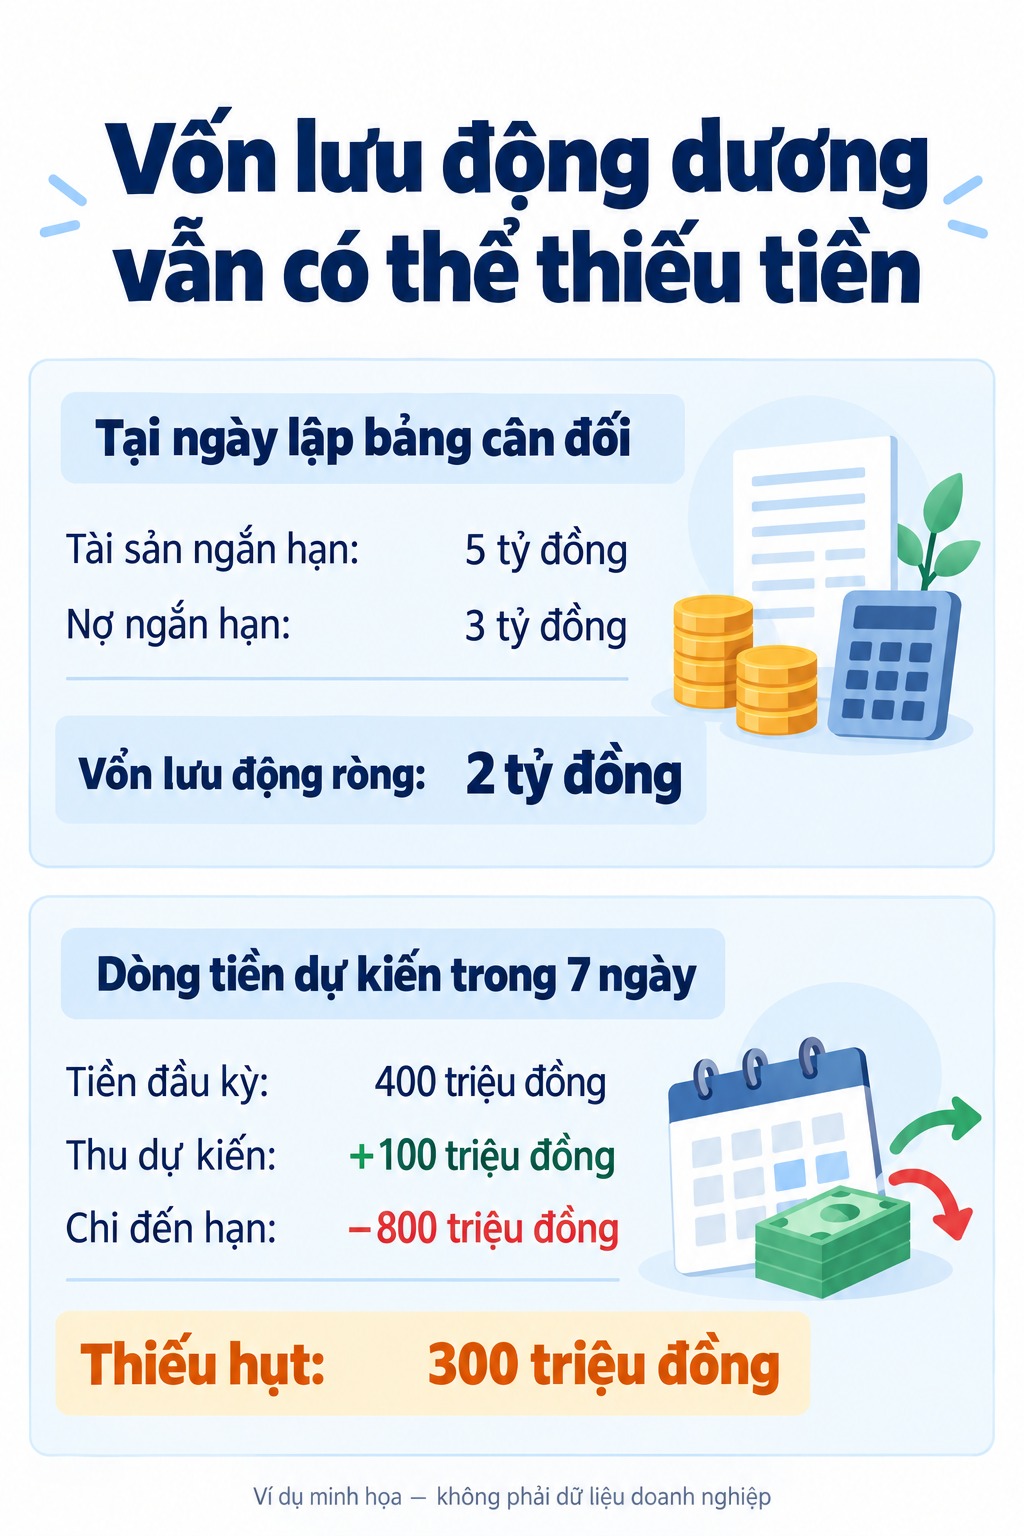
To determine if a business is short of cash, two tests are needed: Calculate net working capital on the balance sheet and schedule receipts and payments by due date. A business with net working capital of 2 billion VND may still be short 300 million VND next week if cash is tied up in inventory or uncollectible accounts receivable.
What does working capital consist of, and how does it differ from net working capital?
In business management, working capital is typically referred to as assets used in the purchasing, production, sales, and cash collection cycles. In financial statement analysis, it's crucial to clearly state the assets being used. total current assets good net working capital, because these two numbers answer two different questions.
| Target | How to determine | Things to avoid |
|---|---|---|
| Current assets | The total of items classified as short-term on the financial statements includes: cash, short-term investments, accounts receivable, inventory, and other short-term assets. | Don't assume everything can be converted into cash immediately. |
| Net working capital | Current assets minus current liabilities. | This cannot be used in place of remaining cash balances or loan limits that can be withdrawn. |
| Money can be used to pay off debts. | The actual amount of money used is added to the guaranteed income before the payment due date, after accounting for necessary expenses. | Do not include funds with usage restrictions or receivables that may not be collected on time. |
Current assets Both value and quality need to be considered. Limited-use deposits are not the same as readily available cash. Accounts receivable due but under dispute are not the same as amounts confirmed by customers. Slow-moving inventory may not generate cash even though it remains on the balance sheet. Prepaid expenses are for operational purposes but are often unusable to pay suppliers.
Short-term debt This includes accounts payable to suppliers, short-term loans, long-term debt due, and other short-term obligations as classified in the report. When calculating the indicator, use the figures presented in the same report; when planning payments, separate each item by due date. Supplier credit also has trade-off costs, such as loss of payment discounts or impact on purchasing relationships if payments are delayed beyond the agreed terms.
How to calculate net working capital from the balance sheet.
Formula: Net working capital = Current assets - Current liabilities. The result is in currency, not a percentage. To avoid getting the correct formula but incorrect data, follow these steps in order.
- Select the same business, time period, and reporting scope. Do not subtract the current assets of the consolidated report from the current liabilities of the separate report, or combine the quarterly and annual end-of-year figures. Check the unit of measurement (VND, thousand VND, or million VND) before calculating.
- Take total current assets and total current liabilities. Use the classifications in the company's financial statements and compare them with the explanatory notes when an item is unclear. Do not arbitrarily apply a single item code to all report templates.
- Perform the subtraction and record the data source. If using the net value already presented in the report, no further provisions should be deducted. Short-term debt already included in short-term debt should also not be deducted a second time.
- Compare the figures from the previous period and the reasons for the change. Separate the effects of cash, accounts receivable, inventory, and accounts payable. An increase in balance due to unpaid customers is different from an increase due to collected cash.
- Check the property's quality and repayment schedule. The calculation is just the starting point. Add in the age of the debt, the age of the inventory, and the projected cash flow to understand which items truly support the payment.
Example: Current assets of 5 billion VND, current liabilities of 3 billion VND
Assume that on the same reporting date, the business has current assets of 5 billion VND and current liabilities of 3 billion VND. Net working capital equals... 5 − 3 = 2 billion VND. It can be concluded that current assets exceed current liabilities by 2 billion VND on that report. However, it cannot be concluded that the company has 2 billion VND in idle cash, as current assets also include accounts receivable, inventory, and other items.
What does positive, negative, or increasing working capital indicate?
The net working capital indicator helps identify the financing structure, but it is not sufficient to assess liquidity health. The business model and the ability to convert assets into cash within a timely manner need to be examined.
| Situation | Original meaning | Check again |
|---|---|---|
| Positive | Current assets exceed current liabilities. | Are accounts receivable being collected on time? Is inventory being sold before the accounts receivable become due? Are there any restrictions on the use of cash? |
| Minus | Short-term liabilities exceed short-term assets. | Does the business collect payment upfront and receive payment later from suppliers, or does it have to borrow short-term to cover prolonged shortfalls? Is there a realistic source of funds to pay when the debt becomes due? |
| Increase | The difference between current assets and liabilities is greater than in the previous period. | Is the increase due to cash receipts, business expansion, or overdue debts and slow-moving inventory? Are we holding more capital than we need? |
Some cash-on-delivery retail models with fast inventory turnover and deferred supplier payments can operate with negative net working capital. That doesn't make every negative number safe: if sales decline or suppliers shorten terms, the timing advantage can be lost. Conversely, a large positive balance containing uncollectible liabilities isn't necessarily better than a small positive balance with assets that convert quickly into cash.
When assessing trends, comparisons should be made within the same season, reporting scope, and among businesses with similar models. A single working capital level or solvency ratio should not be used as a benchmark for all industries.
Identifying cash shortfalls: Don't just look at net working capital.
The need for funding is determined from the cash flow schedule, not by using the net working capital as the loan limit. Prepare weekly or daily forecasts if payment obligations are concentrated. The largest shortfall during the period, plus a justified provision, will serve as the basis for considering sources of compensation.
For example, net working capital is positive at 2 billion VND, but next week there will be a shortfall of 300 million VND.
Let's keep the example of 5 billion VND in current assets and 3 billion VND in current liabilities. Suppose that in the next 7 days, the business has 400 million VND in opening cash that is actually available, expects to receive 100 million VND, and has to pay 800 million VND on time. The expected closing cash is... 400 + 100 − 800 = −300 million VND. The company needs to collect payments sooner, adjust its payment schedule through agreements, or arrange appropriate financing; it cannot repay debt using only the 2 billion VND net working capital shown on paper.
The 300 million VND figure in the example represents the shortfall before the provision, not the recommended borrowing limit. If a 100 million VND collection is delayed, the shortfall will become 400 million VND. If a payment is legitimately postponed, the shortfall may decrease. Therefore, forecasts should include both a base case and a delayed collection scenario, with someone responsible for updating each item.
- The opening balance is available for use. Reconcile bank accounts and any funds that are frozen or set aside for other obligations.
- Arrange payments according to the expected date of receipt. Use payment deadlines, customer confirmation, and payment history; do not take all recorded revenue as cash receipts.
- Organize expenses by due date. Include goods, wages, taxes, rent, interest and principal on loans, and other necessary expenses; avoid omitting any lump-sum payments.
- Calculate the final balance for each time period. Transfer the previous period's ending balance to the next period's beginning balance. Mark the point at which the balance is negative or falls below the provision level.
- Choose a solution before you run out of money. Assign debt collectors, negotiate repayment schedules, or work with lenders; update forecasts after the plan is confirmed.
To delve deeper into how to read actual cash flow and differentiate between profit and cash inflows and outflows, see the guide. corporate cash flow analysis.
7 ways to manage working capital based on the reasons for holding cash.
Prioritize creating shortages, rather than simultaneously reducing accounts receivable, inventory, and expenses. Each measure needs someone in charge, data to monitor, and limits so as not to disrupt revenue or the supply chain.
1. Debt recovery based on debt aging and actual bottlenecks.
Create a list of upcoming, overdue, and disputed debts; assign a person in charge of each customer. Verify acceptance, reconciliation, and documentation before simply sending reminders. For new orders, adjust credit limits and payment terms based on risk. Early payment discounts should only be applied when the discount cost is reasonable compared to the benefit of collecting the money; do not automatically apply discounts to all debts.
2. Reduce slow-moving inventory while maintaining essential service levels.
Group inventory by sales rate, age, and risk of obsolescence; dispose of unwanted inventory using an approved plan. Adjust order points, lot sizes, and contingency levels based on actual delivery times. Just-in-Time (JIT) or Estimated Quantity (EOQ) is only useful when assuming appropriate demand, costs, and supply; excessively deep inventory cuts can lead to shortages, lost revenue, or the need for urgent purchases at higher prices.
When adjustments are needed to coordinate supply, production, and delivery, a comparison can be made. supply chain models with stable demand and response times.
3. Negotiate payment as agreed, don't turn delayed payments into a strategy.
Compare payment schedules with collection schedules, propose a suitable deadline before the obligation becomes due, and record the agreed-upon conditions. Compare the benefits of holding cash against lost discounts, penalties, and the risk of supplier cancellations. Prioritize maintaining commitments to essential supplies. Extending payment terms only improves the balance temporarily if it results in material shortages or loss of credibility.
4. Shorten the time from delivery to invoicing and payment collection.
Check the delays between delivery, acceptance, invoicing, reconciliation, and payment processing. A slow internal process can delay payment collection even if the customer is not intentionally late. Track the number of days at each step, handle erroneous records, and assign a point of contact for dispute resolution. Do not increase sales with excessive credit without assessing the likelihood of recovery.
5. Maintain a revenue and expenditure forecast with ongoing updates.
Include forecasts in a regular work schedule, compare projected figures with actual figures, and explain any discrepancies. Businesses can choose a multi-week forecast window, updating it progressively based on volatility; they need to look far ahead to make necessary arrangements, but avoid assigning the same level of certainty to near and distant weeks. Separate confirmed amounts from estimates, avoiding doubling the same revenue.
6. Monitor the cash cycle to identify areas that need improvement.
Simultaneously review inventory days, collection days, and payment days. If the cycle is prolonged due to inventory, increasing customer debt reminders doesn't address the root cause. If accounts receivable increase due to slow acceptance, that process needs to be revised. Evaluate each change based on trends in the number of days and quality of service, not just the end-of-month balance.
7. Match funding sources with time gaps.
Seasonal shortages require funding with a fixed term, disbursement conditions, and repayment schedules that align with collection times. The portion of ongoing needs should be addressed with more stable funding sources, rather than constantly shifting short-term loans. Considering interest, fees, and associated obligations, when a business cannot generate enough cash to repay its debts, borrowing more is not necessarily the root cause. Reference to relevant guidelines is possible. interest expense before comparing the costs of the options.
Read working capital ratios without confusing ratios with days.
The index helps compare efficiency and solvency, but it must be used for the same period, with the same calculation method, and the denominator must be explained. These supplement the income and expenditure schedule, not replace the cash forecast.
| Index | Recipe | Reading limits |
|---|---|---|
| Current ratio | Current assets / Current liabilities | A balance above 1 does not guarantee that all payments will be made on time. The quality of assets and industry practices need to be considered. |
| Quick Ratio | (Cash + Liquid short-term investments + Accounts receivable) / Short-term liabilities | Accounts receivable still carry the risk of being delayed or not collected. Inventory and prepaid expenses should not be considered quick payments. |
| Net working capital turnover | Average revenue / net working capital | A denominator of zero is uncalculated; negative or near-zero results are difficult to use for ranking effectiveness. Compare using the same definition. |
| Cash conversion cycle | Inventory days + Accounts receivable days - Accounts payable days | Use data from the same period and a consistent number of days. This is the number of days, not the amount of money to be borrowed. |
With an example of 5 billion VND in current assets and 3 billion VND in current liabilities, the current ratio is approximately... 1.67 times. Net working capital remains 2 billion VND. The two results originate from two different sets of data but have different units and meanings. It's impossible to conclude from a figure of 1.67 that the business is definitely not short of money.
When calculating the index by the number of days, use the average balance appropriate to the season. The number of days of inventory is usually related to the cost of goods sold; the number of days of accounts receivable should be consistent with credit sales and the scope of receivables; the number of days of accounts payable should use the corresponding credit purchases. Using the cost of goods sold instead of credit purchases is an approximation that needs to be clearly stated, especially when inventory fluctuates significantly. The convention of 365 days, 360 days, or the actual number of days in the period must be kept consistent. Guidance How to calculate DPO and read the number of days due. The limits of the denominator and the method of comparison are presented separately.
Frequently Asked Questions about Calculating and Managing Working Capital
Is net working capital the same as equity capital?
No. Equity reflects the remaining interest after subtracting all liabilities from all assets. Net working capital is simply short-term assets minus short-term liabilities. If properly and consistently categorized, net working capital could also be measured as long-term capital minus long-term assets; these are not two new amounts added together.
How much working capital is needed?
There is no single set of funds. Sales, inventory, collection deadlines, payment deadlines, and expenses incurred during the cycle need to be forecasted, and then the timing of potential shortfalls and appropriate provisions must be determined. Increased credit sales or peak seasons may lead to increased financing needs before funds become available.
Does negative net working capital mean bankruptcy?
It's impossible to draw conclusions based solely on this metric. Cash flow, due obligations, the current payment model (collecting now, paying later), and the actual availability of funding must be examined. However, persistent negative figures, coupled with overdue payments or repeated cash shortages, are signals that need attention and should not be ignored.
Is an increase in net working capital always a good thing?
No. Increase due to cash receipts is different from increase due to unsold goods or overdue debts. Each item and its utilization efficiency should be analyzed, rather than setting a target for the highest possible balance.
Next steps: Choose a reporting date to calculate net working capital, then create a cash flow schedule for the coming weeks. If there is a cash deficit, identify the cause in accounts receivable, inventory, payment schedules, or funding sources before choosing a solution. The examples and indicators in this article are for management analysis purposes only and do not replace comparing financial statements with the actual conditions of the business.
Source of method: ACCA — Working capital management; CFA Institute — Financial Ratio List. The data scenarios are illustrative examples constructed for this article.





