


Planning your expenses involves determining what you will spend money on, how much, when, and who will be responsible for it during a given period. For businesses, the plan should include approved budget limits and a schedule of income and expenses. This allows for the evaluation of both the purpose of the expenditure and the ability to repay it.
To begin, choose a month or quarter, gather committed obligations, estimate new expenses, and then compare that to available funds. A spreadsheet clearly outlining assumptions and the person in charge is often more helpful than a general budget figure without a schedule.
How do spending plans, budgets, and cash flow forecasts differ?
A spending plan describes needs and a spending schedule; a budget establishes the amount allocated; and a cash flow forecast checks the availability of funds on the payment due date. These three parts are interconnected but not interchangeable.
| Tools | The question needs to be answered. | Information needed |
|---|---|---|
| Spending plan | What needs to be bought or done, when, and why? | Expenditure details, quantity, estimated unit price, deadline, and responsible department. |
| Budget approved | How much is allocated and who has the authority to decide? | Limits are set by period, department, or project; approval authority and transfer conditions. |
| Cash flow forecast | Do you have enough money by the payment deadline? | Initial deposit, collection schedule, payment schedule, and maintenance level required. |
For example, a business approves a budget for equipment purchases during the quarter, but the supplier requires a deposit in the first month. The purchase may still be within the budget limit, while available funds may not be sufficient to cover the deposit. Conversely, having money in the bank account does not necessarily mean a spending request has been approved.
Sales revenue from credit sales may not necessarily be collected in cash during the period. Additional equity capital and borrowed funds increase available cash but are not considered sales revenue. When designing an overall budget for each department, further comparison can be made. Business budgeting and allocation.
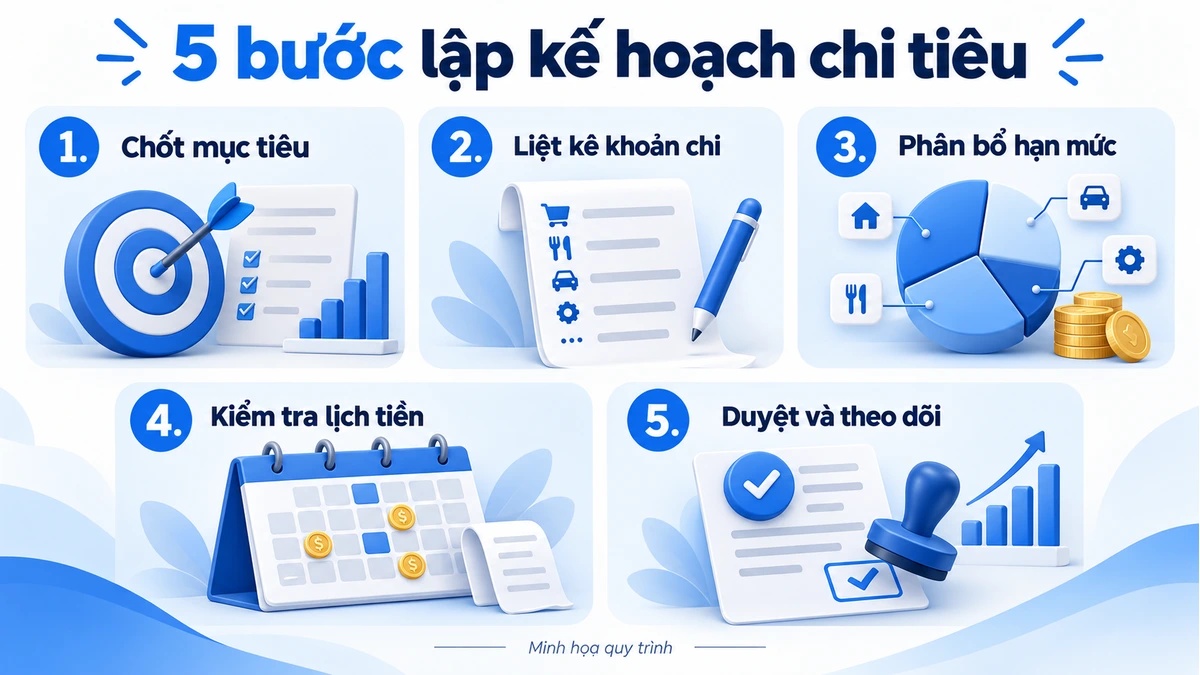
5 steps to creating a business spending plan.
Finalize targets and planning periods, create a list of expenses, prioritize them, check the payment schedule, and then assign responsibilities for monitoring. Each step needs to generate verifiable information, rather than simply recording a percentage increase or decrease compared to the previous year.
Step 1: Finalize objectives, planning period, and data sources.
Choose a period that suits your needs: monthly for managing recurring expenses, quarterly for coordinating campaigns or projects, and annually for longer-term resource allocation. Businesses with significant monthly cash flow fluctuations may consider adding weekly income and expenditure schedules.
Record specific goals such as maintaining operations at two sales points, launching a limited-spending campaign, or purchasing equipment to fulfill confirmed orders. Gather previous figures, contracts, purchase orders, payment schedules, staffing plans, and uncompleted proposals. One-time anomalies should be identified before using historical data as a baseline.
Step 2: List the expenses and clearly state the basis for the estimates.
For each item, record the quantity multiplied by the unit price, the usage period, or the contract terms. For example, estimate software rental based on the number of accounts and the number of months; estimate shipping based on the expected number of orders and the fee. Reference prices should include the update date and the person confirming the price.
It is possible to categorize costs by department, project, or purpose to assign responsibilities; and to distinguish between relatively stable costs and variable costs. Fixed costs are only relatively stable within the scope of the activity and the time period under consideration. As the scale changes, rent, personnel, or infrastructure costs can still increase proportionally.
For committed but unpaid amounts, record the remaining balance and the expected payment date. When compiling forecasts, clearly separate the amount already spent, the remaining committed amount, and the uncommitted needs to avoid counting the same amount twice.
Step 3: Prioritize and allocate quotas
Prioritize obligations due, funds necessary to maintain operations, and funds serving agreed-upon objectives. For new proposals, the proposer should state expected results, the timeframe for use, alternative options, and the consequences of delaying implementation.
The reviewer may accept, adjust the scope, divide the proposal into phases, or postpone it. When cost reductions are necessary, consider the impact on quality, revenue, schedule, and contractual obligations. Immediate savings may not necessarily lead to better results if they entail rework or operational disruptions.
Step 4: Check your payment schedule and prepare a contingency plan.
All expenditures are scheduled for payment, including deposits and installments. Compare these to the opening balance and collection schedule based on actual collection availability. Funds with restricted use or those already allocated to other obligations should be separated from the available funds.
Prepare for contingencies such as delayed payments from customers, price increases, or changes to orders. The reserve level should be based on the risk of each operation, data volatility, and access to funds, not a fixed percentage applied to all businesses. If funds are insufficient, renegotiate the payment schedule or terms with the relevant party before the deadline.
Step 5: Approval, assignment of responsibility, and monitoring.
The approved budget should include the person responsible for each expenditure group, the authorized person for approval, and the procedure for handling requests exceeding the budget limit. When transferring budget between accounts, record the reason and the approved version so that all departments can use the same data.
Simultaneously track payments made, outstanding obligations, and projected expenditures for the entire period. Keep the original budget for comparison; update forecasts as new information becomes available. If there are significant changes to objectives or scope of work, budget adjustments must go through the designated authority.
What columns should a budget plan include?
A complete expenditure record should indicate the expenditure item, basis for calculation, limit, payment schedule, and responsible person. You can add department, project, or supplier codes when you need to consolidate multiple tasks.
| Expenditure | Based on estimates | Estimated expenditure (million VND) |
Payment time | Responsibility and status |
|---|---|---|---|---|
| Office rental | Rental rate as per contract | 30 | Beginning of the month | Administration; committed obligations |
| Human Resources | Payment schedule and spreadsheet have been reviewed. | 200 | According to the monthly expenditure schedule. | Human Resources, Accounting; awaiting final confirmation. |
| Purchase | Quantity according to purchase order, payment schedule | 90 | Two installments as agreed. | Purchasing; having a commitment with the supplier. |
| Marketing campaign | Scope of work and quotation | 30 | After review and according to the implementation schedule. | Marketing; new proposals |
| Total projected | Same planning period, no overlapping items. | 350 | Further checks of the collection schedule are needed. | |
These figures are hypothetical to illustrate the table structure and are not intended as reference spending limits or salary levels. The numbers represent the total estimated payments including taxes and related obligations, if any; this table should not be used to calculate deductible expenses or tax obligations.
When implemented, add columns for "approved," "paid," "commitment outstanding," "expected uncommitted," and "reason for discrepancy." Unsettled advances should be tracked separately for reconciliation, avoiding adding them again when the expenditure documents are finalized.
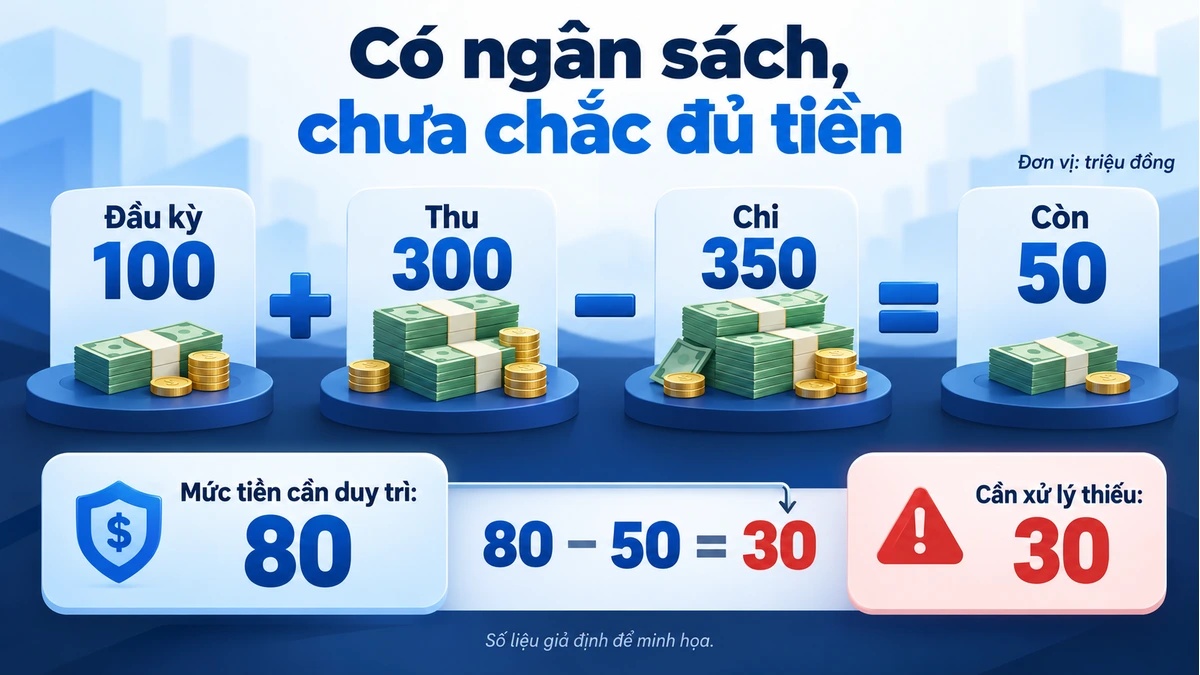
For example: the spending limit is met, but an additional 30 million VND in cash is still needed.
The ability to pay depends on the timing of incoming and outgoing funds, not just the total budget. Let's assume the business starts the month with 100 million VND in available cash, expects to receive 300 million VND, and has payments of 350 million VND according to the table above.
Expected ending cash = Beginning cash + Cash inflows - Cash outflows.
100 + 300 − 350 = 50 million VND.
If the business sets its own end-of-period maintenance amount at 80 million VND, the amount to be processed is 80 − 50 = 30 million VND. The 80 million figure is a governance assumption for the example, not a legal requirement or a general safety margin.
The person in charge may consider the possibility of early collection of a debt, readjusting the purchasing schedule, or postponing an uncommitted proposal. Each option must consider the contract terms, feasibility, and the approving authority. Do not automatically postpone due obligations or treat unapproved loans as guaranteed funds.
A positive ending balance can still mask a shortfall in the middle of the month. If 200 million VND in payments are due before the customer pays, a weekly or daily schedule should be created for that period. (Method) cash flow planning This helps to delve into the collection and payment schedule.
The principles for tracking beginning cash, cash receipts, cash disbursements, and ending cash are also presented in Instructions for creating a cash flow statement from business.gov.au. The example here only uses the principles of cash management; foreign tax regulations do not apply to Vietnamese businesses.
Monitor discrepancies to make the right adjustments to expenses.
Read about discrepancies in the same cause, timing, and workload. Spending less than your budget could be due to saving money, but it could also be because a payment has been carried over to the next month or there's unfinished work.
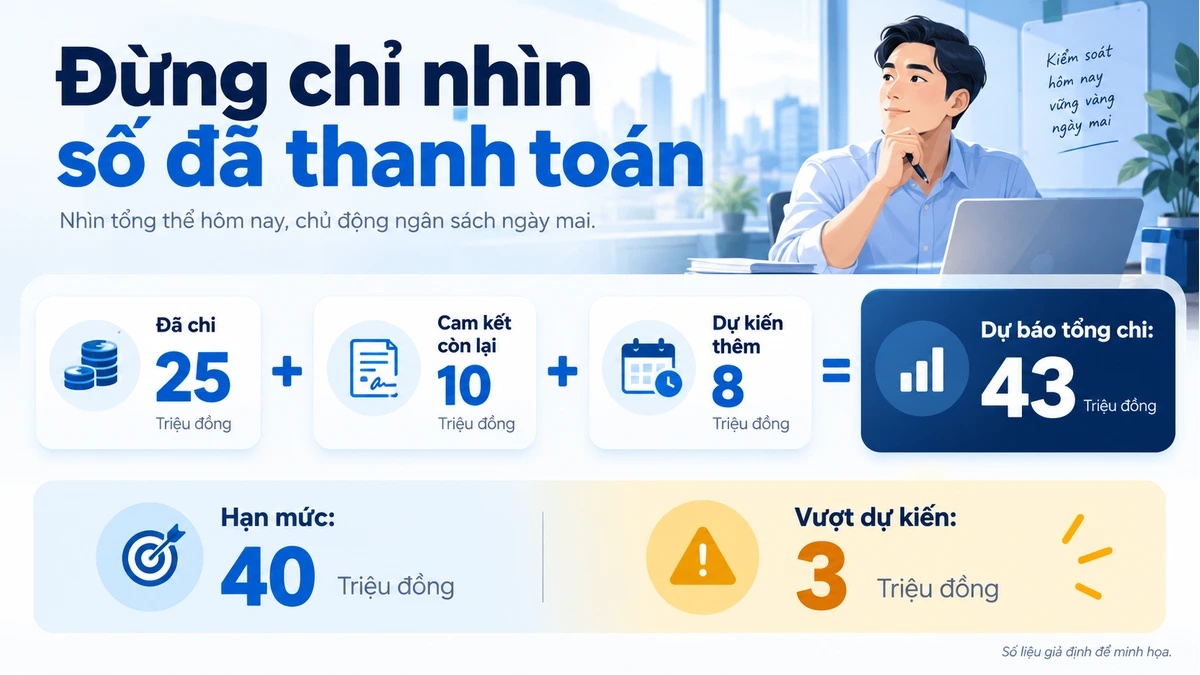
For example, an approved project costs 40 million VND; 25 million VND has already been spent, 10 million VND remains based on committed purchases, and an additional 8 million VND is expected for the unordered portion. The projected total expenditure is 25 + 10 + 8 = 43 million VND, That's higher than the 3 million limit. Just looking at the 25 million already spent will overlook the remaining needs.
- Difference due to mass: Have the number of orders, trips, or production changed compared to what was assumed?
- Difference due to price: Where do unit prices, discounts, shipping costs, or service scope change?
- Differences due to timing: Expenses have been incurred but not yet paid, or has the work actually been postponed?
- Differences due to range: Are there any new jobs that have been approved or proposals that have not yet been approved?
After identifying the cause, record the specific action, the person in charge, and the deadline for updating. The threshold for accountability can combine the amount, percentage, and level of risk; businesses can define it themselves according to their size and authority, rather than assuming that all amounts exceeding a certain percentage are treated the same way.
For expenditures that are no longer aligned with objectives, a review of the supplier, purchase volume, or process may be necessary. (Guidance) cutting business costs It is appropriate to assess the impact of each option individually, rather than implementing a blanket cut.
Should you choose a spreadsheet or software to manage your spending plan?
Choose the tool based on the number of participants, the number of expenses, and the approval requirements. Even when the data table is clear, but updates and coordination are often slow, there is still a basis to assess the need for software.
| Tools | Suitable when | Points to be organized |
|---|---|---|
| Simple paper or form | Fewer expenses, fewer people updating. | Keep the approved copies and gather the supporting documents; the totaling and reconciliation are mostly done manually. |
| Spreadsheet | Formulas, grouping, and period-based comparisons are needed. | Standardize expense codes, editing permissions, versioning, and recipe validation; usage costs vary depending on the tool and license. |
| Cost management software | Multiple departments submit proposals, multiple levels of approval are required, and a consolidated report is needed. | Examine how limits, approval flows, input data, and exception handling are set up in the deployment configuration. |
The transfer of tools that cannot be automatically corrected assumes incorrect revenue or payment schedules. Before implementation, a typical process should be selected, responsibility agreed upon, and data reconciled between the plan, proposal, approval, and actual figures.
When it is necessary to link the budget with the expenditure request and approval.
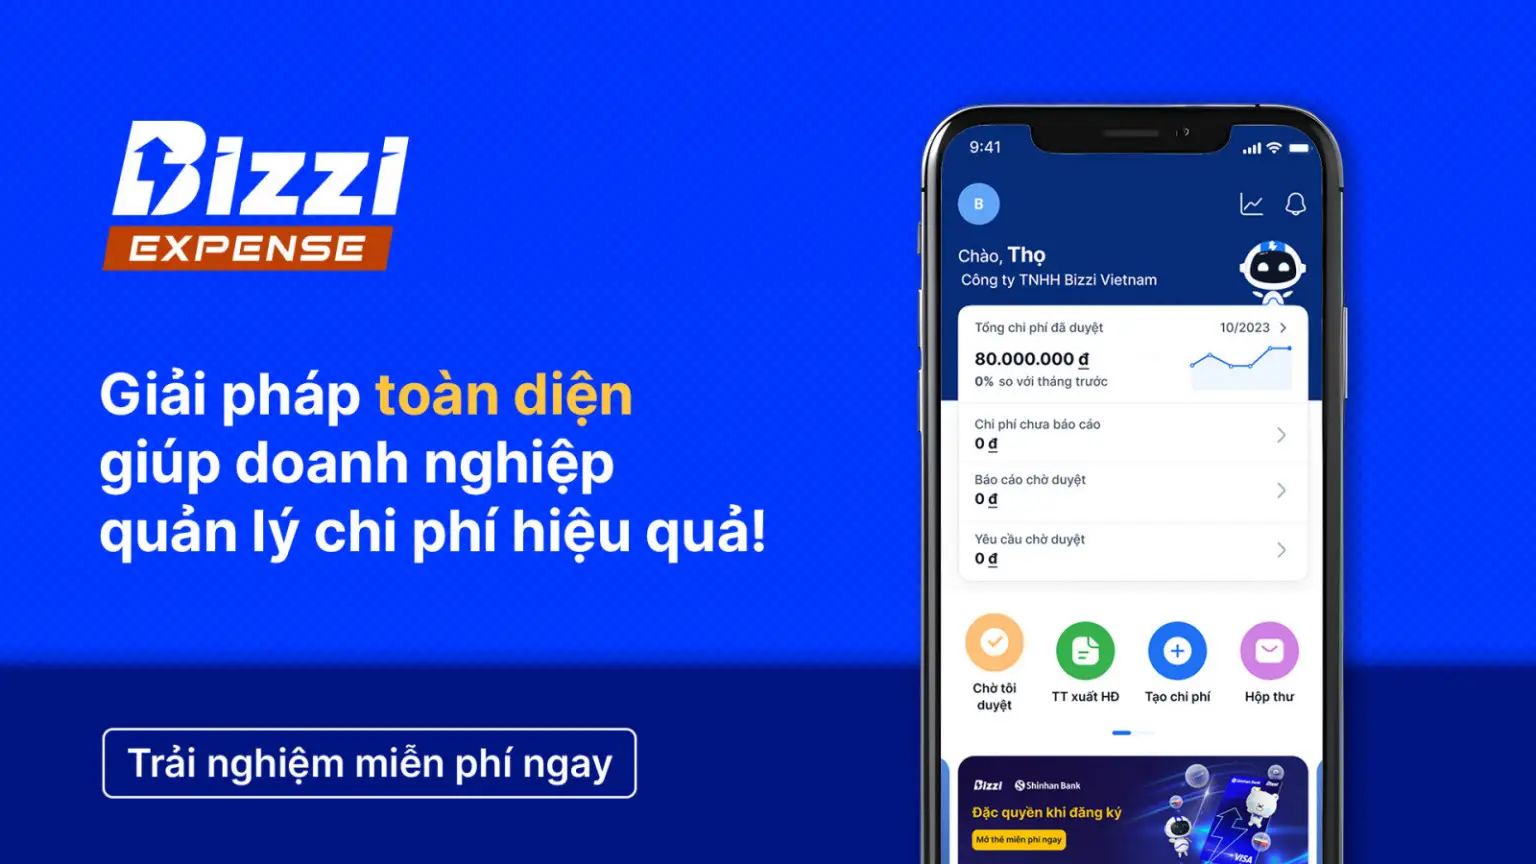
Businesses can find out Bizzi Expense cost management solution For budgeting, proposal, and expense reporting purposes, when communicating requests, a real-world unit scenario should be used to test the functional scope, approvers, and data aggregation methods to ensure a suitable configuration.
The criteria that need clarification include whether the committed amount is reflected in the way the business needs, the timing of data updates, the process for handling overspending, and the ability to reconcile with accounting data. The plan and responsibilities for verification still need to be established by the business beforehand.
Frequently Asked Questions When Planning Your Spending
Should you plan your spending on a monthly or yearly basis?
An annual budget can be used to allocate resources, monthly plans for implementation, and weekly payment schedules for closer control over payments. Choose a level of detail based on activity fluctuations, avoiding a uniform annual cost breakdown across 12 months if there are seasons or specific payment milestones.
Is spending less than the budget always a good thing?
It's too early to draw a conclusion. We need to see if the work is complete, what payments are still due, and whether the output quality meets the requirements. Low spending due to delays or failure to record other obligations is not necessarily a genuine saving.
Should the budget remain unchanged when forecasts change?
Keep the originals for comparison and update forecasts for operational purposes. If the official budget changes, record the reasons, scope, and authorized approvals to avoid losing track of the assigned figures.
What percentage of the budget should be allocated to contingency funds?
There is no one-size-fits-all ratio for every business. The type of risk, price volatility, certainty of the collection schedule, and non-deferable obligations must be considered. The provision should have a clear purpose and conditions for its use.
How does a new business with no historical data begin?
Start with minimum obligations and requirements, quotations, payment terms, and assumed activity volume. Add scenarios for delayed payments or higher costs, then update with actual figures as soon as activity occurs.





