


Enterprise value is the estimated economic value of a business or equity stake at a given point in time, based on specific purposes and assumptions. To understand this figure, it's necessary to know whether the valuation is based on operating value or shareholder value. Total assets, registered capital, revenue, and desired selling price alone are not sufficient to replace the valuation result.
What is enterprise value and what does that number tell us?
Enterprise valuation answers the question: given its assets, revenue-generating capacity, and existing risks, how much is the business valued at a given date? Valuation is a process of moving from data and assumptions to an explainable outcome. The number only has meaning when the reader understands its scope, basis, and timing.
For example, a business with a large factory but much of its equipment is no longer in use will be viewed differently from a business with few tangible assets but stable customer contracts. Asset size is part of the information; it is the ability to generate economic benefits from those assets that helps explain the results.
In finance, Enterprise Value (EV) It is commonly used to analyze the operating value of a business for capital providers. Equity value This is the equity value as assessed. When reading reports or transaction proposals, confirm which metric the preparer is using instead of assuming all "company value" figures are the same.
Three questions to ask first: Are you valuing the entire business or a portion of its capital? What date are the results from? Is the business assumed to continue operating or be liquidated? A valuation lacking this information is difficult to use for comparison or negotiation.
“"Core values" such as honesty, responsibility, and collaboration speak to organizational culture. These elements can influence business operations, but they are not a financial valuation figure to be directly added to the company's value.
Distinguish between enterprise value, equity, and transaction price.
Operating value and shareholder equity are related but differ due to debt, cash, and related interests. The transaction price, on the other hand, is the result of actual negotiation. Separating these three layers helps avoid using a single valuation to answer the wrong question.
| Quantity | Meaning | Things to check |
|---|---|---|
| Operating Value / EV in the current model | Value associated with the activity for capital providers. | The scope of cash, non-operating assets, and adjustments to the model. |
| Equity value as appraised | The portion of the value that belongs to the owner after settling all related obligations and rights. | Debt, preferred stock, non-controlling interest, or other adjustments, if any. |
| Equity on the accounting books | Differences between assets and liabilities are recognized on an accounting basis. | The book value may differ from the valuation. |
| Market capitalization | Market price of shares multiplied by the number of shares | This is a figure at the equity level, not including debt financing itself. |
| Trading price | The price the parties actually agreed upon for the scope of the transfer. | Ownership percentages, control rights, payment terms, and commitments. |
Registered capital reflects information about capital as recorded in legal documents; it doesn't automatically indicate how much a company can sell. Revenue is also not the value of the business: two companies with the same revenue can differ significantly in profit margins, investment needs, and ability to collect payments.
When transferring a portion of equity, the total equity value plus the ownership percentage should not be considered the final price. Rights associated with the equity stake, transfer restrictions, and specific conditions must also be considered. A valuation report is a basis for negotiation; it does not guarantee that the buyer will accept that price.
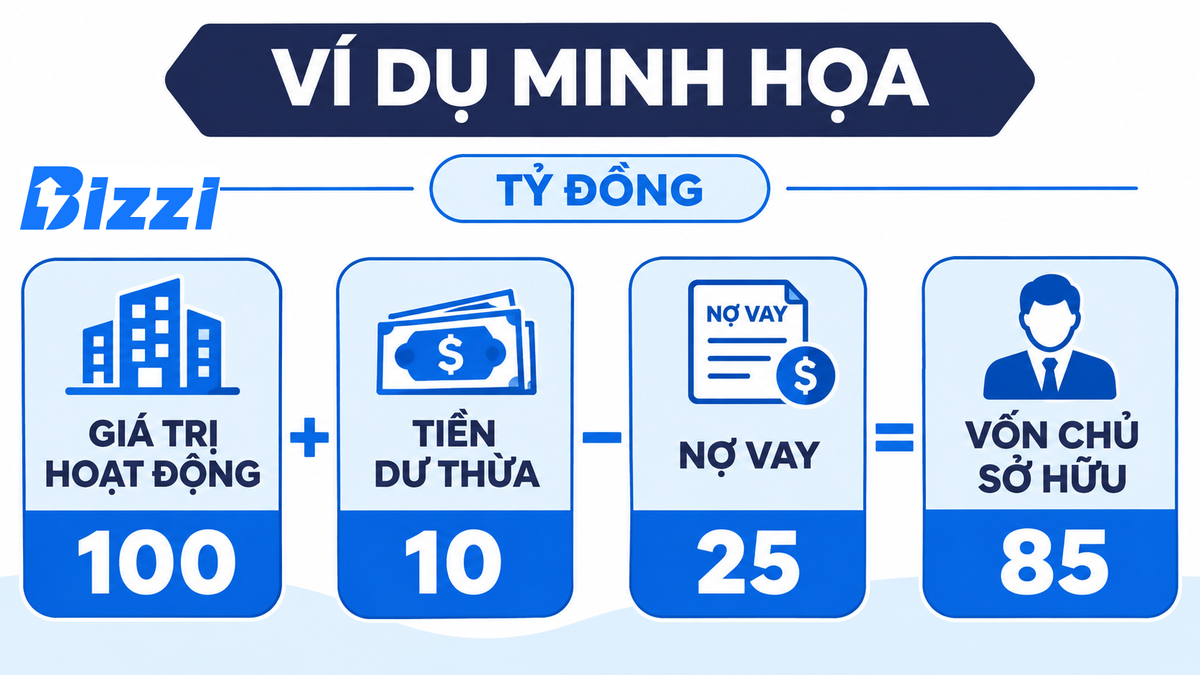
For example, going from operating value of 100 billion VND to equity of 85 billion VND.
Assume the operating value of Company A is estimated at VND 100 billion. The company has VND 10 billion in excess cash not reflected in the VND 100 billion operating value and VND 25 billion in debt. If only common stock is held and there are no other obligations, rights, or adjustments, the equity value is:
100 + 10 − 25 = 85 billion VND.
Operating value + excess cash not accounted for in operations - debt = equity value as assumed in the example.
Do not mechanically add all cash balances to the model. It is necessary to determine which amounts have served operations or have been reflected in cash flow, and which are truly separate. If an asset and its economic benefits have already been accounted for in operations, adding the value of that asset again may cause double counting.
Similarly, do not subtract the entire second liability if the model already partially reflects the obligation in working capital or cash flow. The scheduler needs to explain each adjustment and reconcile the method's results with the correct portion of capital being valued.
When does a business need to determine its value?
Valuation is useful when a business needs a basis for negotiation, resource allocation, or evaluating ownership options. The intended use determines the scope of data and the level of verification required.
- Capital transfers, mergers or acquisitions: Clarify the operational value, capital contribution, and associated obligations before negotiations begin.
- Raising capital or changing ownership structure: Consider the existing capital and the impact of the new investment; do not confuse the money expected to be raised with the money already available.
- Restructuring, divestment, or consideration of ceasing operations: Compare the options based on appropriate assumptions, rather than using a single consistent performance result for all situations.
- Internal management: Identify the sources of value creation, risks, and assumptions that cause outcomes to change.
Some legal, accounting, or transactional tasks require specific valuations. It's crucial to determine the exact requirements of each case before hiring the service or utilizing the results; not every business needs an annual revaluation solely for tax reporting purposes.
For a loan, the bank also assesses the borrower's ability to repay, their documentation, and the security conditions of the transaction. A business valuation report does not automatically convert the entire "company value" into collateral, nor does it guarantee loan approval.
Three approaches to determining business value
A business can be evaluated based on its assets held, future economic interests, or market data. Article 7 of the Standards issued with Circular 36/2024/TT-BTC stipulates three approaches: market, cost, and income. The method applied must be consistent with the business's valuation basis and operating status.
The asset-based method requires reassessing assets and liabilities.
The asset-based method considers tangible assets, financial assets, intangible assets, and liabilities to determine value within the scope of the valuation. It is not advisable to simply copy the total assets on the balance sheet and call that the enterprise value.
For example, a factory may differ significantly between its book value and its appraised value at the valuation date. Slow-moving inventory, uncollectible receivables, and unrecognized obligations can also alter the results. Ownership records, usage rights, and actual conditions need to be reconciled with the data.
This approach can be useful for businesses with multiple assets or for cross-checking results. It's not just for liquidation businesses. However, evaluating a business in operation must consider the potential for generating benefits from the asset portfolio, not automatically assuming that selling each asset separately is the only scenario.
Discounting cash flows requires using the correct cash flows and discount rate.
The income-to-cash-flow approach forecasts the timing of valuation. The model needs to explain how revenue translates into cash after expenses, taxes, investments, and working capital requirements. Accounting profit or EBITDA that does not automatically equal cash flow can be used in the model.
In the commonly used model, free cash flow to the firm (FCFF) is discounted using the weighted average cost of capital (WACC); free cash flow to shareholders (FCFE) is discounted using the cost of equity. FCFE already reflects the impact of debt financing, so debt is not further reduced in the same way as the operating-level results.
To read the input before creating a valuation model, see how to differentiate. FCF, FCFF, and FCFE. Revenue growth plans must be accompanied by assumptions about cash collection, inventory, and capital expenditures; simply extending profits from the most recent year will overlook these capital needs.
If using end-of-period values, long-term assumptions and reinvestment levels to sustain operations must be checked. Small changes in growth or capital costs can significantly alter results. It is advisable to present well-founded scenarios rather than a seemingly precise figure.
Market comparisons require a similar scope and criteria.
The market approach uses comparable or matching business data. Being in the same industry is not enough to consider two companies similar: size, growth, risk, capital structure, and data quality can differ.
EV/EBITDA is used to reflect earnings before interest expenses, while P/E is linked to the corresponding portion of earnings attributable to equity. Do not simply apply a single EV/EBITDA ratio directly to after-tax earnings. All metrics must be consistent across reporting periods, scopes, and methods for excluding unusual items.
The revenue ratio is not a "standard multiplier" that applies to every company. If two businesses have different profit margins and investment needs, the same revenue does not guarantee the same value. For businesses that are losing money or have limited transaction data, the applicability and limitations of the ratio should be considered instead of choosing the highest one available.
Legal scope: Circular 36/2024/TT-BTC applies to enterprise valuation in accordance with the law on pricing; it takes effect from July 1, 2024 and replaces Circular 28/2021/TT-BTC. An internal estimate does not replace reports, certificates or professional requirements of a specific transaction. (Readable) Circular 36/2024/TT-BTC and the attached official version. To compare the scope of application.
What factors cause valuation results to change?
Results change as expectations about economic benefits or risks change. Analysis of each factor should highlight its impact on the figures, rather than automatically adding a "brand value" or "personnel value.".
| Element | The question needs to be answered. | Verifiable evidence |
|---|---|---|
| Revenue and Profit Quality | Which expenses are recurring, and which are one-time occurrences? | Contracts, customer structure, detailed ledger, and multi-period results. |
| The ability to convert profits into cash. | Is the money tied up in liabilities, inventory, or large investments? | Debt age, inventory turnover, investment plan, and cash flow. |
| Assets and exploitation rights | What does the business actually own or utilize? | Legal documentation, inventory, property condition, and restrictions. |
| Human resources, brand, and customers | Will the benefits continue if the business owner or major customer leaves? | Contracts, concentration ratios, succession planning, and the ability to maintain profit margins. |
| Industry environment and cost of capital | How do changes in competition, interest rates, or regulations affect things? | Industry data, funding conditions, and operating scenarios. |
A strong brand can support selling prices or retain customers, but that benefit needs to be consistently reflected in the methodology. If brand-related revenue and profit margins are already included in projected cash flows, adding the full brand value separately without adjustment risks double counting.
Revenue growth doesn't necessarily translate into increased value. If a business has to sell at very low margins, incurs long-term debt, or invests beyond its cash-generating capacity, the increase in scale may come with higher capital requirements and greater risk.
How do I prepare the documentation and review the valuation results?
Start with a comparable dataset, then choose a model. The steps below help business owners and finance departments prepare; they do not replace professional processes when a formal valuation is needed.
- Finalize the purpose, date, and scope. Specify whether it refers to the entire business or equity, whether it is a separate or consolidated report, and whether it assumes continued operation or otherwise. The output is a description of the scope that is mutually understood by all parties.
- Gather and compare data. Prepare financial statements, detailed ledgers, asset records, loan records, accounts payable records, key contracts, and business plans. Separate verified data from management's forecasts.
- Clarify the amounts that need adjustment. Create a table of non-recurring income and expenses, assets outside of operating activities, and related liabilities. Each adjustment should be documented, with a reason and its impact on the model, not just a single line of addition or subtraction.
- Choose a method based on the data. Explain why the method is appropriate; if market data is lacking or the forecast is unreliable, state the limitations and consider alternative testing methods.
- Compare the results and the assumptions. Verify the connection between operating value and equity, avoid double counting assets, test key variables, and explain the differences between methods.
- Record the usage of the results. Include the source, date of data, currency, scope, assumptions, limitations, and responsible party. When purposes or conditions change, reassess the relevance of the previous results.
For publicly traded company data, guidelines Search for financial reports of companies This helps in selecting the correct source, period, and type of report. Do not merge one company's consolidated figures with another company's separate report while ignoring scope differences.
Article 6 of the Standard accompanying Circular 36 prioritizes the use of reports audited or reviewed by an independent auditing firm. If unaudited reports, reports not reviewed, or reports with non-unqualified opinions are used, limitations must be stated as prescribed by the standard. Therefore, "unaudited" should not be interpreted as implicitly unassessable; reliability and limitations must be clearly addressed.
When two or more methods are used, Article 8 stipulates that a weighted average of the results should be calculated to determine the equity value, with weights based on reliability, input data, purpose, and relevant factors. A uniform average should not be taken simply because of differing results, nor should the highest result be chosen to meet one party's expectations.
What data do small businesses need to clarify before setting a price?
For small businesses, the challenge often lies in separating business operations from personal finances and the dependence on a few individuals, customers, or contracts. A clear data table is more helpful than pre-selected coefficients based on size labels.
- Costs for the business owner: Distinguish between personal expenses, management salaries, and the costs necessary for others to continue operating. Do not eliminate all employer salaries in order to achieve higher profits.
- Related transactions: Clarify rent, purchase price, and liabilities with relevant parties, along with the basis for any adjustments.
- Customers and key personnel: Determine the level of focus, contract duration, relationship transferability, and replacement team.
- Revenue, cash collection, and inventory: Compare the ledger with actual transaction records; clarify slow-moving inventory, uncollectible receivables, and debts that have not been fully recorded.
- Post-transfer plan: Who will operate it, how much additional investment is needed, and what resources can justify the growth assumption?
If the sudden increase in profit is due to an asset sale, present that item separately instead of using the entire year as recurring income. If the plan depends entirely on the business owner continuing to work, state this condition so the reader understands the assumptions on which the results are based.
Frequently Asked Questions about Business Valuation
Does negative equity on the books mean the business is no longer worth anything?
It's impossible to draw conclusions from just one criterion. The company needs to consider its operational capacity, assets, liabilities, and remaining value for the owner using appropriate methods. Conversely, a positive book value of equity doesn't guarantee that shares will sell for at or above that level.
Can business owners estimate the value themselves?
Estimates may be made to understand the data and prepare for exchange, provided that assumptions, scope, and limitations are clearly stated. When a transaction requires a legally mandated valuation or an independent opinion, the requirements of that case must be met; internal spreadsheets do not automatically replace professional documentation.
Is a revaluation necessary when a business receives additional funding?
It is necessary to determine whether the valuation is before or after the investment, whether the funds have been received or are new, and the terms of the equity issuance. Do not add the new funds to both the operating value and the cash balance and then recalculate. If the date or purpose of use has changed, the basis of the previous result must be reviewed.
Before using a valuation figure, request a link to the correct capitalization, adjusted portfolio, and key assumptions. This is a quick way to identify whether two reports are genuinely disagreeing on value or simply measuring two different ranges.
Reference material on methodology: CFA Institute, Free Cash Flow Valuation and Price and Enterprise Value Multiples. The calculations in this lesson are hypothetical examples to explain the concept.





