


Free cash flow (FCF) indicates how much cash a business generates from its operations after deducting identified capital expenditures. The common calculation is net cash flow from operations minus CapEx. This indicator helps assess the ability to reinvest, repay debt, and distribute cash, but it does not replace checking the actual payment schedule.
What is free cash flow and how does it differ from profit?
FCF is a cash flow analysis indicator, not the cash balance in an account. A business may have positive FCF during the year but still be short of cash on a due date; conversely, ending cash may increase through new borrowing even with negative FCF.
Profit reflects revenue and expenses for the accounting period. Cash flow reflects receipts and disbursements: sales without payment resulting in accounts receivable; purchases for inventory holding, keeping cash in inventory; purchases of machinery resulting in investment expenses even though the cost is gradually allocated through depreciation. Therefore, a company's profit does not necessarily mean it has generated sufficient cash after investment.
| Target | Answer the question | It is not yet possible to conclude. |
|---|---|---|
| Profit after tax | What was the recorded business result for the period? | Has the customer paid in full yet? |
| CFO or OCF | What is the net cash flow generated by the business operations? | How much is left after investment in assets? |
| FCF according to CFO − CapEx | After the identified investment expenditures, what is the remaining cash flow? | All of this money can be distributed to shareholders immediately. |
| Ending balance | How much cash does the business have at the end of the period? | The increase comes from business operations, borrowing, or selling assets. |
The way reports are prepared also affects the calculation and comparison of FCF. Cash flow classification, CapEx scope, and adjustments may vary between businesses. When making comparisons, it is necessary to review the calculation methods and compare them to the same period, same unit, and same consolidation scope.
How to calculate FCF from the cash flow statement.
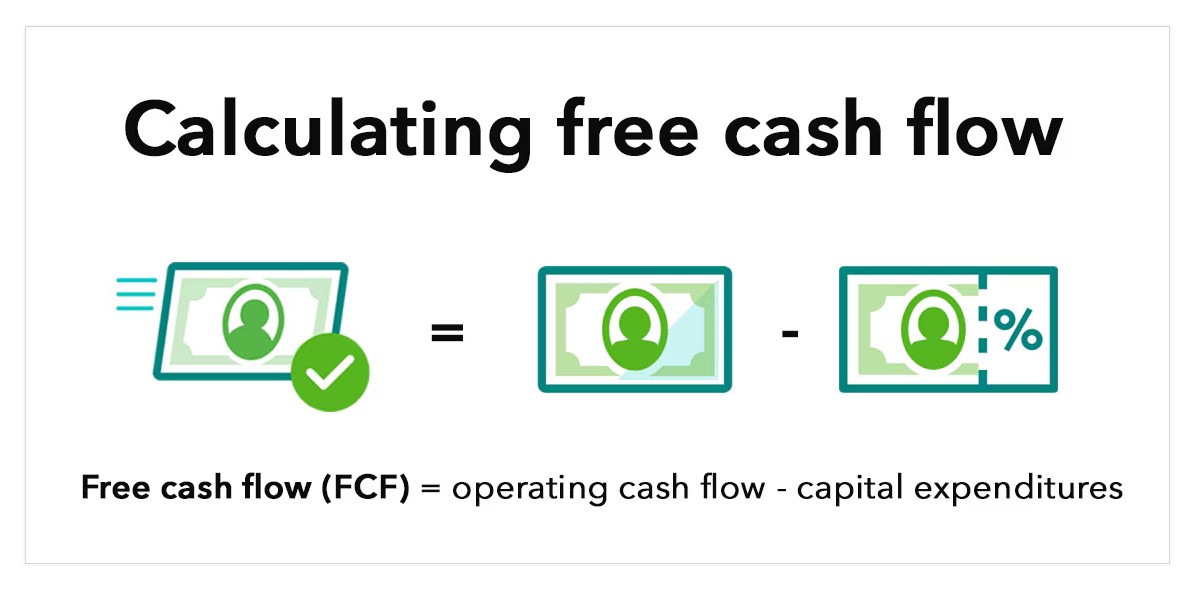
FCF = CFO − CapEx
CFO represents net cash flow from operating activities. CapEx in the calculation below is the actual amount spent on long-term assets used in operations, recorded as a positive number when subtracted.
The net cash flow from operating activities is used to determine the CFO. With CapEx, separate the investment expenditures that need to be calculated: financial investments, business acquisitions, and proceeds from asset disposals may need to be separated depending on the definition being used.
- Closing date and reporting scope. Select the most recent quarter, year, or 12-month period; use either separate or consolidated reports consistently. Do not combine six-month CFO reports with full-year CapEx reports.
- Get the CFO for the correct period. Read the net cash flow from operating activities and explain any significant changes. Use signed net numbers, even negative ones.
- Determine the amount of money spent on asset investments. Read the cash flow statements for asset purchases and construction, along with any accompanying notes; clearly indicate whether intangible assets or other expenses are included. For amounts shown in parentheses, convert them to positive values before subtracting them.
- Calculate and create a comparison table. Subtract CapEx from CFO. Include the data source, units, and any exclusions so that the reader can recalculate.
- Explain the change. Separate the impact of operations, working capital, and investment; look at the same repayment schedule, lease obligations, and cash needs for the coming period.
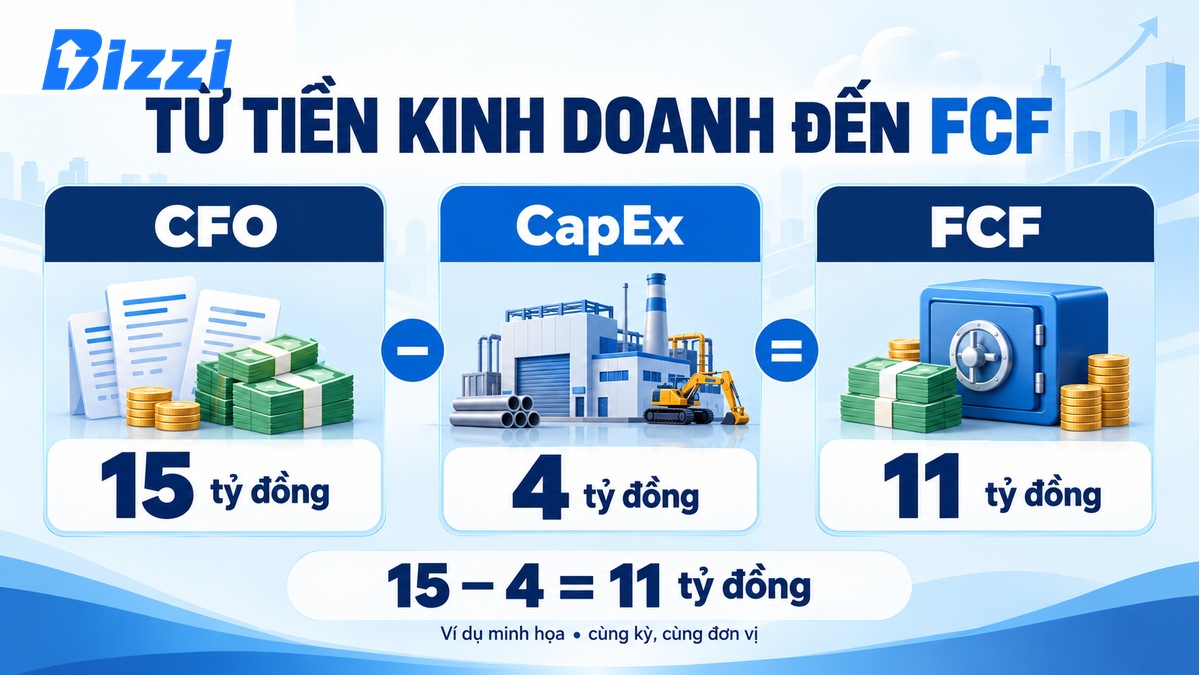
For example, CFO has a salary of 15 billion VND, CapEx has a salary of 4 billion VND.
Company A has a CFO of VND 15 billion in year N and investment expenditures of VND 4 billion. Both figures are for the same period and within the same scope; for example, without other adjustments. Then... FCF = 15 − 4 = 11 billion VND. If the asset expenditure line on the report shows “(4)”, the calculation is still 15 − 4, not 15 − (−4).
Suppose the company has to repay a loan principal of 8 billion VND next year and needs to add a reserve fund for operations. Before allocating 11 billion VND, the company needs to create a schedule of income and expenses, set aside funds for the loan due, and check remaining commitments.
Why shouldn't you calculate CapEx by subtracting beginning-end assets from ending assets?
The approximate formula “Ending PPE − Beginning PPE + Depreciation” is only suitable when other variables have been accounted for. Liquidation, exchange rate differences, business acquisitions, revaluations, or non-cash asset creations can all skew the results. For cash-based FCF, prioritize cash flow figures and explanatory notes; the asset change statement is used for comparison.
How do working capital and depreciation go into FCF?
If the CFO figure has already been used in the report, do not subtract working capital changes or add depreciation again. These factors were already included in the CFO selection process. Subtracting or adding them together would result in double counting.
When calculating cash flow from profits, it is necessary to fully reconcile non-cash adjustments, investment or financing activities, and changes in operating working capital. Simply adding depreciation to profits and subtracting CapEx may miss accounts receivable, inventory, and other significant adjustments.
For a simple example, without any other adjustments: net profit after tax is VND 12 billion, depreciation is VND 3 billion, and working capital increases by VND 2 billion. The simulated CFO is VND 12 + 3 − 2 = VND 13 billion. If CapEx is VND 4 billion, FCF is VND 9 billion. This is an illustrative table of calculation conditions, not a simplified formula applicable to all reports.
| Fluctuations | Common effects on money, all other factors remaining constant. | Things that need checking |
|---|---|---|
| Accounts receivable from customers increased | Outstanding cash increases, CFO decreases. | Debt age, payment deadlines, invoice disputes |
| Inventory increased | Cash held in inventory increases, CFO decreases. | Seasonality, sales speed, slow inventory turnover. |
| Increased operating costs | Holding cash temporarily, CFO raises | Is the debt still due or overdue? |
Working capital in the FCF model is typically: Working capital excludes cash and debt., Instead of automatically subtracting short-term liabilities from all current assets, each item needs to be identified and used consistently. See more How to distinguish between working capital and working capital requirements when creating a comparison table.
Do FCF, FCFF, and FCFE use the same formula?
Each metric serves a different perspective. FCF = CFO − CapEx is a common way to track it; FCFF and FCFE differentiate the portion of money allocated to funding sources. Therefore, the correct cash flow and discount rate must be selected for analytical purposes.
| Target | Perspective | What needs to be kept consistent |
|---|---|---|
| FCF according to CFO − CapEx | Operating cash after investment expenditures have been determined. | Defining CFO, CapEx, and adjustments. |
| FCFF | Cash flow to the company's capital providers. | Cash flow before financing and cost of capital are appropriate. |
| FCFE | Cash flow to common shareholders after the impact of debt financing. | New loans, principal repayments, and equity costs. |
In the common model where the CFO has already factored in interest expenses: FCFF = CFO + interest expense × (1 − t) − asset investment; FCFE = CFO − investment in assets + net borrowings. Net borrowing is new borrowing minus principal repayment, and t is the appropriate tax assumption of the model. If the report classifies interest expense differently or has a complex capital structure, adjustments are needed before use.
According to CFA Institute cash flow valuation document, FCFF is discounted using the weighted average cost of capital (WACC), while FCFE is equal to the required rate of return on equity. When converting from operating value to equity value, debt and related non-operating assets must also be considered. See Methods for determining business value To place the results into the correct model.
For monthly management purposes, businesses can start with a clearly referenced CFO – CapEx statement. A valuation model should include operational forecasts, investment, capital structure, and sensitivity testing; a current FCF result should not be used as a fixed growth rate indefinitely.
Read positive, negative FCF and fluctuations over multiple periods.
The value of FCF lies in the underlying cause. A positive or negative sign alone is insufficient to assess whether a business is strong, weak, or a stock worth buying.
FCF is positive but quality control is needed.
A stable CFO after necessary investments can provide resources for debt repayment, provisions, and reinvestment. However, FCF can also increase due to the recovery of old receivables, temporary inventory reductions, extended payments, or delayed maintenance. Consider whether the increase is repeatable and whether it will impair operational capacity.
For example, CFO remains at VND 15 billion, but CapEx decreases from VND 4 billion to VND 1 billion, and FCF increases from VND 11 billion to VND 14 billion. If the cuts are unnecessary investments, this could be an improvement. If it's machinery that needs replacing to maintain production, higher FCF today carries the risk of large expenditures or disruptions later.
Negative FCF: Separating operational difficulties from expansion needs.
CFO of VND 15 billion and CapEx of VND 18 billion create FCF of -VND 3 billion. If the expansion investment is on schedule, funding sources and revenue expectations are sound, a negative figure does not automatically prove failure. Capacity utilization, market demand, and a plan to cover the shortfall need to be examined.
Negative CFO due to slow debt collection, inventory, or declining operating margins requires a different approach. In such cases, increasing borrowing only increases cash flow and does not automatically improve FCF. Compare companies across multiple periods within the same scope and consider industry cycles, rather than applying a single "good FCF" threshold to all companies.
FCF is not an entirely arbitrary amount of money to spend. SEC guidance, section 102.07 Please note that the calculation of FCF is not standardized and may not deduct mandatory obligations. This is a note regarding analytical methodology, not a regulation of Vietnamese accounting.
Improve FCF through disciplined operations and investment.
Before cutting spending, identify where cash is being tied up and which expenses create capacity for the next period. The goal is to increase sustainable cash generation, rather than increasing FCF for a period by delaying necessary expenses.
- Collect payment as agreed: Complete delivery documentation, reconcile accounts payable, resolve disputes promptly, and assign personnel to monitor overdue payments. Increasing credit sales revenue doesn't necessarily guarantee an immediate increase in the CFO position.
- Reduce unnecessary inventory: Focus on actual demand, monitor slow-moving inventory and supply times; avoid cutting costs to the point of shortages or production disruptions.
- Cost control based on efficiency: Review duplicate, misused, or over-budgeted expenditures; protect spending necessary for quality, safety, and customer service.
- Manage supplier payment schedules: Take advantage of agreed terms, consider payment discounts and supply risks. Holding onto cash by delaying payments is not a sustainable improvement.
- CapEx Divergence: Separate maintenance and expansion, view cash flow by progress, and evaluate project effectiveness. Leasing instead of buying can change payment schedules and contractual obligations, and does not automatically save money or make the business better.
Each month or quarter, there should be a link between profit and CFO, and from CFO to FCF, with a person in charge of major fluctuations. This will help in making short-term spending decisions, in conjunction with... revenue and expenditure plan and cash flow management, debt due dates and risk provision levels based on actual risk.
Control expenses before compiling cash flow.
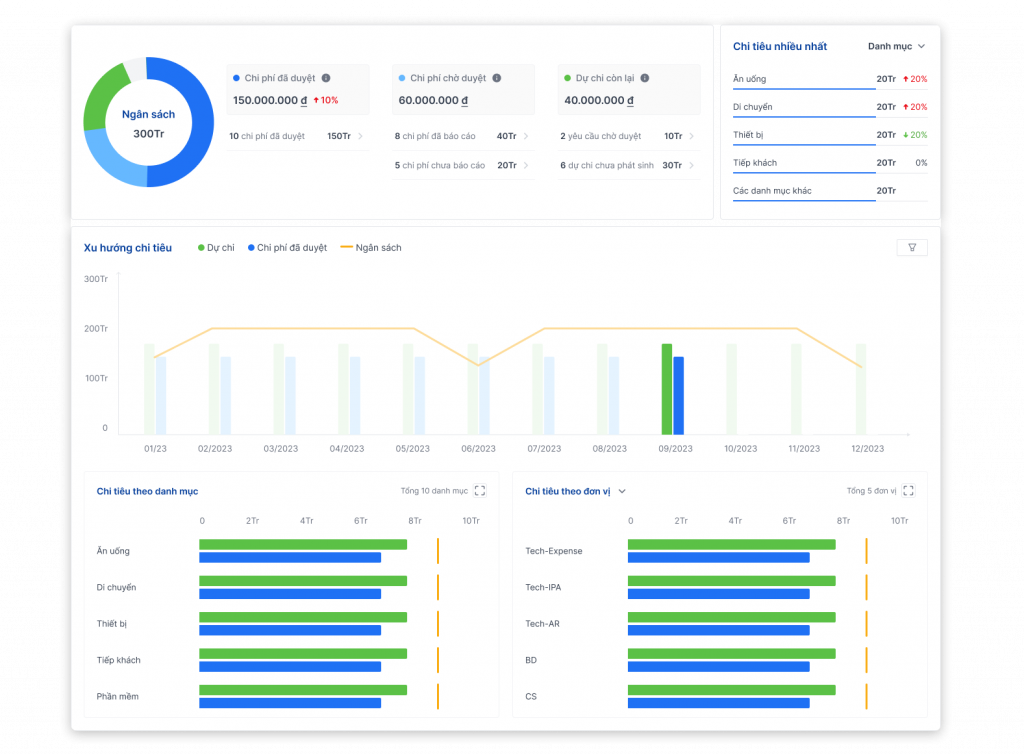
If tracking spending limits, requests, and actual expenditures is fragmented, businesses can explore Bizzi's expense management solution. Information on approved and actual expenditures helps accountants reconcile spending with the budget. When preparing FCF (Foreign Cost Cost), accountants combine this data with the cash flow statement and asset investment records.
Frequently Asked Questions about Free Cash Flow
Are CFO and OCF different?
In the context of this article, both refer to net cash flow from operating activities. It's important to distinguish between CFO as a technical indicator and CFO as the title of Chief Financial Officer when reading other documents.
Is FCF equal to EBITDA excluding CapEx?
It cannot be changed directly. EBITDA does not fully reflect taxes, working capital changes, and related expenses. It needs to be converted to the appropriate cash flow before deducting investment expenses.
Does a positive FCF guarantee dividend payments?
No. Cash available at the disbursement date, debt due, and applicable commitments and distribution conditions must be considered. A period's FCF (Foreign Cash Flow) does not automatically guarantee that all of those conditions are met.
Is it possible to exclude only the retained CapEx when calculating FCF?
A separate analysis of the remaining CapEx (Capital Expenses) can be conducted if there is a basis for separating the data and clearly stating the calculation method. Do not directly compare those results with businesses that deduct all CapEx. Depreciation does not automatically equal the maintenance expense requirement.
Should this calculation method be used for banks?
It is not advisable to mechanically apply the model of non-financial businesses. For financial institutions, lending, fundraising, and capital requirements play a different role; models and data tailored to their specific operations are needed.





