


Project cost management is the process of estimating resources, budgeting, tracking incurred costs, and updating forecasts to complete the agreed-upon scope of work. The manager needs to know how much the project has cost, what obligations remain unpaid, and how much more is needed to complete the project.
A new project that has used half of its budget may still risk overspending if little work is completed or many contracts have been signed but not fully recorded. Therefore, the tracking sheet should place costs alongside completed work, purchase commitments, and remaining work.
What does project cost management involve?
Project cost management includes defining cost scope, preparing estimates, approving budgets, recording actual costs, analyzing discrepancies, and handling changes. These tasks are ongoing from the preparation stage to acceptance, contract liquidation, and project closure.
For example, when implementing a new sales system, businesses must factor in internal staff, implementation contractors, licenses, data, testing, and training. If they only include the software contract cost, the budget might miss the time spent by the operations team and the cost of data refactoring before the migration.
The goal is to detect deviations from the plan early, select appropriate solutions, and determine who has the authority to decide on additional expenses. Monitoring support costs helps protect progress, quality, and funding; the outcome also depends on the scope, implementation capacity, market, and decisions of the parties involved.
At the enterprise level, cost control It encompasses many departments and regular activities. For a project, data needs to be grouped around the project code, work package, and specific completion deadline.
Determine sufficient costs and avoid double allocation.
Project costs should reflect resources within the approved scope, with consistent classification rules. An expense can be directly related to the entire project or indirectly to individual work packages; the tracking level needs to be determined before categorization.
| Group | For example | Control methods |
|---|---|---|
| Direct | Labor hours, materials, and contractors for the work package. | Attach job code, quantity, unit price, and confirmation code. |
| Used jointly or indirectly | The equipment is used in many projects, offices, and for general support. | Select criteria related to usage levels; compare total allocation. |
| Management and allocation | Management resources are allocated by the company to the project. | Clearly state which items are already included in indirect costs to avoid double counting. |
| Preventive | Amount for risks and uncertainties under approved policy | Attach the basis, the authorized person, and the conditions of use. |
When using newly purchased equipment across multiple projects, clearly identify whether the report is tracking the purchase price, usage costs, or internal allocations. Do not combine the entire purchase price and allocation of the asset itself into a single total cost within the same scope.
Personnel working on multiple projects simultaneously require a verified basis for time or workload allocation. Monthly salaries do not automatically become a direct cost of a project simply because the employee participated in that project.
Choose an estimation method based on the available data.
The estimation method should be appropriate to the clarity of the scope and the quality of the data. When the project is in its early stages, it can start with similar data; once the work package is clear, more detail is needed and assumptions need to be checked.
| Method | When should it be used? | Things to check |
|---|---|---|
| Similar projects | In the initial stage, a quick estimate is needed. | Scale, scope, timing, price, and conditions vary. |
| According to parameters | There are reliable unit prices and volume relationships. | For example, labor hours × unit price; the scope of application of productivity and unit price. |
| From bottom up | The work has been broken down into sufficient detail. | Calculate each package separately and add them up; review the interface between packages and shared usage costs. |
| Three points | The outcome depends on uncertain scenarios. | Clearly state the optimistic, probable, and pessimistic scenarios along with the assumptions; choose the appropriate model for evaluation. |
| Expert reviews, price comparisons | Insufficient data or feasibility test required. | Same scope, acceptance standards, taxes/fees, and payment terms. |
For example, the labor cost estimate for a testing package is 160 hours × 500,000 VND/hour = 80 million VND. If the unit price already includes contractor management costs, it is necessary to verify this before adding a similar management fee. The time required for approval or rework should also be considered when justified.
Costs for error prevention, quality control, and error handling should be included in appropriate packages. Contingency planning must be based on the project's risks, uncertainties, and policies; there is no one-size-fits-all approach.
The cost estimate differs from the pricing method used with the customer.
Hourly rates, lump sums, cost-plus pricing, and value-based pricing are all pricing methods or contractual mechanisms. They influence how risk is allocated but do not replace the need for resource allocation.
Lump-sum contracts require clear control over the scope of work and any changes outside the scope. Hourly contracts need to track approved time, unit price, and limits. Cost-plus pricing mechanisms require a unified cost calculation and verification method. Value-based pricing still requires internal cost checks to assess transaction efficiency.
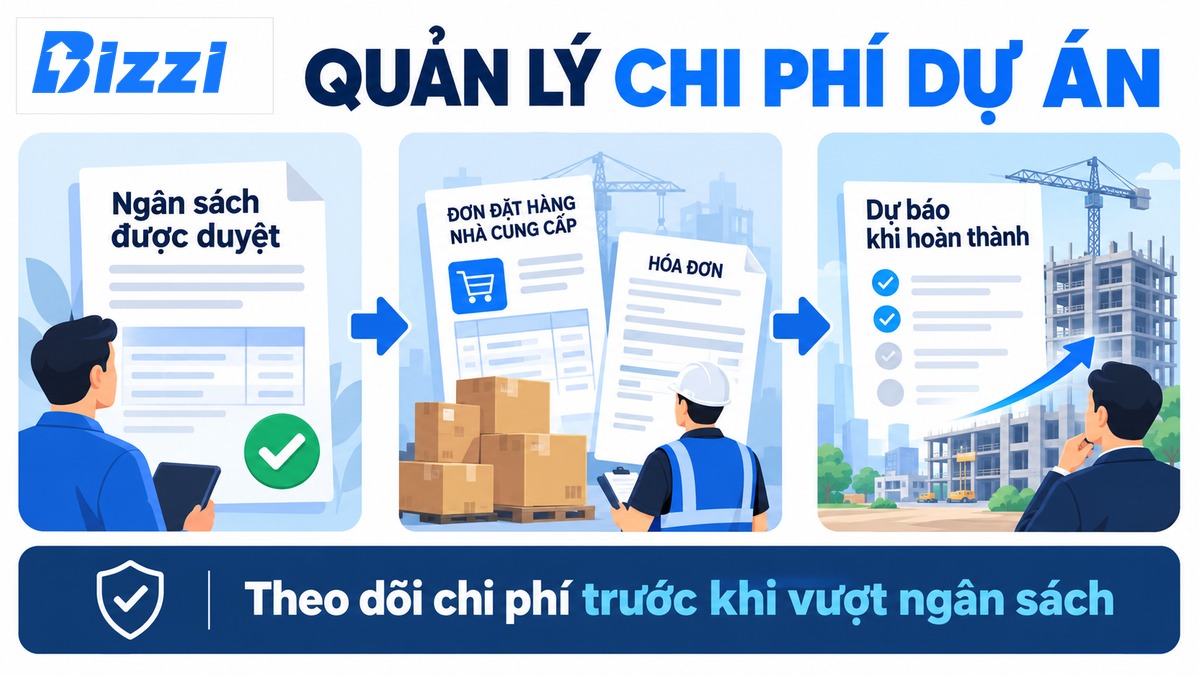
Project cost management process from budgeting to project closure.
A process can be implemented in the following six steps, with outputs and validators at each step. The level of detail needs to be appropriate to the scale of the project; small teams can share roles, but there must still be a clear distinction between the proposer, the reviewer, and the approver.
- Define the scope and rules for tracking. Define the deliverables, acceptance criteria, work package, responsible person, reporting period, currency, and how taxes/fees are handled in the data. The output is a list of tasks with identification codes, assumptions, and exclusions that are mutually agreed upon by all parties.
- Prepare a well-founded budget. Calculate the volume × unit price for each package, adding reasonable overhead costs and risk assessment. Record the quote, data source, date, assumptions, and author. When information is insufficient, use an estimated range and specify the areas needing clarification instead of presenting a falsely precise number.
- Approve the budget and funding schedule. Consolidate packages, phase them according to plan, and record the approved version for comparison. Separate the cost budget from the advance payment, acceptance, and final payment schedules: the payment timing may differ from the resource utilization timing.
- Note the proposal, commitment, and associated costs. Attach project codes to purchase requests, orders, contracts, timesheets, acceptance reports, and invoices. Track signed but uncompleted obligations separately, along with incurred costs and payments. Verify duplicate codes, documents, and transactions before consolidating.
- Compare, forecast, and handle discrepancies. On the same closing date, compare progress and costs against the plan; update the remaining work. State the cause, impact, solutions, decision-maker, and deadline for resolution. Reporting frequency depends on the rate of occurrence and level of risk; short projects require faster responses than overly long reporting periods.
- Close the chapter and learn from the experience. Compare the final acceptance, outstanding obligations, advances, and open commitments. Only release unused budget after reviewing the remaining obligations. Save the final version and the reasons for discrepancies to improve the budget for similar projects.
In step three, the business can develop the structural details. budget planning According to management needs, the project budget should still remain aligned with the project's specific scope and schedule.
For example, tracking budgets and forecasting completed costs.
A useful cost breakdown should indicate the project's completion cost, rather than simply reporting the amount paid. The example below uses millions of VND, the same project scope, the same closing date, and the same tax/fee basis.
| Tracking | Amount | Interpretation |
|---|---|---|
| Budget approved | 1.000 | Current comparative basis |
| Costs have been incurred. | 400 | Resources used, not uniformly reflected in the amount paid. |
| The commitment has not yet been fulfilled. | 250 | Value remaining to be fulfilled according to the contract/order. |
| Estimate the remaining amount beyond the above commitments. | 420 | The job is not included in the 400 and 250 categories. |
| Estimate total cost | 1.070 | 400 + 250 + 420 |
| Exceeding the projected budget. | 70 | 1,070 - 1,000, a decision on how to handle this is needed. |
In this example, the newly incurred cost ratio is 40% budget, but the forecast has exceeded it by 70 million VND. If 420 million already includes the committed 250 million, then 400 + 420 = 820 million must be used; adding 250 again would distort the forecast.
The tracking sheet should include the project/work package code, original budget, approved changes, current budget, incurred costs, open commitments, remaining estimates, end-of-period forecast, responsible person, and update date. This structure can be implemented on a spreadsheet and adapted to internal processes.
The project team confirms the remaining workload and obligations; the accountant verifies the generated figures; and the authorized person decides on adjustments. A single "remaining budget" column is insufficient if the work to be completed and the committed funds are not yet known.
Read the cost and completion schedule differences.
Spending less than planned isn't necessarily saving money if less work is completed than expected. For projects with task-based budgeting and objectively measurable progress, the value-based approach can be used to position costs against results.
On the closing date, PV represents the budget value of the work expected to be completed, EV represents the budget value of the work actually completed, and AC represents the actual cost incurred for the work. EV is not the amount paid by the customer or the revenue invoiced.
For example, let's assume: PV = 500 million VND, EV = 400 million VND, and AC = 450 million VND. Then the cost difference CV = EV − AC = − 50 million VND; the cost efficiency index CPI = EV ÷ AC ≈ 0.89. The project costs more than the budgeted value of the completed work. EV being lower than PV also indicates that the completed volume is lower than planned, according to this measurement method.
The definitions and formulas above are consistent with the guidelines. Read the obtained PMI values.. It is necessary to agree on completion criteria before calculating; progress rates based on self-estimated data without sufficient basis may lead to inaccurate indicators.
After identifying discrepancies, re-examine labor hours, unit prices, changes in volume, delayed recording, and acceptance criteria. Indicators are investigative cues; they do not automatically identify the cause and do not replace critical path progress checks or cash flow forecasts.
How are overhead costs allocated and changes approved?
Overhead costs require criteria that reasonably reflect the level of benefit or resource utilization. These can include labor hours, machine hours, area, or other criteria appropriate to the expenditure; choose the criteria first, apply them consistently, and maintain records.
For example, let's assume a support team has 60 million VND in expenses for the month, serving project A for 200 hours and project B for 100 hours. If support hours are considered appropriate, a total of 300 hours at an allocation rate of 200,000 VND/hour: A receives 40 million VND and B receives 20 million VND. Compare this to 40 + 20 = 60 million VND, and check directly recorded expenses to avoid redistribution.
When unforeseen circumstances arise, the proposer must describe the change, its reason, the affected work, the increase/decrease in costs, the impact on schedule, and the funding source. The project manager evaluates the options, the finance department verifies the figures and authority, and then submits the proposal to the person authorized to approve it.
- Keep the original budget and save the history of approved changes.
- Simultaneously update the scope, schedule, contract, and related forecasts.
- Separate approved changes, pending proposals, and unapproved expenses.
- Record the person responsible for implementation, the deadline, and proof of completion.
Don't increase the budget just to erase old discrepancies. If the work needs urgent attention, apply the proper mechanism authorized by the business and complete the decision-making process, instead of considering verbal agreements as full approval.
Address the causes of overspending while maintaining output.
Cost-cutting strategies should be based on the root causes and their impact on output. A blanket cut could lead to a shortage of testing personnel, prolong lead times, or shift costs to the warranty phase.
- The budget is incomplete or the scope is vague: Clarify the delivered products, update the remaining quantities, and submit a proposed adjustment plan.
- Unit price increased: Review the quotation deadline, suitable replacements, and total cost of use; don't just compare purchase prices.
- Retry or wait for approval: Address the underlying causes, quality, and delivery points before requesting a productivity increase.
- Outsourcing: Considering all contract management fees, quality control, handover, and post-handover responsibilities, outsourcing is not necessarily cheaper.
- Change the way you organize your work: Deployment phases can be broken down or scope prioritized, but a flexible approach does not automatically guarantee a reduction in overall costs.
Safety-related expenses, labor obligations, mandatory quality standards, and contractual commitments need to be assessed according to applicable conditions. With cuts in multiple departments, this could continue. business cost reduction strategy to balance benefits and long-term impacts.
Assign responsibilities and choose tools according to scale.
The project manager is responsible for compiling the plan, schedule, discrepancies, and proposals. Finance/accounting provides verified data; team leaders confirm resources and remaining work; the sponsor or authorized person approves the budget and changes.
Employees need to correctly assign project codes, submit documentation, and report any discrepancies promptly. Purchasing should track quotations, contracts, purchase orders, and unfulfilled commitments. Roles must agree on closing dates and data definitions to avoid one department reporting payments while another reports expenses in the same column.
Spreadsheets are suitable when the number of users and transaction volume are small, and there is someone to manage versions and check data. When multiple projects share resources, it is necessary to consider the tool's project code, permissions, approval process, documentation, modification history, and data export capabilities for comparison.
Before making a choice, test a real-world scenario: a request for funding for project A, proper authorization transfers, one invoice for multiple projects, and outstanding commitments. Examine how the overall system works, who can modify the data, and how duplicate transactions are handled. Task tracking software, expense tracking software, and accounting systems have different functions; it's necessary to identify the primary data source for each.
Frequently Asked Questions about Project Costs
Is project management cost the entire project cost?
Management costs cover expenses related to organization, coordination, and control. Total project costs also include implementation resources, contractors, materials, and other expenses within the approved scope. For construction projects, the scope and method of determining these expenses, as stipulated by relevant industry regulations, need to be considered separately.
What are prelim costs?
In some construction documents, preliminaries often refer to services related to site organization, preparation, or operation, and general work as specified in the particular document. Refer to the bill of quantities and contract terms to determine what is included; do not use this term as a percentage add-on for every project.
Is the remaining budget money available for immediate expenditure?
Inconsistent. Remaining obligations need to be excluded, and the financial plan, limits, and approval authority need to be checked. The remaining administrative budget does not automatically demonstrate sufficient bank funds or that the request has been approved.
Is it possible to use a fixed contingency rate for all projects?
Contingency planning should be determined based on risk, budget uncertainty, and approval policies. New projects with significant fluctuations require different assessments than recurring projects with existing data; avoid using a single ratio without a basis.
Where should we begin with project cost management?
Finalize the scope and assign responsibility, consolidate costs by task code, create a well-founded budget estimate, and then approve the budget. Afterward, regularly monitor incurred costs, commitments, and remaining work to make early predictions, instead of only summarizing at project completion.
When expenditure requests and supporting documents are scattered, it is difficult to keep project data fully updated. Businesses can discuss with Bizzi the scope of expense management and how to organize data according to project needs. When evaluating the solution, it is necessary to clarify which parts are handled by the expense system and which parts remain within the scope of work planning, accounting, or project reporting.





