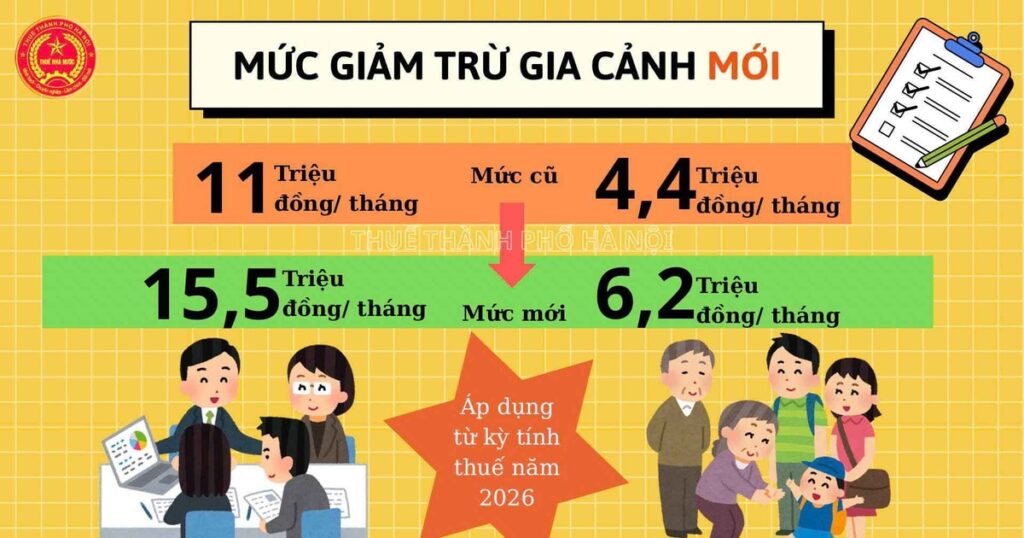
In 2026, personal deductions will no longer be applied when calculating taxes on income from business activities. A deduction of VND 15.5 million per month for the individual and VND 6.2 million per month for each dependent is applied to income from salaries and wages of resident individuals.
Therefore, if your income is solely from your business, you cannot use these deductions to subtract from your business income. If you are both employed and running a business, you need to separate the two sources of income: the salary portion, which can be deducted if eligible, and the business portion, which is subject to separate tax regulations.
Will household businesses be eligible for personal deductions in 2026?
No, if you are considering income generated from business activities. The deciding factor is not how the household is "declaring" their income, but whether the taxable income falls under the business income category or the salary and wage category.
Article 10 of the Personal Income Tax Law No. 109/2025/QH15 defines family allowance deductions as amounts deductible from taxable income before calculating tax. Income from salaries and wages of resident individual taxpayers.. Income from business activities is subject to tax liability determined according to a separate mechanism for household businesses and individual business owners.
| Sources of income | Family deduction | How to handle it |
|---|---|---|
| Income from business | Not applicable | Determine the obligations stipulated by regulations for household/individual businesses. |
| Salaries, wages | May apply | This applies if you are a resident individual and meet the eligibility requirements for the deduction. |
| There are two sources. | Separate | Don't add everything up and then apply a single subtraction formula. |
What will the personal allowance be in 2026?
Starting from the 2026 tax year, the applicable personal allowance will be:
| Deduction | Applicable level |
|---|---|
| Taxpayers themselves | 15.5 million VND/month |
| Calculated annually | 186 million VND/year |
| Each dependent | 6.2 million VND/month |
Common misconceptions: This is not a direct deduction from the household's revenue or business income. This deduction is subject to the tax calculation mechanism for salaries and wages.
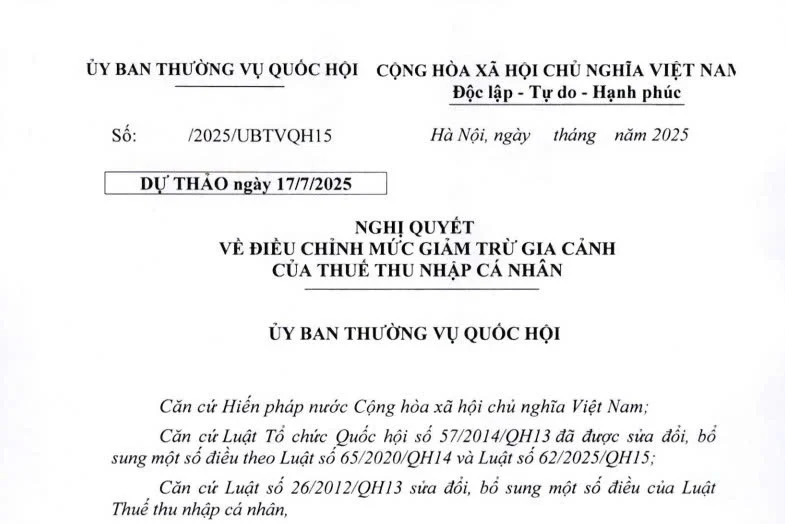
You can view the text and detailed explanation in the Bizzi documentation. Resolution 110/2025/UBTVQH15 and the personal allowance deduction for 2026.
Can a sole proprietorship register dependents?
If the head of the household also has income from salaries and wages, they can register dependents to claim a tax deduction on their salary income if they meet the eligibility requirements. Conversely, if income is solely from business activities, having or registering dependents does not generate a deduction for business income.
Decree 253/2026/ND-CP stipulates that taxpayers are entitled to deductions for dependents when they have registered for tax, registered their dependents, and have supporting documents as prescribed. Each dependent can only be claimed as a deduction once by one taxpayer per year.
For dependent groups subject to income requirements, Circular 87/2026/TT-BTC stipulates that the average monthly income from all sources during the year must not exceed... 3 million dong For cases falling within the scope of application.
How is tax deducted when someone is both a business owner and employed?
This case requires separate two sources of income. Do not add salary to business income, then deduct personal allowances and apply the salary tax rate to the entire amount.
| Revenue sources | Does GTGC apply? | Note |
|---|---|---|
| Salaries, wages | Maybe | Eligible for personal and dependent tax deductions. |
| Income from business | Are not | Determine tax obligations under tax policy for household/individual businesses. |
For example, you work as an office employee and also sell products online. Your salary from your job is determined as taxable income according to regulations for salaries and wages, and may be subject to personal deductions. The online business income is determined separately according to regulations for business activities.
Does the absence of personal deductions mean that business households are definitely required to pay personal income tax?
Are not. Personal deductions and business revenue thresholds are two different mechanisms.
| Mechanism | What is it used for? |
|---|---|
| Family deduction | Reduce taxable income before calculating tax on salaries and wages of resident individuals. |
| Business revenue threshold | Determine whether the household/individual business falls within the threshold for paying business-related taxes. |
According to Decree 141/2026/ND-CP, the revenue threshold for business households and individual businesses to be exempt from tax has been raised. 1 billion VND/year, effective from January 1, 2026.
Therefore, a household with only business income and revenue falling within the threshold exempt from personal income tax may not generate personal income tax from business activities. The reason is revenue threshold, This is not because the household is entitled to a deduction of 15.5 million VND for the individual or 6.2 million VND for dependents.
If you need to delve deeper into other obligations, you can read the article. Types of taxes that household businesses must pay.
Two changes in 2026 are easily confusing when reading the old guidelines.
Firstly, from January 1, 2026, household businesses and individual businesses will no longer be subject to the lump-sum tax method. Therefore, the guiding structure of "households paying taxes are not eligible for deductions, households declaring taxes are eligible for deductions" is no longer appropriate to explain personal deductions in 2026.
Secondly, the collection and payment of business license fees will also cease from January 1, 2026. The old versions still list business license fees as a regular obligation for business households and need to be updated before use.
To understand the transition from the old system to the new tax management approach, see the following article. What do household businesses need to prepare for after the abolition of lump-sum tax from 2026?.
Legal basis for personal deductions for business households in 2026
| Document | Related content |
|---|---|
| Personal Income Tax Law 109/2025/QH15 | Scope of application of personal deductions and deduction levels for salaries and wages. |
| Resolution 110/2025/UBTVQH15 | The allowance will be VND 15.5 million per month for the individual and VND 6.2 million per month for each dependent, starting from the 2026 tax year. |
| Decree 253/2026/ND-CP | Conditions, principles, and registration of dependents. |
| Decree 141/2026/ND-CP | Raise the tax-exempt revenue threshold for household/individual businesses to 1 billion VND. |
| Resolution 198/2025/QH15 | The lump-sum tax method will be abolished and business license fees will be terminated from January 1, 2026. |
After determining their tax obligations, what should business households be aware of regarding electronic invoices?
Personal deductions and electronic invoices are two different issues. After determining personal income tax obligations, the next step for a business household is to check invoice obligations based on actual revenue and operations.
According to Decree 141/2026/ND-CP, business households and individual businesses with annual revenue over 1 billion VND Electronic invoices must be applied according to regulations. If the revenue is 1 billion VND or less but the conditions are met and there is a need, registration for use may be granted.
To determine the correct type of invoice and how to process it, see the Bizzi guide. How to issue electronic invoices for household businesses in 2026. If you need to track legal changes from July 1, 2026, please refer to the following information. Decree 254/2026/ND-CP and Circular 91/2026/TT-BTC on electronic invoices.
Frequently asked questions
Will household businesses be eligible for personal deductions in 2026?
No deductions apply to income from business activities. Personal deductions apply to income from salaries and wages of resident individuals according to the Personal Income Tax Law 109/2025/QH15.
Can a sole proprietorship register dependents?
If the head of the household also has income from salaries and wages, they can register dependents to claim tax deductions for this income if they meet the conditions. If the household only has income from business activities, dependents do not reduce personal income tax from business activities.
Can individuals who declare their business be entitled to personal deductions?
The criteria should not be "declared or not declared". If the income in question is from business activities, the personal allowance does not apply simply because the individual has accounting records, invoices, or has declared the income.
What is the dependent deduction amount in 2026?
The deduction for each dependent is 6.2 million VND/month. This amount is applied within the mechanism of personal deductions for income from salaries and wages.
How is the personal allowance calculated when someone works for a company and also runs a business?
Salaries and wages may be eligible for personal deductions if conditions are met. Income from business activities is subject to separate tax regulations and cannot be directly deducted using personal allowances.
If a household business is not eligible for personal deductions, is it still mandatory to pay personal income tax?
No. The revenue threshold and tax regulations for household/individual businesses need to be checked separately. In 2026, Decree 141/2026/ND-CP raised the tax-exempt revenue threshold to VND 1 billion per year.
Conclude
Regarding the question "Are business households eligible for family deductions?", The correct way to determine this is to look at it. type of income:
- Income from business activities is not subject to personal deductions.
- Income from salaries and wages can be reduced by VND 15.5 million/month for the individual and VND 6.2 million/month for each dependent, if eligible.
- Not being eligible for personal deductions does not necessarily mean you are required to pay personal income tax from business activities. The revenue threshold and current tax regulations need to be checked separately.
If you are both self-employed and salaried, separate the two sources of income when determining your tax obligations. If you are solely self-employed, focus on revenue, tax calculation methods, declarations, and invoicing obligations instead of using personal allowances to deduct from your business income.