


Direct material costs are the value of raw materials and supplies actually used directly in the production of products or provision of services during the period. For example, fabric for clothing, wood for tables, and steel for machine frames are tracked by product, order, or production order.
To correctly calculate this expense, the accountant needs to identify the materials consumed, separate the surplus, and select the appropriate accounting entry according to the company's accounting system. The amount spent on materials, the amount withdrawn from inventory, and the cost included in the cost of goods sold may differ.
What are the components of direct material costs?
Materials are classified as direct costs when they are used directly in the production or provision of services and there is a basis for their aggregation and allocation to the cost object. That object could be a product, a group of products, a project, or a production order.
| Item | For example | How to determine |
|---|---|---|
| Main raw materials | Fabric for making clothes, wood for making tables, and semi-finished products purchased from outside for assembly. | Product composition; tracking quantity and value by production item. |
| Direct-use auxiliary materials | Sewing thread, finishing paint, cooking spices. | Collect directly upon measurement; allocate according to appropriate criteria if used jointly for multiple objects. |
| Direct fuel | Fuel used in a specific production process. | See usage patterns and tracking records. Not all energy expenditures are assumed to be direct materials. |
| General supplies and services | Shared machine repair materials, workshop lighting. | Classified according to function and accounting method; often needs to be tracked within general manufacturing costs rather than being included in direct materials. |
The same type of material can be classified differently depending on its use. Paint for product coating is a different case than paint for office renovations. Accountants need to read the requisition form and the intended use, not just the material name.
The value of materials issued for use is determined at actual cost. Directly related purchase costs may be included in the material value according to inventory regulations; normal storage and preservation costs do not automatically become direct material costs. Input VAT that is deductible is not included in the material value; the non-deductible portion is handled according to applicable regulations.
How to calculate the actual direct material costs during the period.
Start by examining the actual materials used in production, then compare them with surplus materials, recoveries, and any related adjustments. An internal reconciliation statement might use the following formula if the items have not yet been written off in the input data source:
Actual direct material costs = Materials remaining at production at the beginning of the period + Additional materials delivered during the period - Unused materials at the end of the period - Related cost recoveries and reductions.
All items in the formula are calculated based on value, the same object, and the same period. Beginning inventory here refers to the portion remaining at the production site, not the entire inventory of the enterprise. When reporting out-of-stock materials, the amount of materials returned to inventory has already been deducted; this amount is not deducted a second time. Scrap materials should only be recorded as a reduction according to the specific transaction and supporting documents, avoiding reductions in both the materials and cost statements.
For example, comparing the materials of a production order.
Suppose a production order has materials remaining in the workshop at the beginning of the period worth 10 million VND, and an additional 100 million VND is received during the period. At the end of the period, the unused materials are worth 8 million VND; the amount recovered and recorded as a reduction in the order's cost is 2 million VND. No deductions have been made in the materials delivery report yet.
Actual material cost = 10 + 100 − 8 − 2 = 100 million VND.
If, out of 100 million VND, 4 million VND is identified as exceeding normal costs, 96 million VND is included in the cost of goods sold; the remaining 4 million VND is treated as cost of goods sold according to applicable regulations. Determining the abnormal amount requires documentation and an assessment of the cause, not just relying on whether the actual amount is higher than planned.
Assuming the order only creates one type of product, completing 2,000 products, with no work-in-progress at the beginning or end of the period, and the entire 96 million VND is related to these products, then the direct material cost is: 48,000 VND/product. If there is work in progress or multiple products, it needs to be assessed and allocated before calculating the unit cost. This figure does not include labor and general manufacturing costs, so it is not the total cost of production.
Choose the accounting method before using account 621.
The journal entry to account 621 and the journal entry directly aggregating to account 154 cannot be used interchangeably. Before recording the transaction, check the accounting system, fiscal year, and inventory accounting method chosen by the business.
| Case | How to track materials in real time. | Points to check |
|---|---|---|
| Businesses are applying Circular 99/2025/TT-BTC. | The funds are accumulated in account 621, and at the end of the period, they are allocated or transferred to account 154; any amount exceeding the normal level is transferred to account 632. | This circular applies to fiscal years beginning on or after January 1, 2026. Accounting entries must be detailed by subject. |
| Businesses complying with Circular 133/2016/TT-BTC must file declarations regularly. | Accumulate production costs according to account 154; for example, direct material issuance: Debit account 154 / Credit account 152. | Track materials, labor, and manufacturing overhead separately to calculate the cost of goods sold. |
| Circular 133, periodic inventory | Account 154 reflects the value of work-in-progress products and services at the beginning and end of the period. | Do not apply the exact recurring journal entry table; refer to the instructions of the chosen method. |
Businesses applying Circular 133 need to compare it with their internal accounting regulations. This is in accordance with Clauses 2 and 4 of Article 10, as amended by Article 3. Circular 46/2025/TT-BTC (Effective from July 1, 2025), businesses may amend or supplement their chart of accounts according to the prescribed conditions, but this must not change the information or indicators on the financial statements, and they must issue accounting regulations when amendments or supplements occur. The examples in this article use the chart of accounts as guided by each accounting regime.
When it is necessary to gather labor costs, general manufacturing costs, and work-in-progress inventory valuation, follow the established procedure. Accounting for production costs according to the accounting system currently applied by the enterprise..
Accounting for direct material costs according to Circular 99
Account 621 reflects the cost of raw materials and supplies used directly in the production of products or the provision of services. The debit side records the actual value of materials used; the credit side records the amount returned to inventory and any transferred amounts. Account 621 has no ending balance.
| Major | Debit | Credit | Conditions and required documents |
|---|---|---|---|
| Direct material withdrawal from inventory | TK 621 | Account 152 | Delivery note and actual cost of goods sold; product details or production order. |
| Buy materials for immediate use, no warehousing required. | Account 621; Account 133 if there is deductible tax. | Accounts 111, 112, 141, 331… | Invoices, delivery receipts, and confirmation of commissioning. Non-deductible taxes are included in the value of materials as per regulations. |
| Unused materials are returned to the warehouse. | Account 152 | TK 621 | The entry form must be re-entered and verified against the production order. |
| The amount exceeding the normal level. | Account 632 | TK 621 | The records identify the excess amount; this portion is not included in the cost. |
| Transfer the portion included in the cost of goods sold. | Account 154 | TK 621 | The table compiles and allocates materials according to each cost object. |
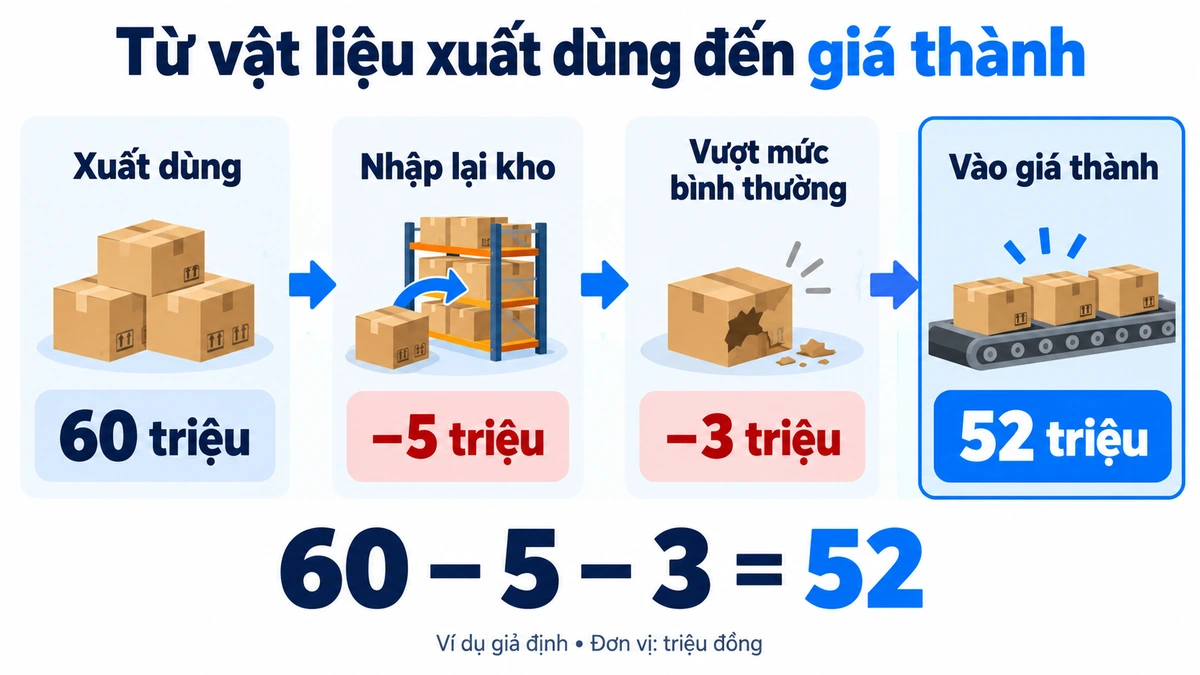
For example: materials worth 60 million VND were issued, and at the end of the period, 5 million VND were returned; 3 million VND is identified as exceeding the normal amount. The accountant records: Debit Account 621 / Credit Account 152: 60 million VND; Debit Account 152 / Credit Account 621: 5 million VND; Debit Account 632 / Credit Account 621: 3 million VND; Debit Account 154 / Credit Account 621: 52 million VND. The total credit entry to Account 621 is 60 million VND, equal to the debit entry in the example.
Common materials used in BCC contracts
In the accounting department for business cooperation contracts, shared material costs are aggregated in detail according to the contract in account 621; input tax is recorded in account 133 if applicable. When allocating to the parties, an allocation table with confirmation from all parties is required: debit account 138, credit account 621; the tax portion is recorded as credit account 133 if input tax is divided, or credit account 3331 if input tax has been fully deducted and output tax must be increased. The method of recording depends on the actual tax status of the contract; it is not defaulted to credit account 3331 for every allocation.
Materials delivered to external processing units require tracking of both ownership and processing results. Process Accounting for outsourced processing costs Separate the delivery of materials, processing fees, and receipt of finished products.
How are shared materials allocated across multiple products?
Prioritize direct aggregation for each object when reliable data is available. For shared items that cannot be individually identified, select criteria that reflect material usage and are appropriate to production characteristics, such as the standard consumption rate for actual output.
Cost allocation for object A = Total cost to be allocated × Criterion of A / Total criteria of all objects.
Suppose there are 90 million VND worth of shared materials to be allocated between two products. According to the actual production standard, A corresponds to 600 kg, and B corresponds to 300 kg. A receives 90 × 600 / 900 = 60 million VND; B received 30 million VND. The total allocation remains at 90 million VND.
Only allocate by the number of products when the products have equivalent consumption levels or the allocation method has a suitable basis. If product A requires more material than product B, allocating equally by quantity may lead to inaccurate cost calculations for each product. Keep the allocation method, data source, calculation method, and the person responsible for verification along with the allocation table so that data can be easily retrieved if it changes.
Prepare an estimate and identify the causes of price and quantity discrepancies.
Material estimates are derived from projected production volume, consumption norms, and projected unit prices. Norms can be established from technical specifications and historical data (excluding anomalies), and then adjusted when design, technology, or input quality changes occur.
Estimated material consumption = Projected production volume × Material consumption rate per product × Projected unit price. With multiple materials, calculate the cost of each type separately and then add them up. The material purchase budget also needs to consider the desired beginning and ending inventory and delivery schedule; the amount needed to purchase does not always equal the projected consumption.
Compare the same output to separate the difference.
For example, a management assumption: the actual required output is 1,000 kg according to the standard, with a standard unit price of 50,000 VND/kg. The actual output used is 1,050 kg at a unit price of 52,000 VND/kg; all values are based on the same calculation method, excluding deductible taxes.
- Price difference based on usage volume: (52,000 − 50,000) × 1,050 = 2,100,000 VND disadvantage.
- Quantity difference: (1,050 − 1,000) × 50,000 = 2,500,000 VND disadvantage.
- Total difference: 54,600,000 - 50,000,000 = 4,600,000 VND, which equals 2,100,000 + 2,500,000 VND.
Here, the price difference is based on quantity. used. If a business calculates the price difference at the time of purchase based on the quantity purchased, it needs to compare the remaining inventory before adding the difference in the quantity used.
Price increases may result from changes in suppliers, specifications, or delivery costs. Quantity increases may be due to input quality, losses, handling, machinery, or outdated standards. Purchasing should investigate the cause of the price increase; production and engineering should investigate consumption; and accounting should check the period, unit of measurement, and recording method. Adverse differences in the management report are not sufficient grounds to conclude that these are excess expenses that should be recorded in account 632.
Control from purchasing to pricing.
A reliable cost estimate should link production needs to actual goods received, materials used, and invoices. The following checks help identify discrepancies before finalizing the cost:
- Identify needs and approve purchases: Use production plans, standards, and inventory to determine the quantity to purchase. Compare quality, delivery conditions, and total costs instead of just choosing the lowest price offer.
- Counting and checking the quality of incoming materials: Record the quantity, specifications, batch number, missing or substandard goods; clearly separate the received portion from the portion awaiting processing.
- Record incoming and outgoing goods by object: Standardize material codes, units of measurement, order codes, and recording times; archive return documents, order transfers, and retrieval documents.
- Reconcile inventory with accounting records: Conduct physical inventory, compare quantities and values; verify discrepancies due to timing, unit conversion, cost of goods sold, or missing documentation.
- Review of end-of-period expenses: Inspect unused materials, recovered items, irregularities, allocation criteria, and transfer amounts. Monitor corrective actions to prevent recurrence in subsequent periods.
When the delivery number, the actual received number, and the invoice number differ, each document must be checked. Instructions Prepare and verify warehouse receipts. Explain how to record actual inventory receipts and handle discrepancies between inventory and accounting records.
The necessary supporting documents include purchase invoices, input slips, output slips, delivery notes, related payment or advance payment documents, allocation tables, and records of handling material losses. A correctly formatted invoice does not replace confirmation that materials were used in production; a correctly formatted output slip does not fully prove the book value.
When dealing with numerous material codes and production orders, inventory software or ERP systems help organize material and cost data according to a specific configuration. Accounting still needs to verify input data, pricing policies, and adjustments. Management benefits depend on data quality, the frequency of standard updates, and coordination between departments.
Frequently Asked Questions about Direct Material Costs
Are materials purchased and received into inventory already considered direct material costs?
It's impossible to draw conclusions based solely on the purchase. It's necessary to distinguish between materials remaining in inventory and those directly used in production or services, and to correctly identify the period and the party responsible for the expense.
How is account 621 different from account 154?
According to Circular 99, Account 621 separately aggregates direct material costs and then transfers them at the end of the period; Account 154 aggregates work-in-progress production and business costs to calculate the cost of goods sold and may have remaining work-in-progress balances. According to Circular 133, the aggregation method depends on the inventory method and does not mechanically apply the process of Account 621.
Should material costs exceeding the budget be fully transferred to account 632?
No. The cause and the amount exceeding the normal level must be determined according to accounting regulations. Increased market prices, changes in production volume, or inappropriately established standards may create discrepancies in the budget that may not yet be sufficient grounds to identify as an abnormal amount.
Does accounting for expenses in account 632 mean they are deductible when calculating corporate income tax?
No. Accounting recognition and deductible expense conditions are two different issues. When determining taxable income, businesses must compare records and tax regulations applicable to the specific expense.
Are direct material costs the entire cost of a product?
No. The cost may also include labor and appropriate manufacturing overhead, and work-in-process and adjustments should also be considered. Do not simply divide the total materials cost by the number of products in any case.





