Minutes of debt offset This is used to record the parties' confirmation of reciprocal receivables and payables and their agreement to offset obligations. If a difference remains after offsetting, the party with the remaining obligation continues to pay the remaining amount.
If you need it immediately, you can choose a Word template with 2 or 3 sides, an English template, or download one. Excel file for offsetting accounts payable in 2026 To compile the data and automatically calculate the balance after offsetting.
Download the 2026 debt offsetting agreement template.
Choose the template appropriate to the transaction situation. The Word file is used for drafting and signing the minutes; the Excel file is a tool to assist in compiling, calculating, and verifying data before preparing the document. Excel does not replace minutes or agreements that have been confirmed by the parties.
| Situation | Recommended model | Format |
|---|---|---|
| The two businesses have both accounts receivable and accounts payable to each other. | Minutes of offsetting debts between the two parties | Word |
| The debt is offset through a third party. | Three-party debt offsetting agreement | Word |
| Conducting transactions with partners using English. | English sample for offsetting accounts payable | Word |
| It is necessary to compile invoices/documents and calculate the amount to be deducted and the remaining balance. | Debt offsetting table | Excel |
WORD
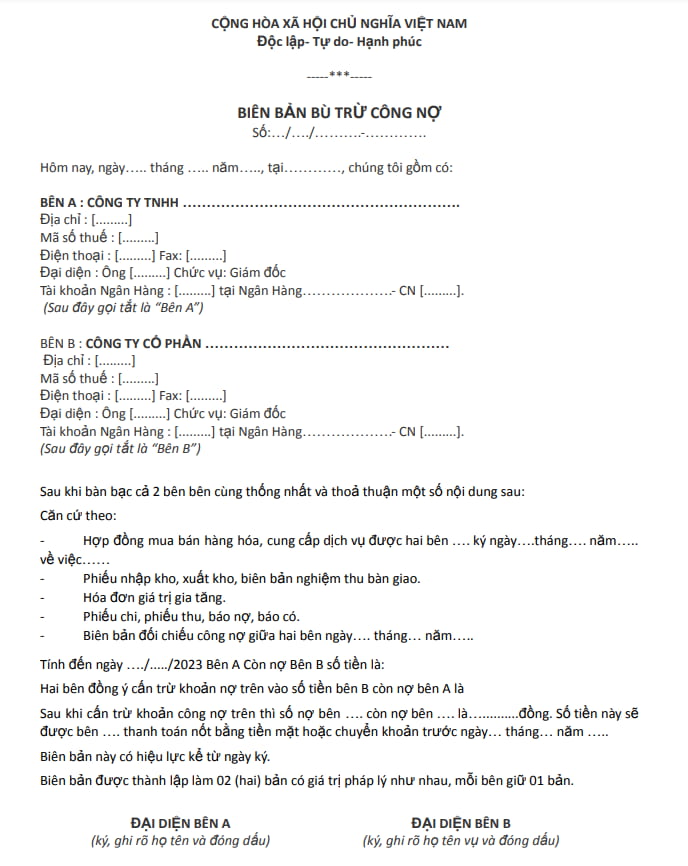
Sample agreement for offsetting debts between two parties.
Used when two entities have reciprocal payment obligations and jointly confirm the amount to be offset and the remaining balance to be paid.
Download Word template (both sides)
Or download common Word templates Currently available on Bizzi.
WORD
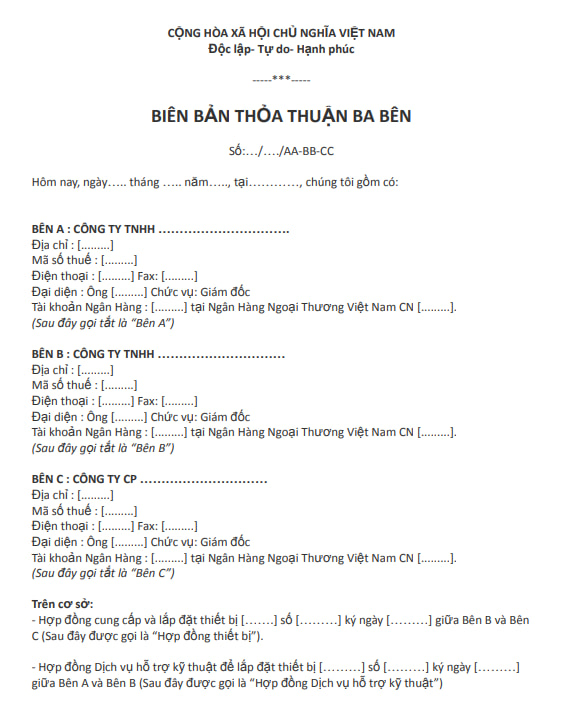
Sample three-party debt offsetting agreement
This is used when offsetting debts involves a third party. The agreement should clarify the obligations of each party before and after the offsetting.
WORD
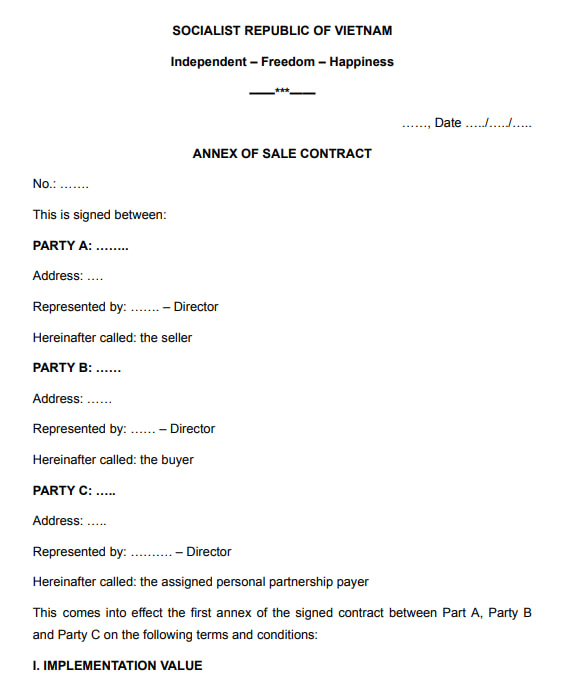
Sample debt offsetting agreement in English
Use this as a reference when working with foreign partners. The terminology should be reviewed to ensure consistency with the contract and applicable law governing the transaction.
EXCEL 2026
Table for offsetting debts between two parties and three parties.
The file includes an instruction sheet, a two-sided sheet, and a three-sided sheet; it supports document entry, two-way debt aggregation, and calculation of the balance after offsetting.
Download the Excel file for offsetting accounts payable in 2026.
3 parties
Calculate the balance yourself.
What is a debt offsetting agreement?
Offsetting debts This is a common term in accounting for using offsetting receivables and payables to offset each other. The 2015 Civil Code uses this term. offsetting obligations. When the obligations qualify for offsetting, the corresponding portion is terminated; if the values are not equal, the parties pay the difference.
Short example: Company A owes B 100 million VND, while B owes A 70 million VND. The two parties can offset the 70 million VND; after that, A will still owe B 30 million VND. These are two outstanding debts. They don't need to be equal. The compensation has just been paid.
Article 378 of the 2015 Civil Code stipulates this principle; Article 379 also lists cases where offsetting is not permitted, such as disputed obligations, alimony obligations, and certain personal compensation obligations. You can check this directly at [link/website]. National database of legal documents.
Are offsetting, offsetting, and reconciling debts different?
In business accounting practice, "offsetting accounts receivable and payable," "compensating accounts receivable and payable," and "counter-offering accounts receivable and payable" are often used interchangeably to describe reducing corresponding accounts receivable and payable. However, Reconcile accounts payable This is another step: reconciliation only compares and confirms the figures; it does not automatically terminate the payment obligation.
For a more detailed distinction between accounts payable transactions and offsetting operations in the software, please see the article. Offsetting, offsetting, and clearing debts by Bizzi.
Conditions and documentation for offsetting debts according to current regulations.
For VAT purposes, the key point to check is not only whether a record exists, but also whether the offsetting method is stipulated in the contract and whether the supporting documents are complete for each case.
| Case | Key documents to check |
|---|---|
| Offsetting the value of goods purchased against the value of goods sold/borrowed. | The contract specifies the method of payment; a record of data reconciliation and confirmation between the two parties. |
| Third party debt offset | The three-party debt offsetting agreement serves as the basis for the tax filing. |
| Offsetting related to borrowing or offsetting through a third party under the loan/borrowing structure. | A written loan/borrowing agreement is prepared in advance, along with appropriate money transfer documents, depending on the applicable circumstances. |
| After offsetting, there is still an amount to be paid in cash of 5 million VND or more. | Non-cash payment documents are required to qualify for input VAT deduction for the relevant portion. |
Regarding corporate income tax, point c, clause 1, Article 9 of Decree 320/2025/ND-CP requires non-cash payment documents for the purchase of goods, services, and other payments made in individual transactions with a value of... 5 million VND or more; The determination of non-cash payment documents is carried out in accordance with VAT regulations. See the document at National database of legal documents.
Documents should be prepared before drawing up the report.
Before calculating the offsetting amount, accountants should complete the reconciliation process to determine exactly which receivables and payables exist and which documents generate the balances. A traceable set of records is easier to verify than a statement that only records a total figure.
- The contract, appendix, or agreement specifies the transactional relationship and the appropriate method of payment.
- Original invoices and supporting documents give rise to accounts receivable and accounts payable.
- A detailed statement or reconciliation of accounts payable before offsetting.
- A record of offsetting/compensating debts, confirmed by all parties involved.
- A tripartite agreement when offsetting debts through a third party.
- The payment voucher will cover the difference if, after offsetting, there is still an amount payable.
- Detailed accounts payable records and accounting documents for comparison with the minutes.
If there is no balance confirmation step, you can use debt reconciliation form before proceeding to draw up the offsetting record.
Contents that should be included in a debt offsetting agreement.
An easily verifiable record should answer three questions: Where did the debt originate, which amounts were offset, and after the offset, how much does each party still owe?.
- Text information: The title of the minutes, the minutes number (if the business has a numbering system), the date, and the location where it was created.
- Information of the parties: Name of entity/individual, tax identification number or appropriate identifying information, address, and representative.
- Basis for the arising of liabilities: Contracts, appendices, invoices, supporting documents, or related reconciliation statements.
- Amount of debt before offsetting: Clearly state each receivable and payable item.
- Amount to be deducted: State the value that the parties agree to offset.
- Balance after offsetting: Determine which party is still obligated and the amount to be paid.
- Method for handling the difference: State the method and deadline for payment if there is any remaining balance.
- Validity and verification: The number of copies, effective date, signature of the authorized person, and seal if used by the business.
How to create a debt offsetting agreement in 6 steps
A record should be made after the figures have been reconciled; do not use an offsetting record as a substitute for the debt verification step.
- Collection of documents: Contracts, invoices, payment documents, and accounts receivable/payable ledgers.
- Compare the data: Confirm accounts receivable and payable and process any discrepancies before calculating the offsetting.
- Check the payment terms: Determine whether the contract/agreement includes an appropriate method of offsetting.
- Calculate the amount to be deducted: Determine the matching obligation and the remaining balance; you can use Bizzi's Excel file at the beginning of the article to check the calculation.
- Prepare and sign the minutes: Clearly state the basis, the figures before and after the deduction, and the remaining amount to be paid.
- Update and save the record: Process the difference, update the accounting records, and file the documents together in one set of documents.
For example, offsetting debts between two parties.
Suppose Company A owes Company B 100 million VND, and Company B owes Company A 70 million VND. If the obligations qualify and both parties agree to offset them, the result is determined as follows:
| Content | Amount |
|---|---|
| A must pay B before offsetting. | 100,000,000 VND |
| B must pay A before offsetting. | 70,000,000 VND |
| The amount to be deducted. | 70,000,000 VND |
| A still has to pay B. | 30,000,000 VND |
This result also shows that the two liabilities do not need to be equal in value. The remaining 30 million VND is A's obligation to continue paying B; the payment method needs to be handled in accordance with the contract and applicable tax conditions.
Common mistakes when offsetting accounts payable
The majority of the errors lie not in the calculations, but in the fact that the records fail to explain the relationship between the contract, invoice, accounts payable balance, and the offset.
- Using the 20 million VND benchmark from the old document: It no longer meets the above-mentioned conditions of 5 million VND.
- The contract does not specify the method of offsetting in cases where tax law requires it: This resulted in a lack of evidence in the application file.
- Just write the total: The lack of supporting invoices/documents makes it difficult to verify the source of the debt.
- Mismatched with offsetting: The reconciliation record confirms the figures but does not automatically replace the offsetting agreement.
- Three parties involved, but one party's confirmation is missing: It does not fully reflect the consensus of the stakeholders involved.
- The difference is not clearly defined: It is easy for the figures after offsetting to not match the accounting records or payment documents.
Frequently Asked Questions about Debt Offsetting Agreements
Is it mandatory to use a single, fixed form when offsetting debts between two parties?
There is no single template that fits all transactions. The template needs to accurately reflect the parties involved, the basis for the debt, the figures before and after offsetting, the difference, and confirmation from all parties. For tax documentation, it must also meet the requirements for supporting documents corresponding to the payment method.
Is it possible to offset debts between three parties?
This can be done when there is a real obligation relationship and the parties agree on the offsetting method. In the case of offsetting debts through a third party as a basis for VAT deduction, Article 26 of Decree 181/2025/ND-CP requires a three-party debt offsetting agreement.
Can two unequal debts be offset against each other?
Yes. Article 378 of the 2015 Civil Code stipulates that if the value of the obligations is not equivalent, the parties shall pay the difference.
What is the English term for a debt offsetting record?
In real-world transactions, you might encounter terms like: set-off agreement or cancerous blood. This is not a mandatory English term for all contracts; businesses should use terminology consistent with the main contract and the law governing the transaction.
Can an Excel file replace a debt offsetting record?
No. The Excel file provided by Bizzi is a tool to assist in compiling documents, calculating the amount to be deducted, and the balance. The actual documentation still requires minutes/agreements and other relevant documents appropriate to the transaction.
Do I need to submit a debt offsetting agreement to the tax authorities?
There is no general regulation requiring businesses to proactively submit each debt offsetting record to the tax authorities simply for the transaction to be recognized. Businesses need to prepare and maintain records to present when requested by the competent authority, depending on the specific circumstances.
After the deduction, what should businesses monitor?
The minutes only address a single point of confirmation and offsetting. Afterward, the business must still monitor remaining balances, payment deadlines, overdue amounts, and transactions awaiting reconciliation to avoid discrepancies in accounts payable figures between accounting, banks, and partners.
NEXT STEP
With Bizzi's debt management solution., Businesses can manage accounts receivable by invoice, contract, and customer; track DSOs (Demand Sales Orders), report aging of accounts receivable; manage pending payments and reconcile payments with bank statements.